Wednesday Nov 04, 2026
Wednesday Nov 04, 2026
Wednesday, 4 November 2026 00:00 - - {{hitsCtrl.values.hits}}

Chairperson Krishan Balendra
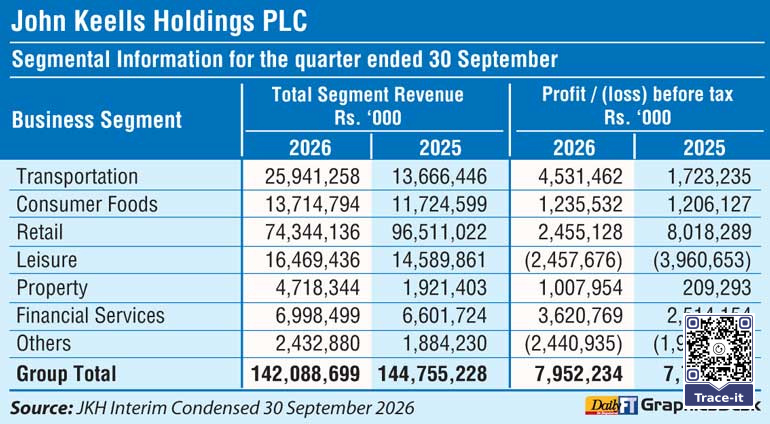
John Keells Holdings PLC (JKH) yesterday said profit attributable to equity holders of the parent rose 213% to Rs. 5.17 billion in the second quarter of 2026/27, from Rs. 1.65 billion a year earlier, while Group profit before tax (PBT) increased 2% to Rs. 7.95 billion from Rs. 7.8 billion.
Group profit after tax (PAT) of Rs. 5.82 billion was an increase of 39% over the Rs. 4.20 billion recorded in the corresponding quarter of the previous financial year. The company said the higher flow through to attributable PAT primarily reflected the lower effective contribution from John Keells CG Auto (JKCG), in which the Group has an ownership of 50%.
Group earnings before interest, tax, depreciation and amortisation (EBITDA) of Rs. 18.30 billion in the quarter was broadly in line with the Rs. 18.36 billion recorded a year earlier. Growth across most industry groups offset the materially lower contribution from JKCG, against an exceptionally strong comparative quarter in the previous year, which benefited from pent-up demand following the resumption of vehicle imports. Cumulative Group EBITDA for the first half of 2026/27 increased by 11% to Rs. 34.65 billion.
The year-on-year PBT comparison was similarly impacted by the strong comparative base at JKCG. The appreciation of the Sri Lankan Rupee during the quarter also had a net impact of Rs. 340 million on Group PBT. Excluding the impact of net exchange movements, Group PBT was Rs. 7.61 billion, against Rs. 8.04 billion a year earlier.
Colombo West International Terminal (CWIT), the project company of West Container Terminal (WCT-1), maintained its strong operational momentum, handling 502,351 TEUs and operating beyond full utilisation of its phase 1 capacity. CWIT became the fastest terminal in the Port of Colombo to handle two million TEUs, reaching the milestone within 18 months of starting operations. Phase 2 operations have commenced with the progressive commissioning of equipment, and the terminal remains on track for full operations in December 2026.
The Transportation industry group recorded an increase in EBITDA driven by a very strong performance in the Group’s bunkering business, Lanka Marine Services (LMS), with volumes increasing by 31% together with higher margins, and a higher contribution from CWIT.
Profitability improved across the Beverages and Confectionery businesses, supported by volume growth of 10% in carbonated soft drinks and 7% in Confectionery, while the Convenience Foods business also recorded improved volumes and profitability.
The Supermarket business recorded 13% same store sales growth, supported by higher basket values and customer footfall. EBITDA increased marginally despite higher electricity and distribution costs, reflecting scale and operational efficiencies.
As anticipated, JKCG’s performance moderated against the exceptionally strong comparative quarter. JKCG handed over more than 2,400 vehicles during the quarter.
The Leisure industry group EBITDA reflected lower contributions from Colombo Hotels and Maldivian Resorts, including the impact of disruptions to travel from the conflict in the Middle East, partly offset by improved profitability across the Sri Lankan Resorts.
The ramp-up of City of Dreams Sri Lanka continued, with improving operating momentum across its key components. Higher occupancy and average room rates supported growth in hotel EBITDA, while the casino demonstrated an encouraging improvement in performance as operations progressively scaled up.
The Property industry group recorded EBITDA growth driven by profit recognition from residential and commercial unit sales at Cinnamon Life and residential sales at TRI-ZEN.
The Group’s share of profit after tax from Nations Trust Bank (NTB) increased, supported by a one-off tax credit arising from the acquisition of HSBC Sri Lanka’s retail banking business. This benefit was partly offset by integration expenses associated with onboarding the acquired business. Union Assurance (UA) recorded growth in gross written premiums, driven by renewal premiums.
JKH also noted that Fitch Ratings upgraded Sri Lanka’s sovereign credit rating to ‘B-’ from ‘CCC+’, which it described as a significant milestone reflecting the progress achieved in restoring macroeconomic stability.
While the Group’s carbon footprint and water withdrawal increased in absolute terms, operational intensity metrics across key businesses in the Consumer Foods, Leisure and Transportation industry groups, which account for the majority of the Group’s carbon footprint and water withdrawal, reflected improved efficiency.
The Board declared a first interim dividend of 10 cents per share, to be paid on or before 2 December, 2026.