Friday Sep 18, 2026
Friday Sep 18, 2026
Thursday, 17 September 2026 15:47 - - {{hitsCtrl.values.hits}}
By Madhuri Peiris
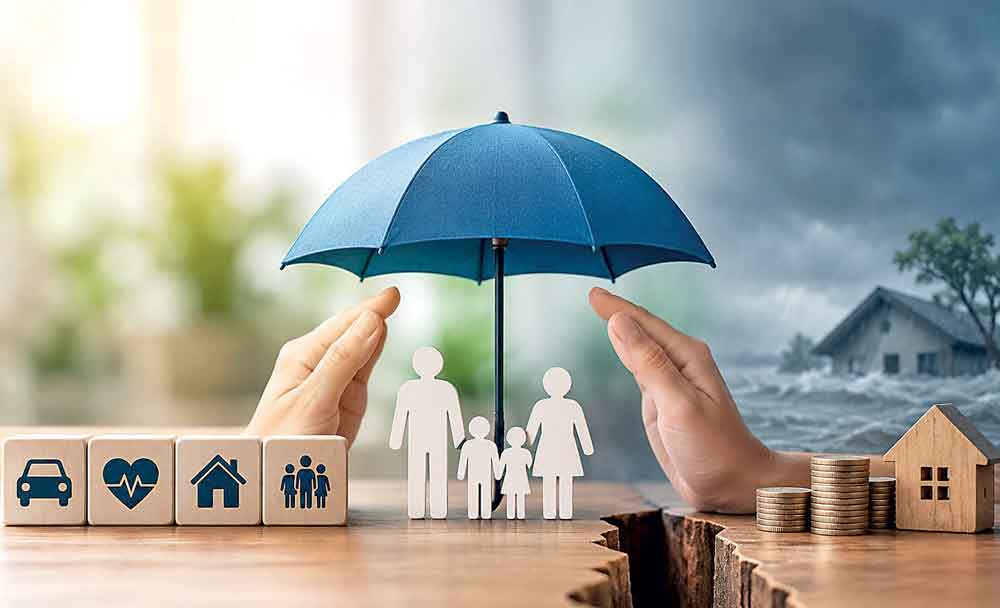
Walk into almost any of our households, and you will likely find at least one insurance policy tucked away in a drawer. It might be a motor policy renewed each year due to legal necessity, a life policy bought decades ago as a favour to a relative working in the industry, or a health plan attached to an employer. Insurance, in that sense, is not unfamiliar to us. Yet familiarity is not the same as protection. Beneath the surface of widespread policy ownership lies a much less comfortable truth: most of us remain significantly underinsured, and many do not realise it until a crisis forces us to find out.
Owning a policy is not the same as being covered
One of the most persistent misconceptions among us is the belief that having “an insurance policy” is the same as having adequate protection. In practice, coverage levels often fall far short of real financial need. A life insurance sum assured chosen ten or fifteen years ago rarely accounts for inflation, rising medical costs, or a family’s current lifestyle. A health policy with a low yearly limit can run out after just one hospital stay, especially if it involves surgery or intensive care. A motor policy that only meets the legal minimum offers little comfort after a serious accident with extensive third-party liability.
This gap between what people hold and what they actually need is what industry professionals refer to as the protection gap. It is not necessarily about the absence of insurance, but about the mismatch between coverage and real-world risk. Many families discover this gap only during a claim, when they realise the payout covers a fraction of the actual loss.
Why the gap persists
A few different reasons cause this problem, and each one makes the others worse. Affordability is a major barrier for many people. With household expenses rising due to inflation and financial pressures in recent years, many families see insurance as an extra cost rather than something essential. When money is tight, insurance is often one of the first expenses they consider cutting. Awareness is another major factor. Financial literacy around insurance products is still limited outside urban centres and professional circles. Many people do not fully understand the difference between term life and endowment policies, what a health insurance sub-limit means, or how depreciation affects a motor claim. Without this understanding, buying decisions are often driven by whoever sells the policy rather than by an honest assessment of personal risk.
Trust matters too. Some people have had bad experiences with insurance, like slow claim payments or arguments over what’s covered. Others have just heard these stories from friends or family. This makes them doubt insurance altogether. Because of this doubt, some people avoid buying enough coverage, even if they can afford it, since they’re not sure they’ll actually get paid when they need it most.
Culture plays a part as well. Many people buy insurance only because they have to, like when a bank requires it for a loan, or because someone they know asked them to, not because they planned it as part of their finances. Life insurance especially can feel uncomfortable, since it reminds people of death, something most prefer not to think about.
Where the gap shows up most
The protection gap is not uniform across product categories. Health insurance is arguably where the shortfall is most visible, particularly as private healthcare costs continue to climb and public hospital capacity remains under pressure. Many working people rely solely on employer-provided group health cover, which can lapse the moment they change jobs or retire, leaving a dangerous window of complete exposure.
Life insurance penetration remains comparatively low as well, especially outside the segment of the population already engaged with formal banking and financial products. Property insurance, meanwhile, is often overlooked entirely by homeowners who assume disasters will not affect them, despite the country’s exposure to flooding and other weather-related risks.
Motor insurance is the exception in terms of reach, largely because third-party cover is a legal requirement. But even here, many drivers choose the cheapest available option rather than comprehensive cover that would actually protect their own vehicle and finances.
Closing the gap
Fixing the underinsurance problem in Sri Lanka will take work from different sides. Insurers need to make simpler, clearer products and explain their value in plain language instead of confusing terms. Regulators can help by educating consumers and pushing insurers to settle claims fairly, which will rebuild public trust. As for individuals, the first step is simple but often ignored: honestly checking your current policies and asking whether they’d really be enough if something bad happened.
Insurance cannot prevent misfortune, but adequate coverage determines whether a setback becomes a temporary inconvenience or a lasting financial crisis. For many of our households, closing that gap between having insurance and having enough of it may be one of the most important financial decisions we never think to make until it is too late.