Friday Sep 18, 2026
Friday Sep 18, 2026
Thursday, 17 September 2026 15:25 - - {{hitsCtrl.values.hits}}
The future of life insurance in Sri Lanka will not be shaped by insurers alone. It will require partnership across regulators, government, healthcare providers, banks, digital platforms, employers, advisors and communities. Financial literacy must improve, distribution must become more inclusive, products must be designed around real needs and claims experiences must reinforce public trust
|
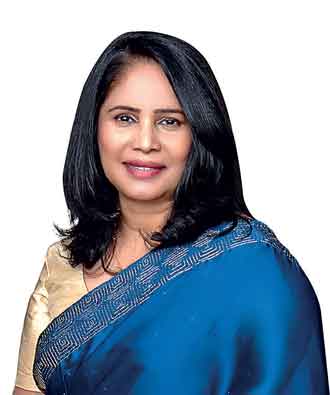
Chathuri Munaweera |
Insurance industry of Sri Lanka stands at a significant inflection point. For decades, insurance has often been viewed as a product to be sold rather than a promise to be delivered. That perception is now evolving. As households face rising healthcare costs, longer life expectancy, changing family structures and greater economic uncertainty, life insurance has a far larger role to play as an essential pillar of national resilience.
The opportunity before us is significant. Sri Lanka remains an underpenetrated insurance market and this protection gap is not just a statistic. It represents families without adequate safeguards, businesses exposed to unexpected shocks and communities that may struggle to recover when illness, loss or disaster strikes. The national ambition to double insurance penetration by 2030 is therefore both timely and necessary, supported by a regulatory roadmap that gives the industry a clear direction for transformation.
However, the true measure of progress should not be penetration alone. The deeper question is whether more Sri Lankans are better protected, better informed and better prepared for life’s uncertainties. Growth that does not build trust will be fragile and expansion that does not improve customer outcomes will be incomplete. The industry’s next chapter must therefore be defined not only by scale, but by relevance, responsibility and impact.
Sri Lanka’s demographic and health realities make this more urgent. An ageing population, a rising dependency ratio and the growing prevalence of non-communicable diseases are reshaping household financial needs. Families are living longer, but they are also facing longer periods of healthcare expenditure, caregiving responsibility and retirement planning. In this context, life insurance must move beyond traditional savings and protection propositions to support prevention, encourage healthier behaviours, enable early intervention and help customers make more confident long-term decisions.
For companies with deep local roots and access to global leadership, like AIA, the responsibility is especially clear. Local understanding gives insight into the lived realities of Sri Lankan families, while global expertise brings tested models, advanced analytics, product innovation, governance frameworks and digital capabilities. The most effective insurers of the future will be those that bring these strengths together, adapting global best practice to Sri Lanka’s realities and creating propositions that are affordable, accessible, simple to understand and meaningful across life stages and income segments.
Technology will be central to this transformation, but it must be guided by purpose. Digital onboarding, data-driven underwriting, automation, customer service platforms and artificial intelligence can make insurance faster, more efficient and more inclusive. Yet every innovation decision must ask whether it creates tangible value for the customer and whether it can be adopted responsibly, with clear objectives, proactive governance, appropriate safeguards and long-term sustainability.
As the industry expands access to protection, trust must remain its most valuable asset. Customers entrust insurers with their financial future, personal information and, often, their most vulnerable moments. That trust must be earned continuously through transparency, fair conduct, strong information security, responsible advice and a clear commitment to customer outcomes. In a more digital insurance ecosystem, confidence will depend as much on how securely and ethically we use data as on how quickly we deliver services.
The future of life insurance in Sri Lanka will not be shaped by insurers alone. It will require partnership across regulators, government, healthcare providers, banks, digital platforms, employers, advisors and communities. Financial literacy must improve, distribution must become more inclusive, products must be designed around real needs and claims experiences must reinforce public trust.
For life insurers, this is both a commercial opportunity and a social responsibility. We have the ability to mobilise long-term capital, support household resilience, promote healthier lives and contribute to national economic stability. The companies that lead in this new era will be those that place purpose and performance side by side, using innovation not merely to grow faster, but to serve better.
Sri Lanka’s protection gap is not simply an industry challenge. It is a national opportunity. If we act with ambition, discipline and humanity, life insurance can become one of the most powerful enablers of financial inclusion for Sri Lankan families. The next chapter of our industry must therefore be about more than selling policies. It must be about helping people live with greater security, dignity and hope. It must be about helping Sri Lankans live healthier, longer and better lives today and in the future.