Friday Sep 18, 2026
Friday Sep 18, 2026
Thursday, 17 September 2026 15:50 - - {{hitsCtrl.values.hits}}
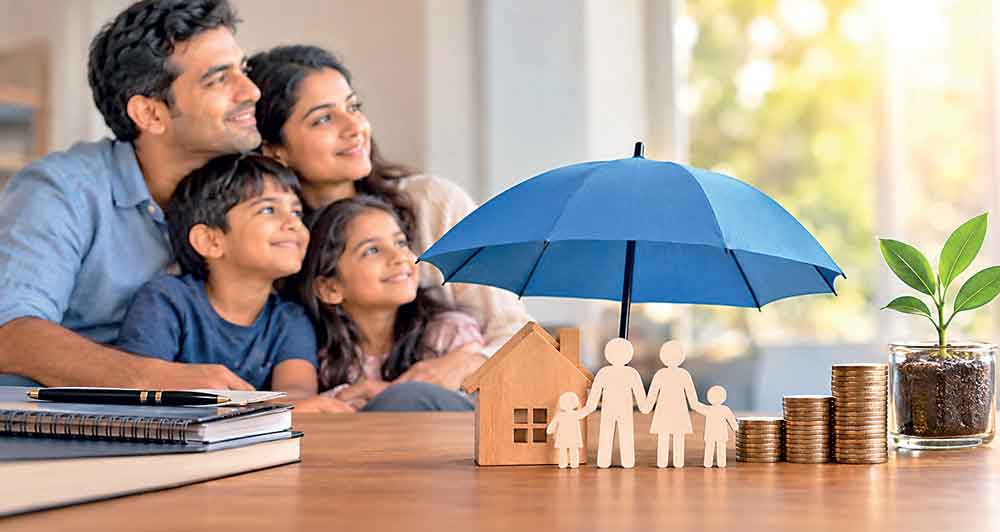
For many of us, life insurance still feels like something you buy only when you are older, or something meant only for wealthy families. This is a misunderstanding. Life insurance is one of the simplest tools available to protect the people who depend on you. It is not just about death. It is about making sure your family can continue their life with dignity, even if you are no longer there to provide for them.
What Life Insurance Really Does
Actually, life insurance is a promise. You pay a small amount regularly, known as a premium, and in return, the insurance company promises to pay your family a lump sum if something happens to you. This money can help cover daily household expenses, children’s education, outstanding loans, and other financial responsibilities that do not stop simply because a family has lost its main earner.
But modern life insurance products have grown beyond this basic idea. Today, many insurers here in Sri Lanka offer plans that combine protection with savings. These are often called endowment plans or savings-linked policies. A part of your premium goes toward life cover, and another part builds up as savings over the years. When the policy matures, you receive a payout even if nothing has happened to you. This makes life insurance useful not only for protection, but also for building long-term financial goals such as retirement, a child’s higher education, or buying a home.
When Should You Consider Life Insurance?
There is no single age that is correct for everyone, but there are clear moments in life when getting life insurance becomes important.
The most obvious trigger is when someone else starts depending on your income. This usually happens when you get married, have children, or take on responsibility for aging parents. If your income stopping suddenly would cause financial hardship for people you care about, that is a strong sign you need cover.
Taking a large loan is another good reason to consider life insurance. Many of us take housing loans, business loans, or vehicle loans that run for many years. If the borrower passes away before the loan is repaid, the burden often falls on the family. A life insurance policy can be structured to clear such debts, protecting your family from inheriting financial stress along with their grief.
Starting a career early is also a good time to think about insurance, even before marriage. Premiums are generally lower when you are young and healthy, so buying a policy early can lock in more affordable rates for many years. Waiting until you are older, or until health problems appear, usually makes insurance more expensive or harder to obtain.
How Much Cover Is Enough?
This is the question most people struggle with, and there is no fixed number that works for everyone. However, financial planners often suggest a simple starting point. Your life cover should be enough to replace your income for several years, while also covering major financial obligations.
A practical way to think about it is to add up your outstanding loans, your children’s future education costs, and daily household expenses for a reasonable number of years, perhaps ten to fifteen. From this total, you can subtract any existing savings or assets your family could use. The remaining figure gives a rough idea of how much life cover you actually need.
It is also important to review this amount over time. As your income grows, as you take new loans, or as your family grows, your insurance needs may increase. A policy bought ten years ago may no longer be enough to protect your family today.
Choosing the Right Type of Policy
Term insurance offers pure protection at a lower cost, making it a good option for those who want high coverage without a large monthly premium. Savings-linked or endowment policies suit those who want to combine protection with disciplined long-term saving, even if the premiums are higher.
Many families in Sri Lanka find a combination approach useful. They may take a basic term policy for strong protection, along with a smaller savings-linked plan to build funds for retirement or a child’s future.
A Decision Worth Making Early
Life insurance should not be seen as a burden or an unnecessary expense. It is a practical tool that brings peace of mind. Thinking about it early, understanding your family’s real financial needs, and choosing a policy that matches your life stage can make a significant difference in how well your loved ones are protected. In the end, life insurance is not just a policy. It is a quiet promise that your family’s future will remain secure, no matter what happens.(MP)