Saturday Sep 26, 2026
Saturday Sep 26, 2026
Thursday, 17 September 2026 15:58 - - {{hitsCtrl.values.hits}}
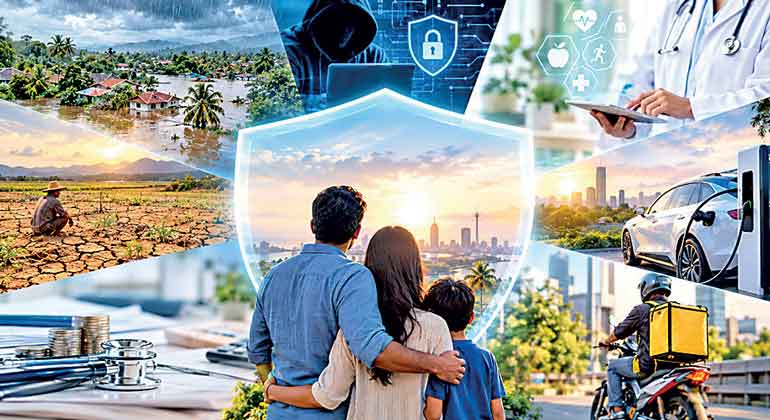
For decades, buying insurance meant sitting across a table from an agent, filling out long paper forms, and waiting days or even weeks for a policy document to arrive. Claims meant visiting branch offices, submitting stacks of paperwork, and waiting patiently for approval. That picture is changing rapidly. Across the nation, insurance companies are evolving with the technology in ways that are reshaping how people buy, manage, and claim insurance. This shift raises an interesting question. Is digital insurance finally making protection accessible to everyone, including younger Sri Lankans and those living outside major cities?
The Move to Mobile and
Online Platforms
Many insurance companies now offer mobile apps and websites where customers can browse policies, get quotations, and even purchase certain types of insurance entirely online. This is particularly true for simpler products such as motor insurance and basic health cover, which do not always require detailed medical assessments.
For a generation of Sri Lankans who are comfortable managing their banking, shopping, and communication through their phones, this shift feels natural. Instead of visiting a branch during working hours, a young professional can now compare policies and make a purchase in the evening, from home, in a matter of minutes.
Digital Claims Processing
One of the most noticeable improvements has been in the claims process. Traditionally, filing a claim involved submitting physical documents, waiting for manual verification, and often following up repeatedly for updates. Many insurers now allow customers to submit claims through mobile apps, uploading photographs of documents, bills, or damage directly from their phone.
This has considerably reduced the time taken to process simple claims, such as minor motor accident repairs or straightforward hospital reimbursements. Some insurers have also introduced tracking features, allowing customers to check the status of their claim online rather than calling repeatedly for updates.
The Role of Artificial Intelligence and Data Analytics
Behind the scenes, insurers are increasingly using artificial intelligence and data analytics to improve how they assess risk and detect fraud. For example, data analytics can help insurers identify patterns that suggest a claim may need closer examination, helping to reduce fraudulent claims that ultimately increase costs for all policyholders.
Artificial intelligence is also being used to speed up processes that once took significant manual effort, such as reviewing documents or answering common customer questions through chatbots. While these tools are still developing in our market compared to more advanced insurance markets globally, their use is steadily increasing.
Data analytics additionally allows insurers to design more personalised products, adjusting pricing based on individual risk factors rather than applying broad, generalised rates to everyone.
Reaching Younger Sri Lankans
Younger Sri Lankans, particularly those in their twenties and thirties, often approach financial decisions differently from previous generations. Many prefer researching options independently online before speaking to anyone, and they value convenience and transparency in pricing.
Digital insurance platforms cater well to this preference. Clear online comparisons, transparent pricing displayed upfront, and the ability to purchase without pressure from a sales agent all appeal to younger buyers who might otherwise delay purchasing insurance altogether. This digital shift may be helping to close a long-standing gap, since younger populations have traditionally been underinsured compared to older, more established professionals.
Expanding Access
Beyond Major Cities
Perhaps one of the most meaningful impacts of digital insurance is its potential to reach people living outside Colombo and other major urban centres. In many rural and semi-urban areas, access to insurance branches and agents has historically been limited, making it harder for residents to learn about or purchase suitable policies.
Mobile apps and online platforms remove much of this geographical barrier. As long as a person has a smartphone and reasonable internet access, both of which are increasingly common across Sri Lanka, they can explore and purchase insurance products without needing to travel to a branch office. This has the potential to gradually increase insurance penetration in areas that were previously underserved.
However, challenges remain. Not everyone is equally comfortable going through digital platforms, particularly older individuals or those less familiar with smartphone applications. Language barriers and varying levels of digital literacy can also limit how effectively these tools reach every part of the population. Insurers will need to continue supporting traditional channels alongside digital ones to ensure no group is left behind during this transition.
A Gradual but Meaningful Shift
Sri Lanka’s insurance industry is clearly moving in a digital direction, and this shift brings real benefits. Faster claims, easier access to information, more personalised pricing, and greater convenience are already changing how people interact with insurance. For younger Sri Lankans and those living further from major cities, digital insurance offers a promising path toward greater financial protection.
Yet technology alone cannot solve every challenge. Combining digital convenience with continued human support, clear communication, and efforts to improve digital literacy will be essential if this transformation is to benefit all Sri Lankans, not just those already comfortable with technology. The move from paper policies to digital insurance is well underway, and its full impact will likely unfold over the coming years.
(MP)