Tuesday Oct 13, 2026
Tuesday Oct 13, 2026
Tuesday, 13 October 2026 02:54 - - {{hitsCtrl.values.hits}}
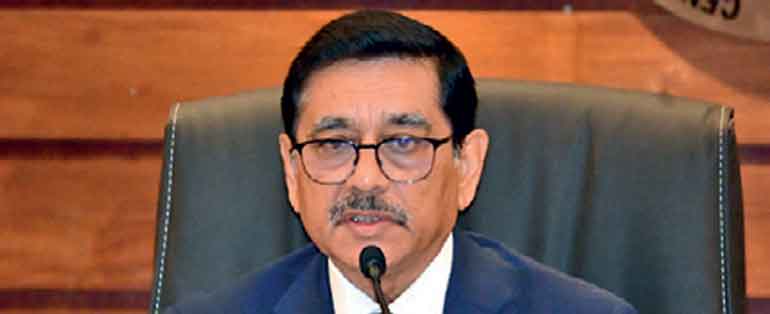
CBSL Governor Dr. Nandalal Weerasinghe – Pic by Sameera Wijesinghe
Vehicle and gold-backed loans now account for nearly a quarter of all credit extended by Sri Lanka’s banks and finance companies, as the reopening of vehicle imports and elevated gold prices fuelled a lending surge, the Central Bank of Sri Lanka (CBSL) said yesterday, releasing its Financial Stability Review 2026.
The two segments together made up 24.9% of total credit of licensed banks and finance companies at end-June 2026, up from 19.6% at end-2024, the CBSL said.
The share of motor vehicle-related credit, which comprises finance leases, hire purchase, and vehicle loans at finance companies together with banks’ leasing portfolios, rose to 12.9% from 9.8%. Demand built up during the import ban drove the increase after restrictions were relaxed in early 2025. Gold-backed lending rose to 12% from 9.8%, as global gold prices climbed steadily through 2025 to a record high in January 2026.
The concentration is far heavier at finance companies, where vehicle and gold-backed loans together accounted for 85.2% of total credit at end-June 2026, up from 82.6% a year earlier. Gold-backed loans alone made up 21.4%, up from 19.4%.
Finance companies’ vehicle-backed loans grew 46.3% year-on-year (YoY) at end-June 2026 and accounted for 65% of the sector’s credit expansion. Gold-backed loans grew 59.8% and contributed 25.8%. At banks, pawning grew 49.2% and raised its share of consumption loans to 37.1% from 32.1%.
The CBSL warned that such heavy reliance on two types of collateral leaves lenders exposed to falls in vehicle prices or gold prices, which have been volatile since end-January 2026. Early signs of strain are emerging at finance companies. Stage 2 loans, which are those showing a significant increase in credit risk, grew 75.5% for vehicle-backed lending and 279.2% for gold-backed lending in the year to June 2026.
CBSL Governor Dr. Nandalal Weerasinghe, however, said household debt remained below its historical average and was not yet a concern. “People are taking loans for economic activity, and only if that becomes excessive is it a problem,” he said, adding that this was why limits had been introduced for vehicle and gold-backed lending.
Dr. Weerasinghe noted that finance companies accounted for only 6-7% of total credit, although they were more concentrated in vehicle and gold-backed lending. Gold loans were commonly used for short-term working capital, particularly in agricultural areas, he said, but acknowledged that without a purpose-based classification of loans, it was difficult to determine precisely how the funds were used. Household credit data held by the Credit Information Bureau (CRIB) does not capture loan purpose and excludes gold-backed lending.
In response to the lending surge, the CBSL imposed a 70% maximum loan-to-value (LTV) ratio on gold-backed loans from 25 May. It also tightened the risk weights on gold-backed lending by banks and finance companies, removing the zero risk weight that some such loans previously carried. For finance companies, the higher risk weights took effect in September 2026. In two rounds, in November 2025 and May 2026, it cut the maximum LTV for new commercial vehicles to 60% from 80%, for other new vehicles to 40%, and for used vehicles to 60% from 70%.
The CBSL also tightened monetary policy in May. CBSL Senior Deputy Governor Dr. Chandranath Amarasekara said the impact was already visible, with private sector credit still growing in the latest month available but decelerating substantially. The CBSL expects these measures to moderate growth in both segments in the coming quarters.
Overall, the financial system remained resilient in the first half of 2026, supported by the economic recovery, improved fiscal conditions, and adequate capital and liquidity buffers at banks and finance companies, Dr. Weerasinghe said. He cautioned, however, that stability depended on sustaining the recovery, advancing fiscal consolidation, and maintaining prudent policies amid geopolitical tensions, energy price shocks, and tighter global financial conditions.
“Continued monitoring and timely policy intervention will therefore remain important in preserving financial stability,” he said.
The strain is showing in bank balance sheets. Banks’ liquidity ratios moderated as they shifted assets from Government securities to private sector lending, and short-term maturity mismatches widened. Capital adequacy ratios (CARs) declined as risk-weighted assets grew faster than capital, although buffers remained above regulatory requirements. Stage 2 loans at banks also rose in the second quarter, signalling potential deterioration in borrowers’ repayment capacity, which the report partly attributed to Cyclone Ditwah and the Middle East conflict.
The insurance sector remained adequately capitalised, though profitability moderated. Claims from Cyclone Ditwah increased reinsurance receivables and heightened underwriting, liquidity, and counterparty risks.
Domestic financial markets remained broadly stable, with the Financial Stress Index at relatively low levels. However, equity market performance moderated amid subdued investor sentiment, with weaker liquidity and higher volatility. Government securities yields rose across maturities, and foreign investor participation remained low despite a modest recovery late in the review period. The rupee came under pressure as Middle East tensions lifted foreign currency demand amid higher import and energy costs, before conditions improved on the back of policy measures and inflows from remittances, tourism, and exports.
The CBSL also flagged spillover risks from geopolitical tensions, renewed inflation, elevated energy prices, and climate-related shocks, along with rising cyber, operational, and third-party risks from the expansion of digital financial services. The outlook for financial stability remains broadly positive, it said, provided the recovery is sustained, fiscal consolidation progresses, and prudent policies continue.
On Sri Lanka’s third Mutual Evaluation of its Anti-Money Laundering, Countering the Financing of Terrorism and Countering Proliferation Financing (AML/CFT/CPF) framework, Dr. Weerasinghe said the on-site assessment by the Asia/Pacific Group (APG) on Money Laundering was scheduled for 26 October. Asked whether the country risked being grey-listed again, he said: “No. We are doing our utmost to prevent that, and we are working hard with all stakeholders to maintain our current rating and, if possible, improve it.” (CdeS)