Saturday Nov 07, 2026
Saturday Nov 07, 2026
Friday, 6 November 2026 00:21 - - {{hitsCtrl.values.hits}}
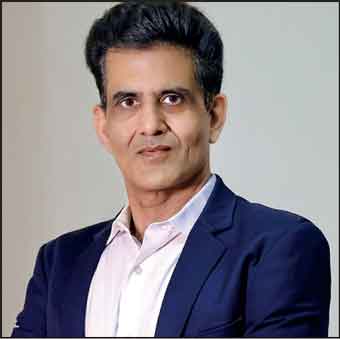 |
| Group CEO Ashish Chandra |
Hemas Holdings PLC yesterday said it delivered a strong second quarter, with revenue growing 17% year-on-year (YoY) to Rs. 37.8 billion as all four sectors recorded growth, led by hospitals (+19.3%) and consumer brands
(+18.3%).
EBITDA rebounded to Rs. 4.5 billion, up 10.5% YoY and nearly double the first quarter. Group earnings more than doubled from 1Q to Rs. 2 billion. For 1H FY27, the strong second quarter turned a 14.1% EBITDA decline at the end of 1Q into growth of 0.9%, with revenue growing 9.5% YoY to Rs. 67 billion.
During 1H, the Consumer Brands segments reported a revenue of Rs. 24.7 billion, up 13.4% from a year ago while earnings fell 30% to Rs. 1.6 billion. Life Sciences posted revenue of Rs, 34.5 billion, up 6% from a year ago with earnings falling 24% to Rs. 1.3 billion. Hospitals saw revenue grew 15% to Rs. 6.2 billion in 1H with earnings up 15% to Rs. 515 million. The Mobility segment saw revenue grow 10% YoY to Rs. 1.2 billion with earnings surging 58% to 627 million.
The Group chose to absorb much of the increase in raw material, energy and freight costs driven by the Middle East conflict, protecting consumer affordability and volumes. Gross margin declined 3.1pp YoY to 29.7%; however, disciplined cost management kept overheads growing slower than revenue, enabling EBITDA growth. Higher finance costs, reflecting increased borrowings to fund working capital and the Twiga acquisition, together with a higher tax charge, resulted in Group earnings declining 3% YoY, the company said.
Within Consumer Brands, Beauty, Home Care and Baby Care all delivered double-digit growth, with Beauty now accounting for 20% of the home and personal care portfolio. In Bangladesh, revenue recorded single-digit growth despite a challenging macroeconomic environment, with male grooming category growing by nearly 50%.
In Learning, newer adjacencies continued to gain traction, with Back-to-School and Bags volumes growing over 50% YoY. In Life Sciences, Hemas Pharmaceuticals retained its market leadership and secured six new product registrations during the quarter, while absorbing higher costs pending approval of regulated price revisions, and Morison’s own-brand volumes grew 23% YoY.
During the quarter, Hemas completed its first international acquisition, a 75% stake in Twiga Stationers and Printers Limited, a leading stationery manufacturer and exporter in East Africa. Revenue is tracking in line with projections, and Twiga provides a platform for long-term growth across the region.
Looking ahead, price revisions in pharmaceuticals, ongoing cost and productivity initiatives, and the third stage of the public sector salary revision in 2027 are expected to support margins and volumes. Hemas remains focused on its Long Range Plan targets of mid-teen compound annual growth in revenue and earnings, with 15% of revenue to be derived from international markets by FY30, and has earmarked over $ 100 million for new growth platforms, to be deployed with discipline.
Group CEO Ashish Chandra said: “2Q FY27 demonstrated the resilience of Hemas in a challenging environment. In a period shaped by the Middle East war, higher energy costs and a volatile currency, our teams protected consumers, ensured the continued availability of medicines and delivered a strong recovery in profitability from the first quarter. This resilience is the foundation on which we are building our next chapter.
“Our Long Range Plan sets clear north stars: mid-teen compound annual growth in both revenue and earnings, with 15% of revenue to be derived from international markets by FY30. To achieve this, we have earmarked over $ 100 million for new growth platforms. We will deploy this capital with discipline, prioritising opportunities that build on our strengths, offer scalable growth and meet clear return thresholds.
“Twiga represents our next step on the international journey. As it enters its school season, our priority is to deliver Twiga’s plan and develop it into a platform for growth across East Africa, reducing our dependence on a single economy and extending our learning expertise to many more young learners.
“In Sri Lanka, we expect the third stage of the public sector salary revision, amounting to Rs. 110 billion in 2027, to support affordability and volumes despite elevated inflation. Together with our relentless focus on cost and innovation, this gives us confidence in the momentum we carry into the second half. Above all, we will continue to Move with Courage. With a clear strategy, trusted brands and talented people, we are determined to convert this quarter’s recovery into sustained growth and lasting value for our shareholders, consumers and the communities we serve”.