Saturday Oct 03, 2026
Saturday Oct 03, 2026
Friday, 14 August 2026 05:49 - - {{hitsCtrl.values.hits}}
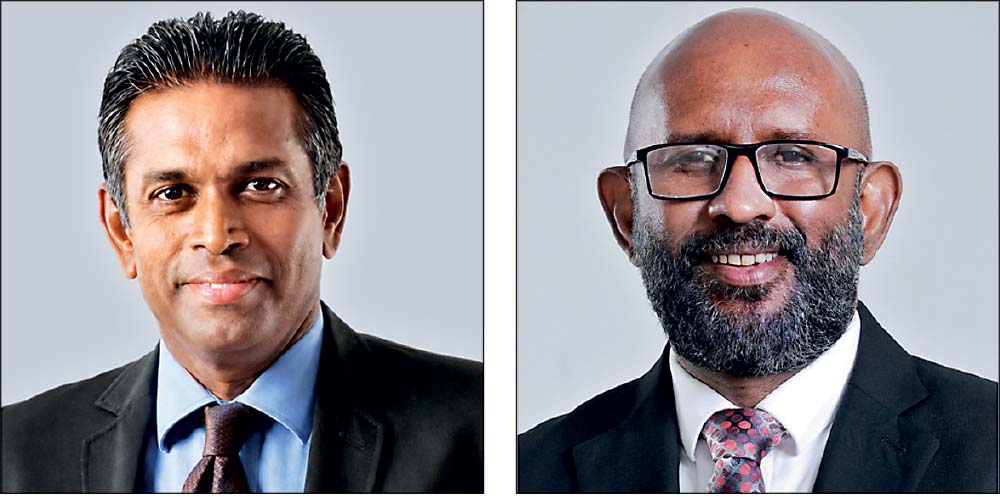
Chairman B.D.A. Perera (left) and Director/CEO Naleen Edirisinghe
Pan Asia Banking Corporation PLC yesterday said it posted a strong financial performance for the six months ended 30 June 2026, posting a Profit After Tax (PAT) of Rs. 2.5 billion. The bank’s results were driven by continued business momentum, reflected in a 13% growth in Net Interest Income and a 28% increase in Net Fee and Commission Income compared to the corresponding period in 2025.
Demonstrating a prudent and forward-looking risk management approach, Pan Asia Bank increased its impairment charge by 32% during the year under review. This strategic measure further strengthened the Bank’s provision buffer, ensuring greater resilience and preparedness to navigate potential market challenges and unforeseen economic disruptions.
Demonstrating its continued growth trajectory, the bank’s total asset base surpassed Rs. 350 billion for the first time in its history, marking a significant milestone. This achievement was underpinned by robust loan portfolio expansion, supported by sustained growth in customer deposits, reflecting the confidence and trust placed in the Bank by its customers and stakeholders.
The bank reported total interest income of Rs. 18.21 billion during the first half of 2026, representing a healthy year-on-year growth of 21%. This performance was underpinned by the continued expansion of loans and advances, supported by the bank’s strategic focus on strengthening its corporate and business banking segments from the latter part of the previous year, thereby positioning itself for sustainable credit growth.
Interest expense increased by 27% to Rs. 11.13 billion compared to the corresponding period of 2025, reflecting growth in deposits and borrowings, coupled with the upward adjustment in interest rates across the industry amidst evolving global economic conditions and geopolitical uncertainties.
As a result, Net Interest Income grew by 13% year-on-year to Rs. 7.07 billion. Meanwhile, Net Interest Margin (NIM) moderated marginally to 4.29% from 4.55% recorded in the corresponding period of 2025, primarily due to lower returns from the Government securities portfolio, reflecting the lagged effect of market yield movements on the repricing of the bank’s investment book.
Net fee and commission income recorded a robust growth of 28% to Rs. 1.46 billion, driven by healthy credit expansion, increased card usage, growth in trade-related business, and strong remittance inflows. The growth was broad-based, with trade finance, card-related services, and remittance products making significant contributions to the bank’s non-interest income stream.
Net gains from trading and gains from the derecognition of FVOCI financial assets declined by 31% and 74%, respectively, compared to the corresponding period of the previous year. This was mainly attributable to the upward movement in Treasury Bill and Treasury Bond yields during the period, which led to lower market valuations of fixed-income securities and consequently reduced mark-to-market and realization gains.
Despite these market-related headwinds, the bank demonstrated the resilience and diversity of its earnings profile, recording a total operating income of Rs. 8.68 billion, an increase of 9% over the corresponding period of 2025. The performance reflects the bank’s ability to sustain growth momentum through a balanced mix of fund-based and fee-based income streams while navigating a dynamic operating environment.
Stage-wise impairment movements continued to demonstrate disciplined portfolio management. Stage 1 impairment charges rose to Rs. 124.23 million, primarily driven by the expansion of the loan book and the incorporation of updated forward-looking macroeconomic risk indicators. Stage 2 impairment charges amounted to Rs. 278.13 million, reflecting moderate risk migration within certain segments of the portfolio.
In line with its conservative risk management framework, the bank also increased Stage 3 impairment provisions by Rs. 132.86 million as a prudential measure against selected borrower segments. This proactive provisioning underscores the bank’s commitment to maintaining a resilient balance sheet while safeguarding asset quality amid evolving economic conditions.
The bank maintained healthy asset quality indicators, with the Net Stage 3 Loan Ratio improving to 1.39% from 1.73% and the Gross Stage 3 Loan Ratio improving to 3.97% from 4.62% at end-2025. This reflects the effectiveness of the bank’s prudent credit risk management framework and disciplined underwriting practices.
The Stage 3 Provision Coverage Ratio improved to 64.92% from 62.63% at the end of 2025, underscoring the bank’s prudent provisioning approach and continued focus on strengthening balance sheet resilience. The increase reflects additional buffers maintained against sectors displaying early signs of stress, reinforcing the bank’s capacity to navigate evolving credit conditions.
The bank continued to balance strategic investments with disciplined cost management during the period. Operating expenses increased by 15% year-on-year, largely driven by investments in technology, digital transformation, and business infrastructure to support future growth and enhance customer experience. Consequently, the Cost-to-Income Ratio increased marginally to 50.32% from 48.94% in the corresponding period of 2025.
Taxes and levies on financial services increased by 6% during the period, reflecting the bank’s improved operating profitability and continued business growth. Despite the increase in operating profit, income tax expense declined compared to the corresponding period of the previous year, primarily due to the reversal of excess income tax provisions relating to prior years.
The bank recorded a 16% yearonyear increase in Profit After Tax in 1H 2026, reflecting strong underlying earnings momentum. The Net Interest Margin (NIM) was sustained at a healthy level, supported by effective balance sheet management and stable funding dynamics.
Key profitability indicators remained robust, with Return on Equity and Return on Assets Before Tax reflecting resilient core income generation, improved asset quality, and disciplined execution across the bank’s operations.
The positive earnings performance was further supported by strong growth in both fund-based and non-fund-based income streams, alongside continued cost discipline and operational efficiency improvements.
Fair value losses were recorded on Government securities classified under FVOCI, mainly rupee Treasury Bills and Treasury Bonds, due to increases in market interest rates during the period. These are mark-to-market adjustments arising from yield movements and do not impact the bank’s underlying earnings performance.
The bank achieved a significant milestone in June 2026, surpassing a total asset base of Rs. 350 billion for the first time in its 31-year history. Total assets grew by 15% year-on-year, reflecting sustained business momentum and the successful execution of the bank’s growth strategy.
Gross Loans and advances increased by 14% to Rs. 248.12 billion, driven by strong credit demand across the SME, Corporate, and Retail segments. The growth was supported by targeted sector-focused strategies and a disciplined approach to business origination, enabling the bank to further strengthen its market presence while maintaining prudent lending standards.
Customer deposits also recorded robust growth, rising by 17% year-on-year to Rs. 271.24 billion as at 30 June 2026. This strong performance reflects the continued trust and confidence placed in the Bank by its customers over more than three decades. Deposit growth was broad-based, supported by healthy mobilisation of both term deposits and low-cost CASA balances, further enhancing the bank’s funding profile.
The bank maintained a strong capital and liquidity position during the period, with all regulatory ratios remaining comfortably above minimum requirements. Capital adequacy remained robust, with a Common Equity Tier 1 (CET1) Ratio and Tier 1 Ratio of 14.93%, and a Total Capital Ratio of 16.47%, providing a solid buffer to support growth while maintaining prudent risk coverage.
Liquidity indicators continued to demonstrate resilience, reflecting effective balance sheet management and a stable funding profile. The Liquidity Coverage Ratio (LCR) stood well above regulatory thresholds, with the Rupee LCR at 221.63% and the All Currency LCR at 168.79%, while the Net Stable Funding Ratio (NSFR) remained strong at 128.96%.
The bank’s Leverage Ratio of 7.98% further underscores its balance sheet strength, reinforcing overall financial resilience and providing capacity to sustain future expansion in a disciplined manner.
Chairman B. D. A. Perera said: “Pan Asia Bank has recorded a solid performance during the first six months of 2026, reflecting the strength of its business fundamentals, disciplined execution of strategy, and the continued trust of customers and stakeholders. The bank achieved meaningful growth in earnings while further expanding its lending and deposit franchises, reinforcing its competitive position within the banking industry.”
During the period under review, total assets exceeded Rs. 354 billion, supported by strong growth in both advances and customer deposits. These results were achieved while maintaining healthy capital and liquidity levels and upholding prudent risk management standards. Such performance underscores the bank’s ability to grow sustainably while preserving financial resilience.”
He added: “The Board remains committed to driving long-term value creation through sound governance, operational excellence, and customer-focused banking solutions. We will continue to support individuals, businesses, and communities while strengthening the bank’s capability to respond to evolving market opportunities.”
“As we move into the remainder of the year, we are encouraged by the opportunities ahead. Backed by a strong balance sheet, a loyal customer base, and an experienced management team, Pan Asia Bank is well positioned to deliver sustainable growth and attractive returns to shareholders.”
Director/CEO Naleen Edirisinghe said: “Pan Asia Bank delivered a strong financial result for the six months ended 30 June 2026. Profit Before Tax reached Rs. 2.93 billion, while Profit After Tax grew to Rs. 2.50 billion. This achievement was driven by growth across our core banking businesses, supported by healthy net interest earnings and fee-based income.”
“Our lending portfolio continued to expand across the corporate, SME, and retail banking segments, reflecting increased customer demand and our ability to meet diverse financing requirements. Customer deposits also recorded strong growth, further strengthening the Bank’s funding base and demonstrating the confidence customers place in Pan Asia Bank.”
He added: “The Bank’s profitability benefited from increased business volumes, treasury income contributions, and ongoing cost discipline. At the same time, we maintained a strong focus on risk management and credit quality, ensuring that growth remained balanced and sustainable.”
“We continued to invest in digital transformation initiatives, process improvements, analytics capabilities, and customer experience enhancement programmes. These investments are helping us improve efficiency, strengthen customer relationships, and respond effectively to changing customer expectations in an increasingly technology-driven environment.”
“Looking ahead, our priorities remain focused on quality asset growth, profitability enhancement, productivity improvement, and revenue diversification. Supported by a strong capital position and disciplined execution of our strategic agenda, we are confident in our ability to sustain growth and create long-term value for all stakeholders.”