Friday Nov 20, 2026
Friday Nov 20, 2026
Friday, 20 November 2026 00:22 - - {{hitsCtrl.values.hits}}
National Savings Bank Group (NSB) yesterday said it has sustained its core banking momentum during the first nine months of 2026, supported by stronger net interest income, strong growth in fee-based earnings and continued expansion in loans and advances.
The Group’s net interest income rose 7.4% to Rs. 69.1 billion, total operating income increased 3.6% to Rs. 71.2 billion and net operating income grew 5.4% to Rs. 75.3 billion. Group profit before tax amounted to Rs. 34.7 billion, broadly in line with Rs. 34.8 billion in the corresponding period of 2025, while profit after tax stood at Rs. 20.7 billion. Group total assets increased to Rs. 1.92 trillion and Group equity rose 8.7% to Rs. 139.05 billion.
The Bank reported total operating income of Rs. 69.8 billion for the period, an increase of 4.6% compared with Rs. 66.7 billion in the corresponding period of 2025. Net operating income increased by 6.4% to Rs. 73.9 billion from Rs. 69.4 billion a year ago, supported by a net impairment reversal of Rs. 4.1 billion arising from improved recoveries and asset quality.
Net interest income rose by 6.4% year-on-year to Rs. 67.3 billion, compared with Rs. 63.2 billion in the first nine months of 2025. Interest income increased 1.8% to Rs. 150.8 billion, while interest expenses declined 1.6% to Rs. 83.5 billion. The result reflects strict financial discipline, prudent balance-sheet management and the Bank’s continued focus on maintaining a sustainable funding and asset mix.
The Bank also achieved substantial growth in fee-based earnings. Fee and commission income rose 32.1% to Rs. 2.58 billion, and net fee and commission income increased by 34.2% to Rs. 2.21 billion, from Rs. 1.65 billion a year earlier. Net other operating income increased 53.2% to Rs. 924 million. These gains were partly offset by a net trading loss of Rs. 744 million, compared with a trading gain of Rs. 775 million in the previous year.
Profit before tax amounted to Rs. 33.7 billion, an increase of 1.1% from Rs. 33.3 billion in the first nine months of 2025, while profit after tax stood at Rs. 20 billion, compared with Rs. 20.11 billion.
Despite these pressures, the Bank preserved a substantial earnings base and continued to invest in the people, systems and service capabilities required to improve operational resilience and the customer experience. Income tax for the period amounted to Rs. 13.7 billion, while VAT and the Social Security Contribution Levy on financial services together amounted to Rs. 10.9 billion. In addition, the Bank declared a dividend of Rs. 7.4 billion to the Government as its sole shareholder. Accordingly, NSB’s total contribution to the Government through dividends, taxes and levies amounted to Rs. 32 billion for the nine months, underscoring the Bank’s significant contribution to public finances and national development.
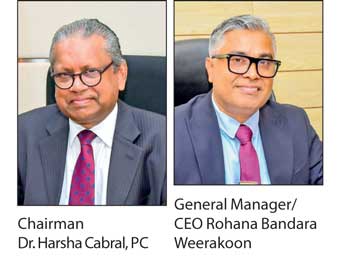
Chairman Dr. Harsha Cabral, PC said: “Our nine-month results reflect the resilience of NSB’s core business and the trust placed in the Bank by generations of Sri Lankans. While expanding lending and improving asset quality, we remain focused on the prudent stewardship of public savings and on supporting productive economic activity, financial inclusion and national development.”
NSB’s total assets increased by 2.6% during the first nine months of the year to Rs. 1.88 trillion, from Rs. 1.83 trillion at end-December 2025. Loans and advances recorded a strong 11.3% expansion to Rs. 613.1 billion from Rs. 550.8 billion, demonstrating the Bank’s continued support for the financing needs of individuals, households and eligible institutional customers within its mandate.
Deposits, the principal source of funding for NSB, increased by 1.9% to Rs. 1.64 trillion from Rs. 1.61 trillion. The Bank’s financial position remained sound, with total shareholders’ equity increasing by 9.0% to Rs. 129.7 billion from Rs. 119.1 billion. Retained earnings rose by 14.7% to Rs. 53.41 billion, further strengthening the Bank’s capacity to support future growth and absorb potential shocks.
General Manager/CEO Rohana Bandara Weerakoon said: “The growth we have achieved in lending, savings, foreign currency deposits and fee income shows the progress we are making in diversifying our business. We will continue to strengthen digital access, service quality, cost discipline and risk management while delivering on NSB’s national mandate.”
The Bank’s profitability indicators continued to reflect the strength of its core banking activities, although higher operating expenses moderated overall returns. The Net Interest Margin (NIM) improved to 4.85% from 4.74% at the end of 2025. Return on Assets (ROA) remained broadly stable at 2.43%, compared with 2.48%, while Return on Equity (ROE) stood at 21.49%, compared with 25.08% at the end of 2025.
Asset quality continued to improve. The net Stage 3 loans ratio improved to 2.00% from 2.52%. At the same time, the Stage 3 impairment coverage ratio strengthened to 59.42% from 58.54%, reflecting improved coverage against Stage 3 loans.
NSB maintained capital buffers comfortably above the applicable regulatory minimum requirements. The Tier 1 capital ratio stood at 18.23% against a minimum of 8.5%, and the total capital ratio at 19.43%, well above the minimum requirement of 12.5%.
The Bank also maintained a strong liquidity and stable funding position. The all-currency liquidity coverage ratio stood at 307.17%, substantially above the statutory minimum of 100%, reflecting the availability of sufficient high-quality liquid assets to meet short-term liquidity requirements. The net stable funding ratio stood at 195.60%, also comfortably above the regulatory minimum of 100%, demonstrating the stability of the Bank’s longer-term funding profile.