Saturday Sep 26, 2026
Saturday Sep 26, 2026
Thursday, 24 September 2026 00:03 - - {{hitsCtrl.values.hits}}
By Wealth Trust Securities
At the weekly Treasury Bill auction conducted yesterday, the weighted average yields increased across the board for the second consecutive week.
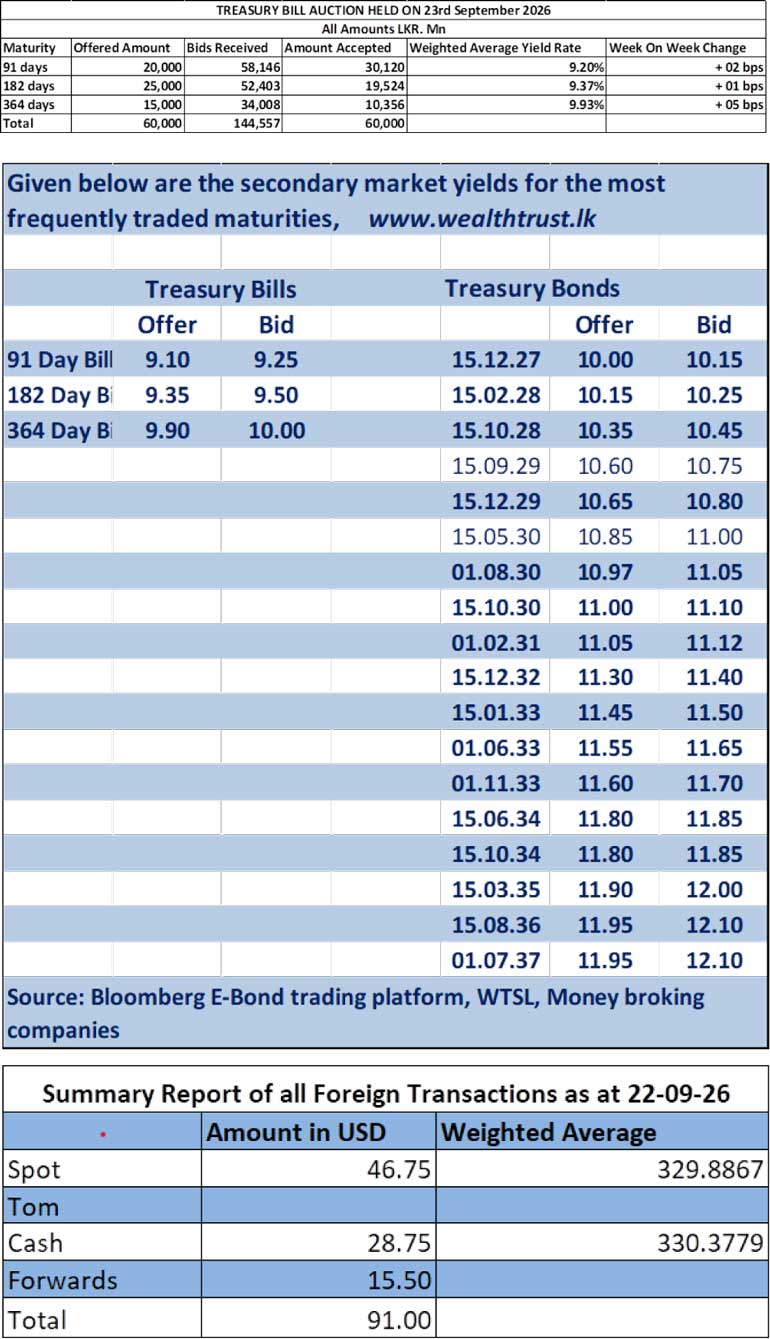
Accordingly, the 91-day yield rose by 2 basis points to 9.20%, while the 182-day and 364-day yields increased by 1 basis point and 5 basis points to 9.37% and 9.93%, respectively.
The Public Debt Management Office (PDMO) successfully raised the full Rs. 60 billion offered. The 91-day tenor recorded acceptances above its target allocation, while the 182-day and 364-day tenors fell short of their respective targets.
Total bids received amounted to 2.41 times the overall offer.
The Phase II subscription across on the 182- and 364-day maturities is now open until 3.00 p.m. on 24.09.2026 at the Weighted Average Yield Rates (WAYRs) determined at the auction (see table for auction details).
The secondary Bond market extended its rally yesterday, with yields continuing to trend lower amid sustained positive sentiment. The sovereign rating upgrade to ‘B-’ with a Stable Outlook, remained a key catalyst, while the IMF’s latest assessment further reinforced confidence, highlighting economic resilience, strong fiscal performance and improving foreign reserves. The IMF report also recommended maintaining the inflation target at the current 5.00%, while discussions remain ongoing towards reaching a Staff Level Agreement for the latest review.
Sentiment was further supported by Brent crude remaining below $ 100 per barrel amid renewed diplomatic efforts and expectations of improved Middle Eastern oil flows, easing concerns over inflationary and external sector pressures.
Although some profit-taking and the Treasury bill auction outcome prompted a modest late-session retracement, secondary market two-way quotes ultimately closed lower on the day, preserving the broader bullish momentum.
The 15.02.28 and 15.12.28 traded lower at 10.20% and 10.50% respectively. The 01.08.30, 15.10.30 and 01.02.31 maturities traded within the ranges of 11.05%-10.95%, 11.10%-10.95% and 11.15%-11.00% respectively. The 15.12.32 traded within the range of 11.43%-11.35%. The 01.06.33 and 01.11.33 traded within the ranges of 11.65%-11.55% and 11.70%-11.60% respectively. The 15.06.34 and 15.10.34 maturities traded lower at 11.82%-11.75% and 11.90%-11.75% respectively. The 15.06.35 maturity traded at 12.00%.
In the money market, the net liquidity surplus stood at Rs. 148.87 billion. A total of Rs. 90.10 billion was deposited at the Central Bank’s SDFR (Standing Deposit Facility Rate) of 8.25% as against an amount of Rs. 1.73 billion withdrawn from the Central Bank’s SLFR (Standing Lending Facility Rate) of 9.25%.
In addition, the Domestic Operations Department (DOD) of the Central Bank of Sri Lanka mopped out Rs. 22.50 billion by way of an overnight repo auction at a weighted average yield of 8.74% and Rs. 38 billion through a 7-day term repo auction at the weighted average yield of 8.75%.
The weighted average yields on overnight call money and repos were 8.92% and 8.98% respectively.
Forex market
The USD/LKR rate on spot contracts was seen closing at Rs. 329.50/329.80 yesterday, as against Rs. 329.40/329.60 recorded on the previous day. The total USD/LKR traded volume for 22 September amounted to $ 91 million.
(References: Public Debt Management Office - Ministry of Finance, Central Bank of Sri Lanka, Bloomberg E-Bond Trading Platform, Money Broking Companies)