Monday Sep 14, 2026
Monday Sep 14, 2026
Thursday, 6 August 2026 07:55 - - {{hitsCtrl.values.hits}}
By Wealth Trust Securities
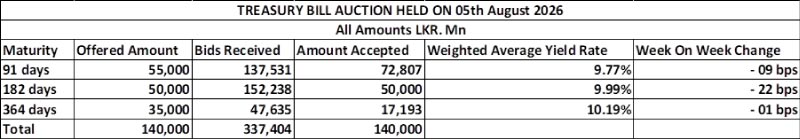
 At the weekly Treasury Bill auction held yesterday, the weighted average yields dropped for the fourth consecutive week. Accordingly, the yield on the 91-day tenor declined by 9 basis points to 9.77% and the 182-day maturity by a steep 22 basis points to 9.99% and the 364-day maturity notched lower by 1 basis point to 10.19%.
The auction successfully raised the full Rs. 140 billion offered at the first phase of competitive bidding. Maturity-wise, the shorter tenors raised more than or equal to their respective amounts offered, while the one-year tenor raised less than the amount offered. The bids received exceeded the offered amount by 2.41 times.
The Phase II subscription only on the 182-day and 364-day tenor maturities is now open until 3.00 pm on (06.08.2026) at the WAYRs determined for the said ISINs at the auction. Given below are the details of the auction.
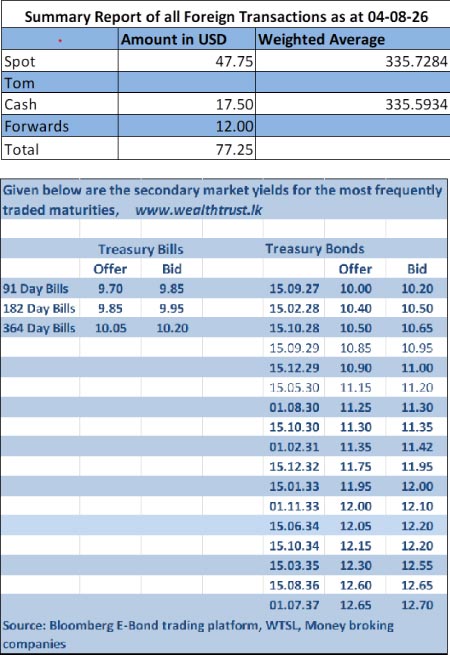
The secondary Bond market rallied yesterday as optimism over a potential agreement to reopen the Strait of Hormuz without tolls lifted sentiment. Axios reported that the US, Iran, and Oman are nearing a 60-day interim deal, with an announcement potentially coming as early as Wednesday (US time), driving oil prices further lower in addition to expectations of a dip in T-Bill averages. The market became increasing bullish and aggressive buying interest pushed rates down. Activity and transaction volumes were seen at robust levels as the market resumed its recent rally.
The 15.10.29 and 15.12.29 maturities traded at the rates of 10.95% and 11.00% respectively. The 2030 tenors saw strong demand and accordingly the 01.03.30, 15.05.30, 01.08.30 and 15.10.30 maturities traded lower down the ranges of 11.20%-11.10%, 11.25%-11.18%, 11.40%-11.30% and 11.42%-11.32% respectively. The 01.02.31 also rallied strongly and saw its yield decline by 15 basis points intraday, from a high of 11.55% to a low of 11.40%. The 15.10.34 maturity traded down the range of 12.25-12.15 and the 15.12.32 maturity at the rate of 11.85%. On the longer end the 15.08.36 maturity traded at the rates of 12.65%-12.60% and the 01.07.37 at the rates of 12.75%-12.70%.
In the money market, the net liquidity surplus was recorded at Rs. 185.38 billion. An amount of Rs. 132.38 billion was deposited at the Central Bank’s SDFR (Standing Deposit Facility Rate) of 8.25%.
In addition, the Domestic Operations Department (DOD) of the Central Bank of Sri Lanka mopped out Rs. 23 billion by way of an overnight Repo auction at a weighted average rate of 8.75% as well as Rs. 30 billion by way of a seven-day term Repo auction at the weighted average rate of 8.75%.
The weighted average rates on overnight call money and repos were recorded at 9% and 9.03% respectively.
Forex market
The USD/LKR rate on spot contracts was seen closing at the rate of Rs. 335.55/335.60 yesterday, appreciating further from Rs. 335.72/335.77 recorded the day prior.
The total USD/LKR traded volume for 04th August amounted $ 77.25 million.
(References: Public Debt Management Office - Ministry of Finance, Central Bank of Sri Lanka, Bloomberg E-Bond Trading Platform, Money Broking Companies)