Thursday Nov 05, 2026
Thursday Nov 05, 2026
Monday, 26 October 2026 06:23 - - {{hitsCtrl.values.hits}}
By Wealth Trust Securities
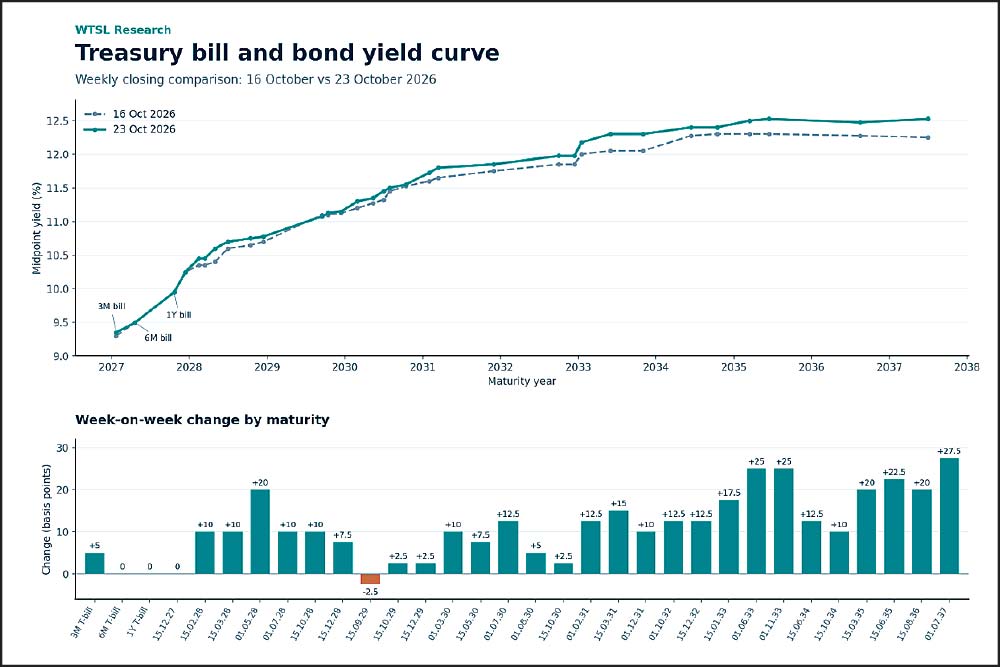
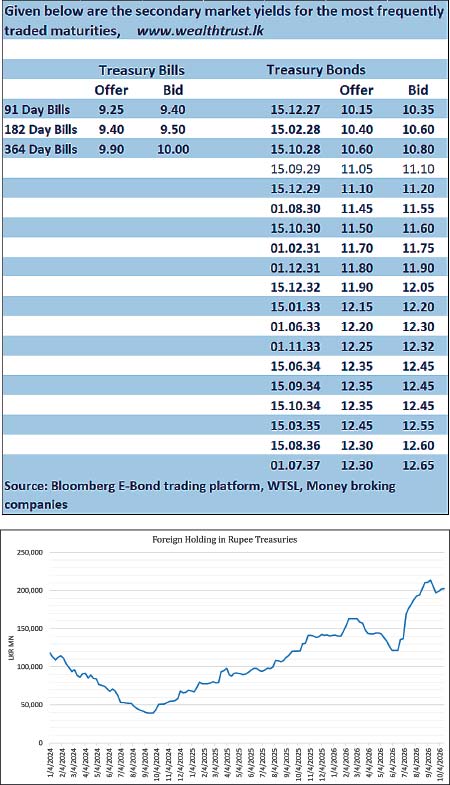 The secondary Bond market initially commenced the trading week ending 23 October on a distinctly bearish footing, with aggressive selling interest driving yields sharply higher and extending the upward momentum from the previous week. However, the elevated yield levels attracted strong buying interest, which absorbed the selling pressure and provided firm support to the market. Traded volumes increased significantly as demand emerged at the higher levels.
This paved the way for a recovery through the middle of the week, with yields reversing their initial increases and declining across medium to longer tenors amid sustained buying interest. Activity and traded volumes remained healthy, reflecting improved demand at the recently elevated levels.
Buying interest subsequently centred on the shorter 2028–2031 maturities, driving yields lower at the short end, while the remainder of the curve held broadly steady. Activity moderated towards the close of the week.
Despite this recovery, two-way quotes closed slightly higher on the belly end of the curve after recovering from their intraweek highs while the short end remained steady, week on week.
At the very short end of the curve, the 15.12.26 touched an intraweek high of 9.50% before trading down to a low of 9.42%, while the 15.01.27 traded at 9.50%. The 15.09.29 and 15.12.29 traded at 11.10% and 11.15% respectively.
The 15.05.30 traded at 11.40%, while the 01.07.30 traded down from an intraweek high of 11.65% to a low of 11.50%. The 01.08.30 saw its yield ease off from 11.60%-11.50% while the 15.10.30 traded down the range of 11.65% to 11.55%. The 15.01.33 traded up to a high of 12.30% before easing to 12.17%, subsequent to hitting a weekly low of 12.10%.
The 2031 and 2034 tenors exhibited the see-saw movement more profoundly, with the 01.02.31 and 01.12.31 increasing to weekly highs of 11.80% and 11.95% respectively from 11.65% and 11.80% opening lows before easing to 11.75% and 11.85% at the end of the week. All three 2034 tenors (15.06.34, 15.09.34 & 15.10.34) followed suit, increasing from an opening average low of 12.33% to highs of 12.55% and easing to close the week on 2-way quotes of 12.35%/12.45% across all the maturities. The 15.03.35 traded at 12.55%.
At the weekly Treasury Bill auction conducted last Wednesday (21), weighted average yields were seen holding broadly steady for a second consecutive week with the rate on the 182-day and 364-day tenors remaining unchanged at 9.44% and 9.95% respectively for the second straight week. However, the 91-day tenor maturity saw its yield edge up marginally by 02 basis points to 9.32%.
The Public Debt Management Office (PDMO) raised only Rs. 80.611 billion or 80.61% in total out of the Rs. 100 billion offered in total. The 91-day tenor recorded acceptance above its respective target allocation, while the 182-day and 364-day recorded acceptances below their respective offered amounts.
Total bids received amounted to 1.86 times the overall offer.
Meanwhile, the foreign holdings of rupee-denominated Government securities recorded a net outflow for the first time in four weeks, registering a decrease amounting 1.40% or Rs. 2.82 billion for the week ended 22 October. Accordingly, the total foreign holdings of rupee treasuries decreased to Rs. 199.54 billion.
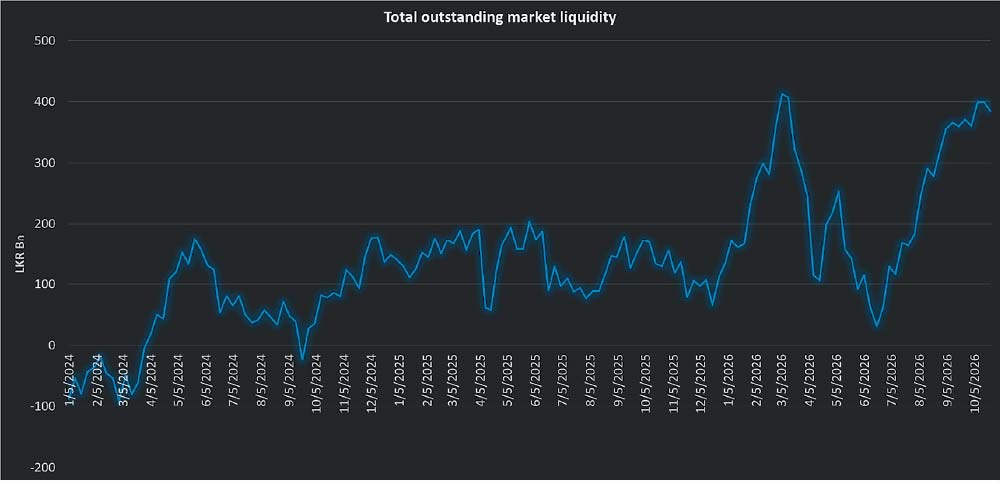
The Surplus liquidity in money markets was seen remaining elevated for the week ending 23 October 2026, at Rs. 384.90 billion albeit declining slightly as compared to its previous week’s closing level of Rs. 399.88 billion.
The weighted average rates on Call Money and Repo closed last week at 9.00% and 9.06% as against 8.99% and 9.04% respectively the previous week.
Furthermore, the rupee or the USD/LKR rate was seen depreciating, to close the week ending 23 October at Rs. 332.10/332.20 as against its previous week’s closing of Rs. 331.25/331.35. This was subsequent to trading within an intraweek high of Rs. 331.35 and a low of Rs. 332.26 intraweek.
The average daily USD/LKR traded volume over the first four trading days of the week stood at $ 51.67 million.
(References: Public Debt Management Office - Ministry of Finance, Central Bank of Sri Lanka, Bloomberg E-Bond Trading Platform, Money Broking Companies)