Tuesday Oct 20, 2026
Tuesday Oct 20, 2026
Monday, 19 October 2026 04:36 - - {{hitsCtrl.values.hits}}

By Wealth Trust Securities
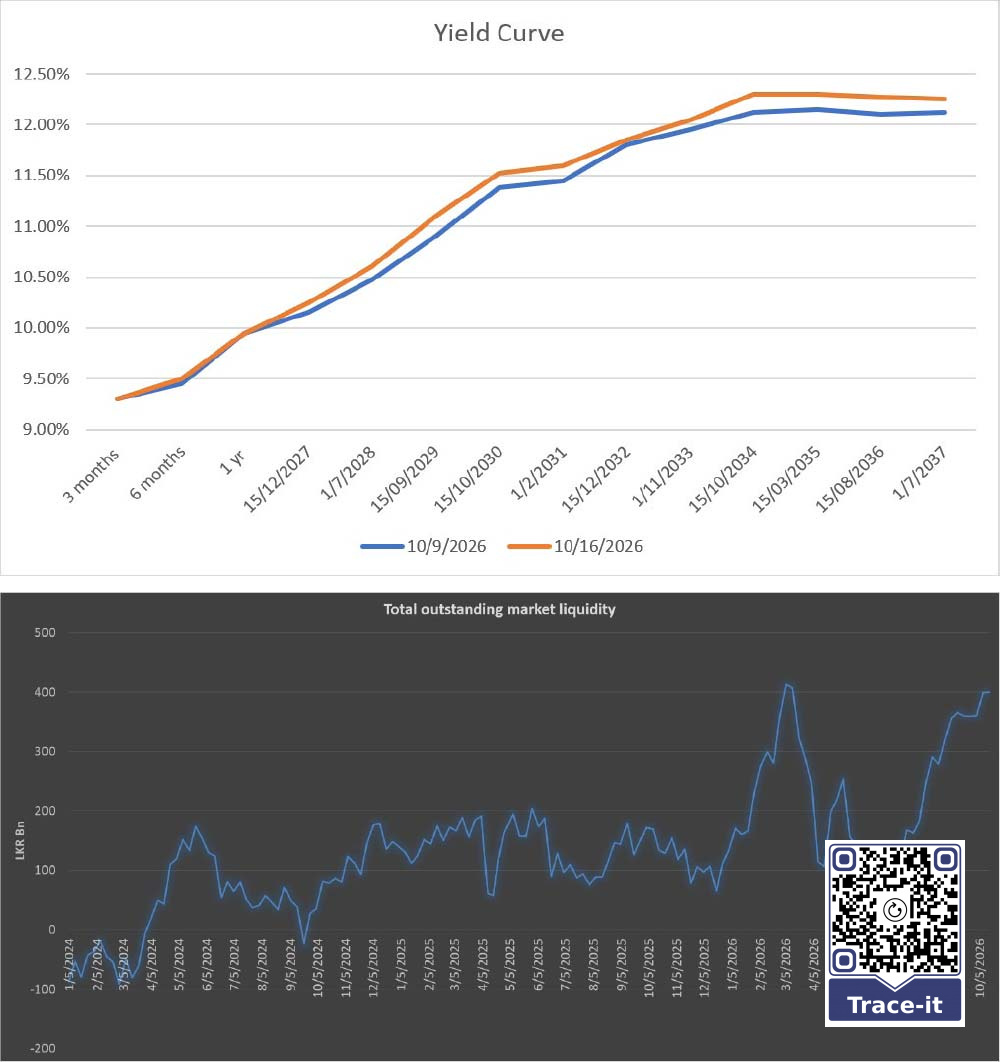
 The secondary Bond market remained largely range-bound during the early part of the trading week ending 16 October, with yields holding broadly steady as participants adopted a cautious stance leading to the Treasury Bond auctions. Trading activity was initially subdued, while the auction outcomes prompted little movement across most of the yield curve.
Thereafter, selective selling interest emerged across the shorter 2029 maturities and the medium 2034 maturities, resulting in a gradual upward drift in yields across the curve. However, buying interest was evident at the elevated levels, helping to absorb the available selling interest and keeping the adjustment contained.
Accordingly, secondary market yields closed higher on a week-on-week basis. Activity and transaction volumes improved from the subdued levels seen at the start of the week and remained at moderate levels towards the close.
The 15.12.27 traded at 10.2%, while the 15.12.2028 moved up within an intraweek range of 10.62%–10.7%. The 15.09.2029 traded up within a range of 11%–11.1% during the week.
The 15.10.2030 saw yields edge higher during the week, trading up from an intraweek low of 11.38% to a high of 11.5%. The 01.02.2031 traded up from 11.48% to 11.6%, while the 01.12.2031 traded up from 11.65% to 11.75%.
Further along the curve, the 01.11.2033 traded up from 11.95% to 12.05%. On the 2034 tenor, the 15.09.34 saw relatively contained but concentrated selling pressure, which pushed it higher within a range of 12.26%–12.3%, while the 15.10.2034 rose from an intraweek low of 12.15% to a high of 12.25%. The 15.06.35 traded at 12.28%.
To recap: the Treasury Bond auctions conducted last Tuesday (13) raised Rs. 80.69 billion, or 80.69% of the total Rs. 100 billion offered across both phases. The auction recorded a mixed outcome, with weighted average yields settling broadly in line with or marginally above prevailing secondary market levels. The bids received-to-offered ratio stood at 2.89 times.
Maturity-wise, the results were as follows:
The longer-tenor 15.08.2036 maturity was issued at a weighted average yield of 12.33% but failed to raise the full offered amount across both phases.
Following the auction, a further Rs. 5 billion, the maximum amount offered was raised through the Direct Issuance Window at the weighted average yields determined at the auction. The issuance was confined to the 2029 and 2031 tenors and attracted total subscriptions of Rs. 10.72 billion. This brought the total value of Treasury Bonds issued during the week to Rs. 85.69 billion.
At the weekly Treasury Bill auction conducted last Wednesday (14), weighted average yields were seen holding broadly steady, with the rate on the 182-day and 364-day tenors remaining unchanged at 9.44% and 9.95%, respectively. However, the 91-day tenor maturity saw its yield increase by four basis points to 9.3%.
The Public Debt Management Office (PDMO) raised only Rs. 66.13 billion or 73.47% in total out of the Rs. 80 billion offered in total. The 91-day tenor recorded acceptance above its respective target allocation, while the 182-day and 364-day recorded acceptances below their respective offered amounts.
Total bids received amounted to 2.01 times the overall offer.
Following the auction, a further Rs. 7.21 billion was raised through the Treasury Bill phase 2 issuance at the weighted average yields determined at the auction, bringing the total value of Treasury Bills issued during the week to Rs. 73.33 billion.
Meanwhile, foreign holdings of rupee-denominated Government securities recorded a net inflow for the third consecutive week, albeit a marginal increase amounting to Rs. 364 million for the week ended 15 October. Accordingly, total foreign holdings of rupee treasuries increased to Rs. 202.36 billion.
The surplus liquidity in money markets was seen holding around the Rs. 400 billion mark for the week ending 16 October at Rs. 399.88 billion.
The weighted average rates on call money and repo stood at 8.99% and 9.04%, respectively, unchanged against the previous week’s levels.
Furthermore, the rupee or the USD/LKR rate was seen depreciating to close the week ending 16 October at Rs 331.25/331.35, as against its previous week’s closing of Rs. 330.85/330.95. This was subsequent to trading within an intraweek high of Rs. 330.95 and an intraweek low of Rs. 331.36.
The average daily USD/LKR traded volume over the first four trading days of the week stood at $ 45.99 million.
(References: Public Debt Management Office - Ministry of Finance, Central Bank of Sri Lanka, Bloomberg E-Bond Trading Platform, Money Broking Companies)