Monday Nov 09, 2026
Monday Nov 09, 2026
Monday, 9 November 2026 04:52 - - {{hitsCtrl.values.hits}}
By Wealth Trust Securities
 The secondary Bond market recorded a strong rally last week, with yields declining sharply across the curve as sustained buying interest gathered momentum. The move was particularly pronounced across the medium- to longer-tenor maturities, with the pace of the decline accelerating as the week progressed.
Sentiment was supported by the sharp intraweek fall in global oil prices, as renewed diplomatic efforts between the US and Iran eased concerns over further supply disruptions and tempered near-term inflationary pressures. The outcome of the US midterm elections further reinforced the move, with Democrats securing control of both chambers of Congress. This contributed to an easing in US Treasury yields, while the broader decline in regional Bond yields, including Indian Government securities, provided additional support.
Against this backdrop, buying interest intensified and yields fell steeply across key maturities over four consecutive sessions. The scale and speed of the move reflected a marked improvement in risk sentiment and a rapid repricing of both external and inflation-related concerns.
Towards the close of the week, some profit-taking emerged alongside a modest rebound in oil prices, prompting a brief and relatively limited reversal in yields. However, the move proved short-lived, with renewed buying interest subsequently pushing rates lower again. As a result, secondary market two-way quotes closed sharply lower week-on-week across much of the yield curve. Market activity and transaction volumes remained robust throughout the week, supported by sustained demand and several sizeable transactions.
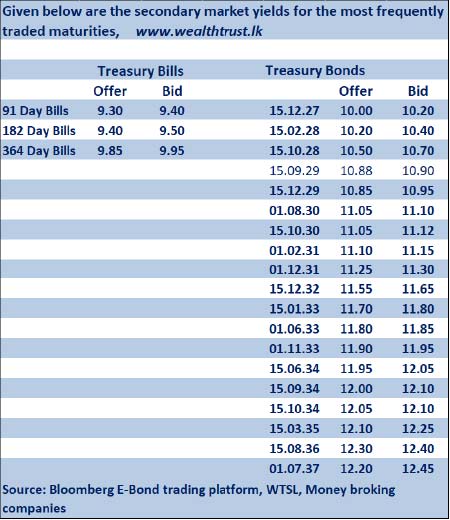
At the very short end of the curve, the 15.12.26 traded at 9.40%-9.36%, while the 15.01.27 traded within the range of 9.45%-9.40%. The 15.09.29 and 15.12.29 rallied down the ranges of 10.95%-10.80% and 11.25%-10.90% respectively.
The 2030 tenors saw a pronounced rally through the week. The 01.03.30 traded down from an intraweek high of 11.47% to a low of 11.00%, while the 15.05.30 declined from 11.45% to an intraweek low of 10.95%. The 01.08.30 rallied down from an intraweek high of 11.55% to a low of 10.95%, while the 15.10.30 saw a similarly sharp move, declining from an intraweek high of 11.62% to a low of 11.00%.
The rally extended into the 2031 segment. The 01.02.31 traded down sharply from an intraweek high of 11.75% to a low of 11.00%. The 01.12.31 initially rose to an intraweek high of 11.95% before reversing sharply and rallying down to a low of 11.25%.
Further along the curve, the 15.12.32 traded down from an intraweek high of 12.03% to a low of 11.55%. The 15.01.33 traded lower at 11.80%, while the 01.06.33 and 01.11.33 declined to trade lower at 11.85% and 11.90% respectively from a high of 12.35% each.
The 15.10.34 rallied sharply from an intraweek high of 12.63% to a low of 12.00%. The 15.03.35 traded down the range of 12.58%-12.15%. On the longer end, the 15.08.36 also posted a steep decline, with yields dropping from an intraweek high of 12.90% to a low of 12.25%.
To recap: At the weekly Treasury Bill auction conducted last Wednesday (4), weighted average yields were seen holding steady with the rate on the 182-day and 364-day tenors remaining unchanged at 9.44% and 9.95% respectively for the fifth straight week. However, the 91-day tenor maturity saw its yield edge up by 01 basis points to 9.35%.
The Public Debt Management Office (PDMO) raised only Rs. 65.9 billion or 73.22% in total out of the Rs. 90 billion offered in total. The 91-day tenor recorded acceptance above its respective target allocation, while the 182-day and 364-day recorded acceptances below their respective offered amounts.
Total bids received amounted to 1.73 times the overall offer.
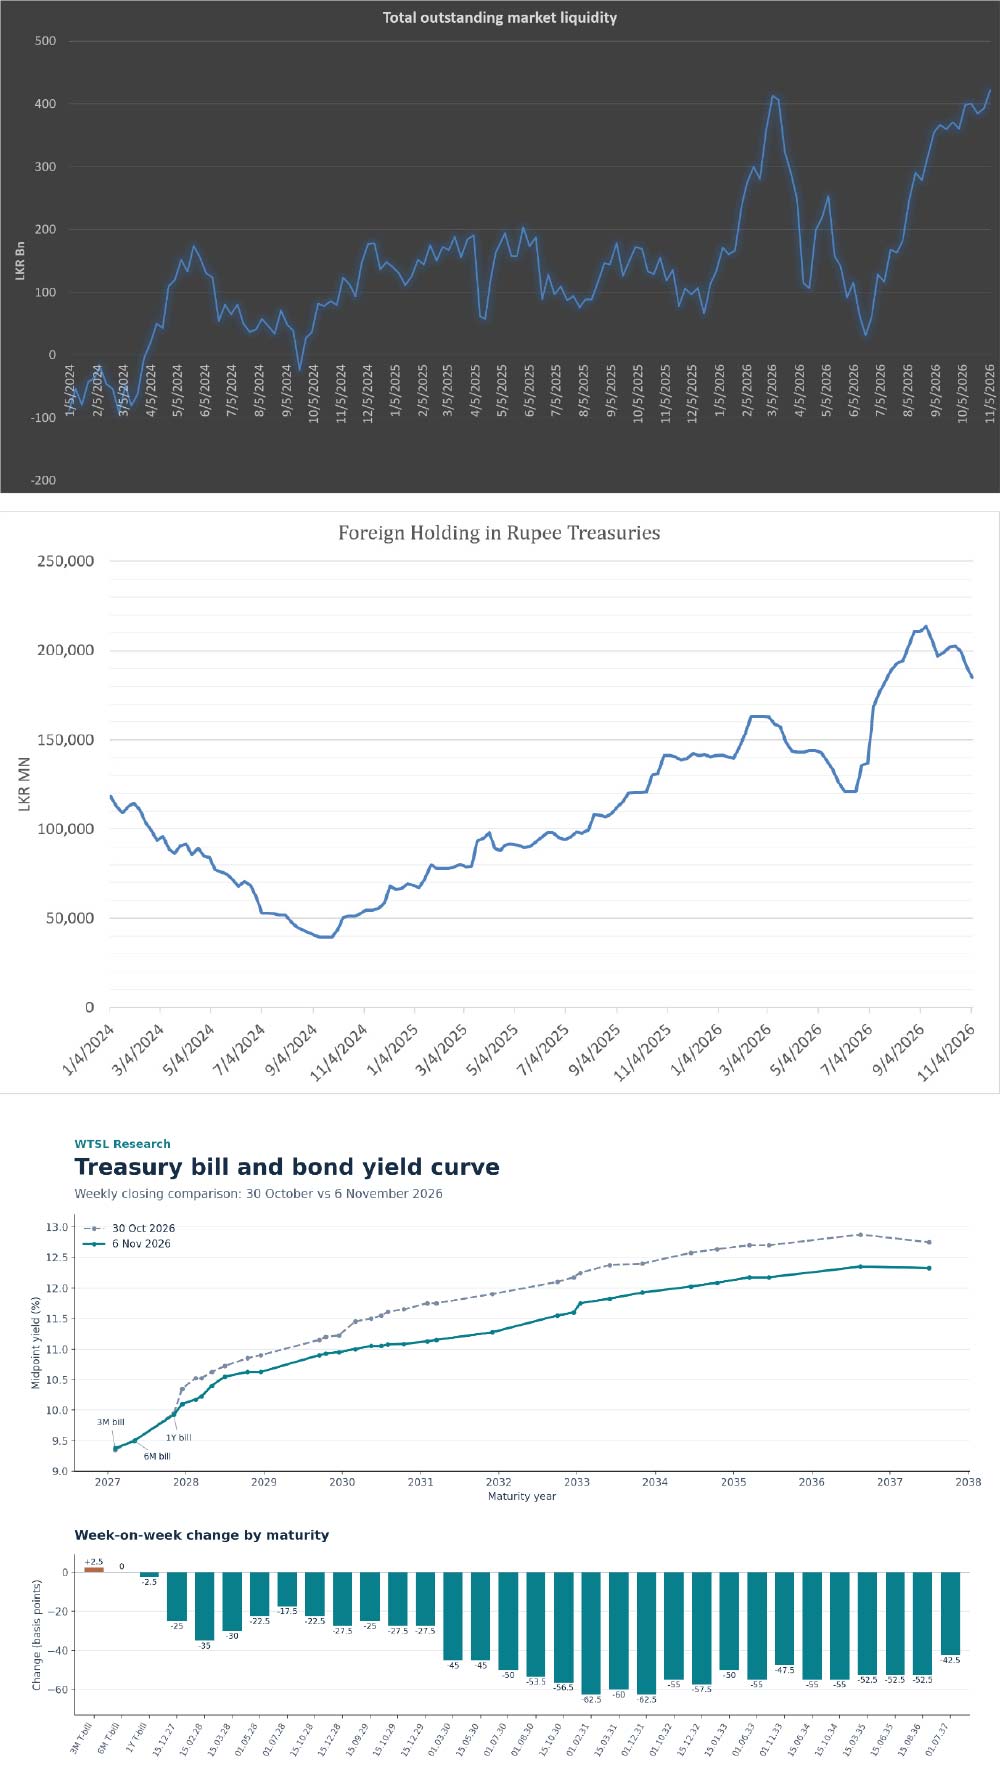
Meanwhile, the foreign holdings of rupee-denominated Government securities recorded a net outflow for the third straight week, registering a decrease amounting to 3.20% or Rs. 6.08 billion for the week ended 5 November. Accordingly, the total foreign holdings of rupee treasuries decreased to Rs. 184.86 billion.
The surplus liquidity in money markets was seen remaining elevated for the week ending 6 November 2026, rising to Rs. 422.29 billion as against its previous week’s closing level of Rs. 392.68 billion. Accordingly, the total market liquidity surplus rose to the highest level since March this year.
The weighted average rates on Call Money and Repo were at 9.04% and 9.13% respectively at the end of the week.
Forex market
The rupee or the USD/LKR rate was seen closing the week broadly steady, at Rs. 332.50/332.60 as against its previous week’s closing of Rs. 332.55/332.65. This was subsequent to trading within an intraweek high of Rs. 332.30 and a low of Rs. 332.80. The average daily USD/LKR traded volume over the first four trading days of the week stood at $ 72.28 million.
(References: Public Debt Management Office - Ministry of Finance, Central Bank of Sri Lanka, Bloomberg E-Bond Trading Platform, Money Broking Companies)