Friday Oct 23, 2026
Friday Oct 23, 2026
Thursday, 22 October 2026 00:02 - - {{hitsCtrl.values.hits}}

By Wealth Trust Securities
The secondary Bond market yesterday saw yields decline, mainly on selected tenors on the back of aggressive buying interest. The market extended the downward momentum from the previous day, marking a recovery as the recently elevated yield levels attracted strong demand. Activity and transaction volumes were seen at healthy levels.
In terms of the trade summary at the very short end of the curve, the 15.12.26 maturity traded at the rate of 9.43%. The 15.05.30 maturity traded at the rate of 11.40%. The 01.07.30 and 15.10.30 maturities traded lower at the rates of 11.50% and 11.60% respectively. The 01.02.31 and 01.12.31 maturities traded down the ranges of 11.77% to 11.72% and at the rate of 11.85% respectively. The 15.12.32 traded at 12.00% and the 15.01.33 down the range of 12.18%-12.10%. The 01.06.33 maturity traded at the rate of 12.20%. The 15.06.34 traded down the range of 12.40%-12.35% and the 15.09.34 maturity traded down the range of 12.45%-12.36% while the 15.10.34 traded at 12.40%.
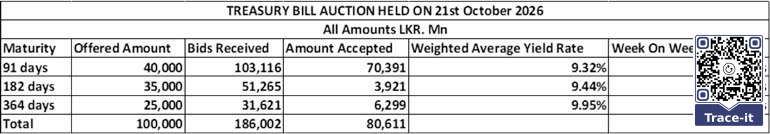
At the weekly Treasury Bill auction conducted yesterday, weighted average yields were seen holding steady with the rate on the 182-day and 364-day tenors remaining unchanged at 9.44% and 9.95% respectively for the second straight week. However, the 91-day tenor maturity saw its yield edge up marginally by 02 basis points to 9.32%.
The Public Debt Management Office (PDMO) raised only Rs. 80.611 billion or 80.61% in total out of the Rs. 100 billion offered in total. The 91-day tenor recorded acceptance above its respective target allocation, while the 182-day and 364-day recorded acceptances below their respective offered amounts.
Total bids received amounted to 1.86 times the overall offer. The Phase II subscription only on the 182-day and 364-day tenors is now open until 3 p.m. on 22.10.2026 at the Weighted Average Yield Rates (WAYRs) determined at the auction (see table for auction details).
In the money market, the net liquidity surplus stood at Rs. 98.13 billion yesterday. A total of Rs. 65.77 billion was deposited at the Central Bank’s SDFR (Standing Deposit Facility Rate) of 8.25%, while an amount of Rs. 0.14 billion was withdrawn from the Central Bank’s SLFR (Standing Lending Facility Rate) of 9.25%.
In addition, the Domestic Operations Department (DOD) of the Central Bank of Sri Lanka mopped out Rs. 32.50 billion by way of an overnight repo auction at a weighted average yield of 8.75%, and Rs. 20 billion through a 30-day term repo auction at the weighted average yield of 9.25%. The weighted average yields on overnight call money and repos were recorded at 9.00% and 9.05% respectively.
Forex market
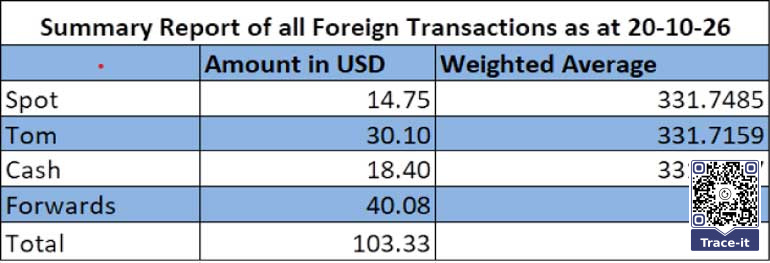
The USD/LKR rate on spot contracts was seen closing at Rs. 331.90/332.00 yesterday, with the rupee depreciating against its previous day’s closing of Rs. 331.60/331.70. The total USD/LKR traded volume for 20 October amounted to $ 103.33 million.
(References: Public Debt Management Office - Ministry of Finance, Central Bank of Sri Lanka, Bloomberg E-Bond Trading Platform, Money Broking Companies)