Thursday Nov 12, 2026
Thursday Nov 12, 2026
Thursday, 5 November 2026 06:24 - - {{hitsCtrl.values.hits}}
By Wealth Trust Securities
 The secondary Bond market yesterday extended its rally for a third consecutive session, with yields declining across the curve on the back of sustained aggressive buying interest.
Market sentiment remained supported by the continued decline in global oil prices, with Brent crude falling to around $ 102 per barrel to a near three-week low, as renewed diplomatic efforts between the US and Iran eased concerns over further supply disruptions and tempered inflationary pressures.
Sentiment was further reinforced by the outcome of the US midterm elections, which saw Democrats secure control of both chambers of Congress. The resulting easing in US Treasury yields, alongside a broader decline in regional bond yields, including India’s 10-year benchmark also extending declines, provided further support. Market activity and transaction volumes remained at robust levels.
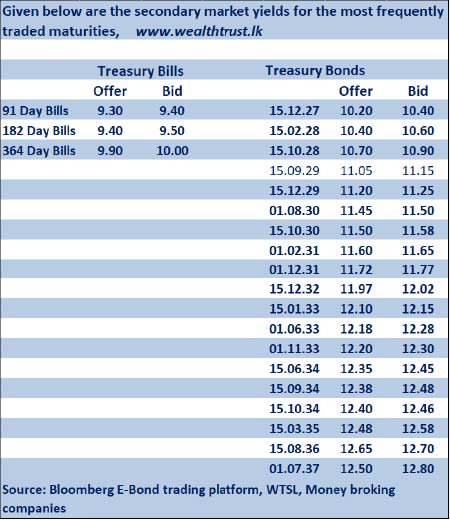
The shorter tenor 15.12.26 and 15.01.27 maturities traded at the rates of 9.40% and 9.45%-9.40% respectively.
On the 2030 maturity tenor, the 01.03.30 traded at the rate of 11.40%, 15.05.30 from 11.45% to 11.40%, 01.08.30 from 11.55% to 11.50% and the 15.10.30 from 11.60% to 11.55%. On the 2031 segment, 01.02.31 and 01.12.31 maturities traded down the ranges of 11.65% to 11.60% and 11.80% to 11.75% respectively. The 15.12.32 traded down the range of 12.03% to 12.00%. The 01.11.33 maturity traded down the range of 12.35% to 12.30%. The 15.10.34 maturity traded down the range of 12.48% to 12.43% and the 15.08.36 down sharply along the range of 12.80% to 12.70%.
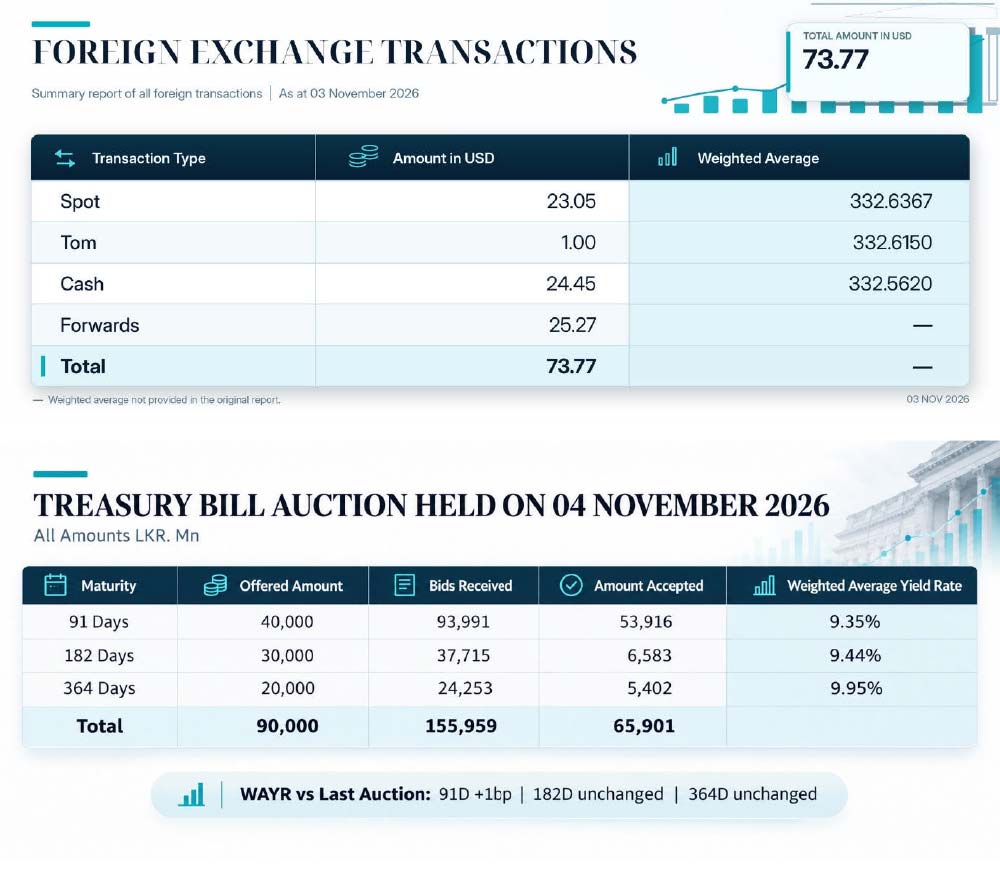
At the weekly Treasury Bill auction conducted yesterday, weighted average yields were seen holding steady with the rate on the 182-day and 364-day tenors remaining unchanged at 9.44% and 9.95% respectively for the fifth straight week. However, the 91-day tenor maturity saw its yield edge up marginally by 01 basis points to 9.35%.
The Public Debt Management Office (PDMO) raised only Rs. 65.90 billion or 73.22% in total out of the Rs. 90 billion offered in total. The 91-day tenor recorded acceptance above its respective target allocation, while the 182-day and 364-day recorded acceptances below their respective offered amounts.
Total bids received amounted to 1.73 times the overall offer.
The Phase II subscription only on the 182-day and 364-day tenors is now open until 3.00 p.m. on 05.11.2026 at the Weighted Average Yield Rates (WAYRs) determined at the auction (see table for auction details).
In the money market, the net liquidity surplus stood at Rs. 126.73 billion yesterday. A total of Rs. 111.85 billion was deposited at the Central Bank’s SDFR (Standing Deposit Facility Rate) of 8.25%, while an amount of Rs. 0.12 billion was withdrawn from the Central Bank’s SLFR (Standing Lending Facility Rate) of 9.25%.
In addition, the Domestic Operations Department (DOD) of the Central Bank of Sri Lanka mopped out Rs. 15 billion by way of an overnight repo auction at a weighted average yield of 8.75% as well as a Rs. 15 billion by way of a 29-day term repo auction at the rate of 9.25%.
The weighted average yields on overnight call money and repos were recorded at 9.04% and 9.12% respectively.
Forex market
The USD/LKR rate on spot contracts or the Rupee was seen closing yesterday at Rs. 332.75/332.80 depreciating against its previous day’s level of Rs. 332.65/332.70
The total USD/LKR traded volume for 3 November amounted to $ 73.77 million.
(References: Public Debt Management Office - Ministry of Finance, Central Bank of Sri Lanka, Bloomberg E-Bond Trading Platform, Money Broking Companies)