Monday Sep 14, 2026
Monday Sep 14, 2026
Monday, 14 September 2026 00:46 - - {{hitsCtrl.values.hits}}
By Wealth Trust Securities
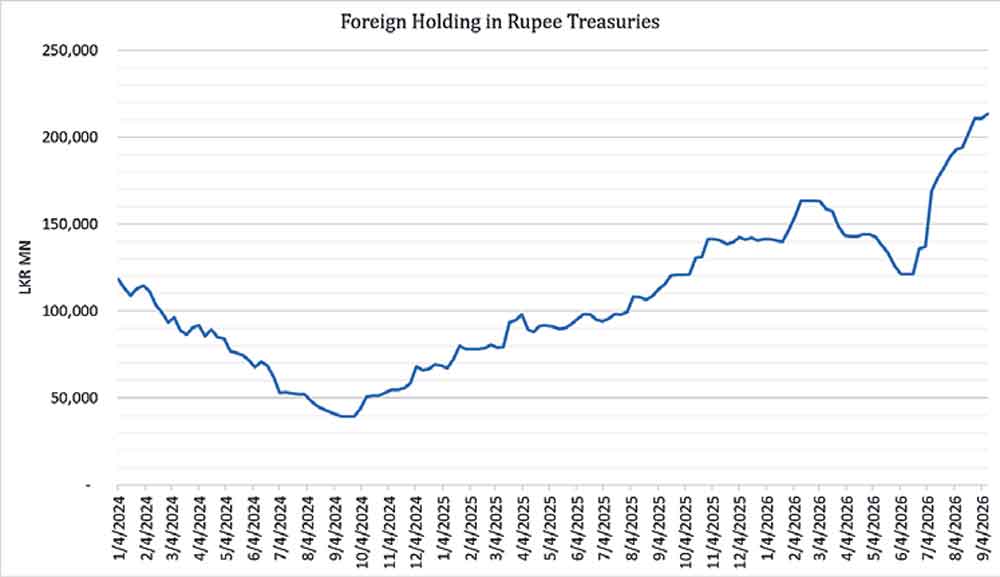
After a lull of a week, the foreign holding in rupee Treasuries increased significantly once again by the tune of Rs 2.75 billion for the week ending 10 September. As a result, the total foreign holdings of rupee treasuries grew by 1.3% week-on-week to stand at Rs. 213.40 billion.
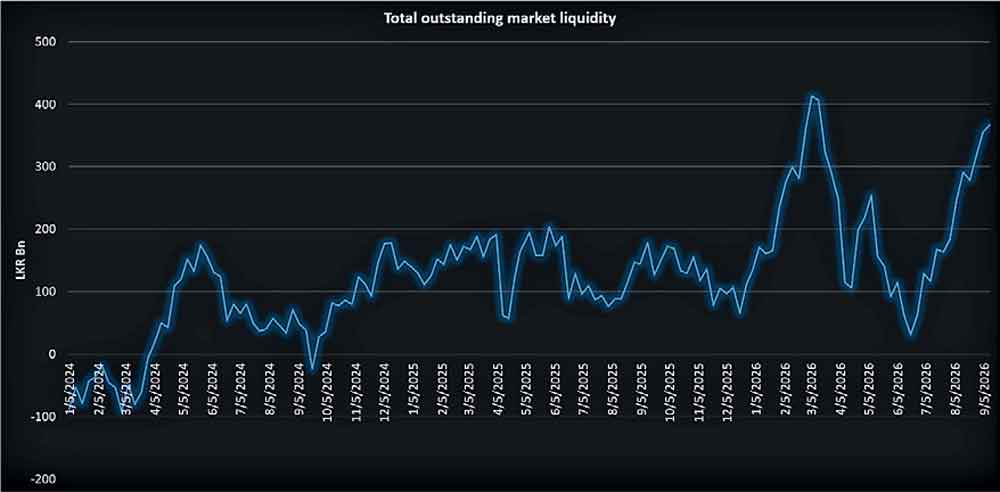
Money market liquidity witnessed another week-on-week increase, hitting its highest level in 26 weeks or since March this year. The jump in liquidity to Rs 366.11 billion was against its previous week’s total outstanding figure of Rs 355.3 billion.
The weighted average Call Money and Repo rates stood at 8.87% and 8.95%, respectively.
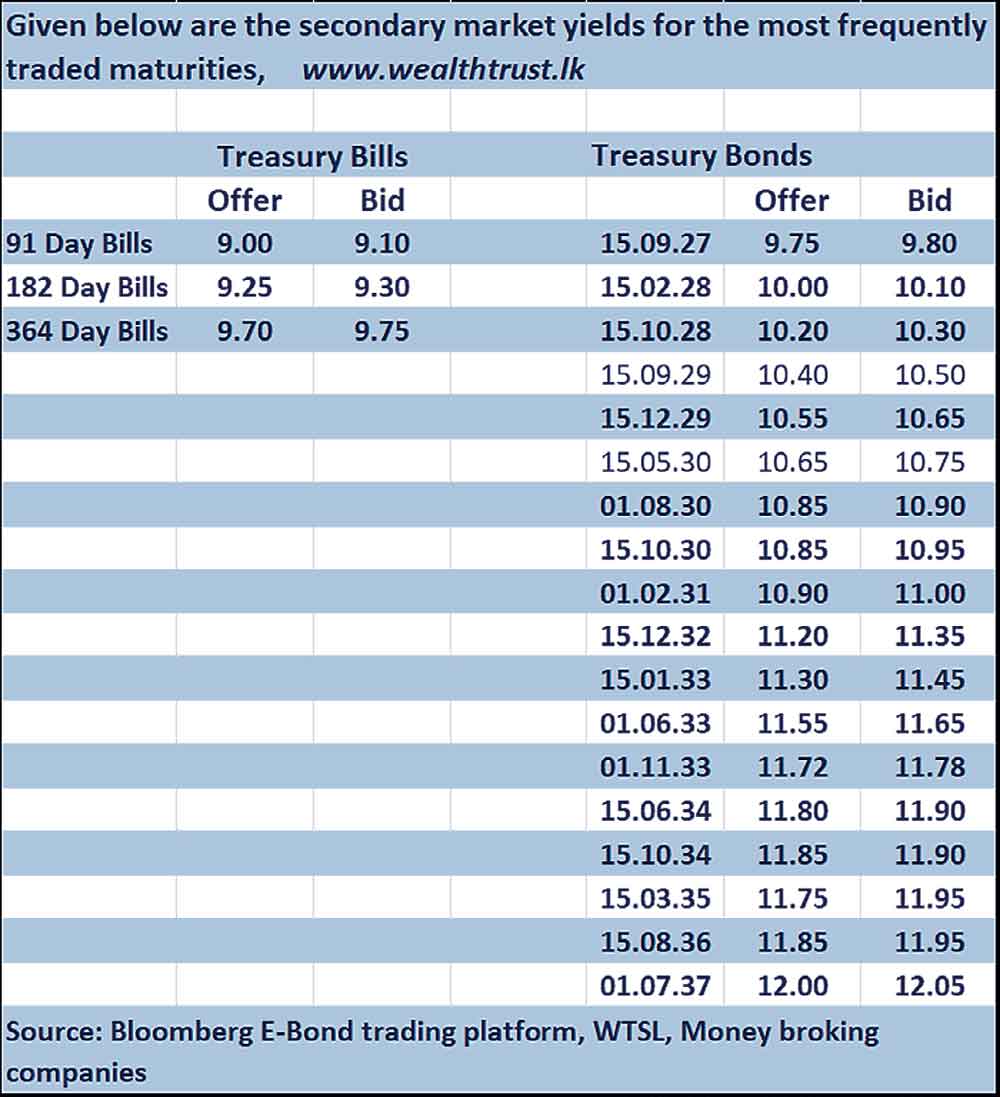
The secondary Bond market came under pressure last week, with yields moving higher as sentiment was weighed down by escalating tensions in the Middle East, the resulting increase in global oil prices and a broader rise in global government bond yields.
However, the upward movement in domestic yields remained relatively measured, with higher rate levels repeatedly drawing renewed buying interest. This helped trigger periodic recoveries during the week and provided a degree of support to the market, containing the extent of the overall increase in yields. As continued foreign demand, robust money market liquidity and strong domestic macroeconomic fundamentals acted as a counterbalance.
The key event of the week was last Friday’s Treasury Bond auction, where auction weighted averages were seen coming in slightly above prevailing secondary market levels. However, this was met with renewed buying interest emerging once again at the elevated levels, prompting a partial recovery towards the close of the week.
Overall, secondary market two-way quotes ended the week higher on a week-on-week basis.
In the secondary bond market, the 2028 maturity segment was seen changing hands within the range of 10.05% to 10.20% while on the 2029, the 15.10.29 traded at 10.45% while the 15.12.29 traded from a weekly low of 10.50% to a high of 10.60%. In the 2030 segment, the 01.03.30 traded at 10.60%, while the 15.05.30 traded at 10.65%. The 01.08.30 traded up from an intraweek low of 10.70% up to a high a of 10.88%, while the 15.10.30 traded within the intraweek range of 10.75%-10.90%.
The 01.10.32 traded up from an intraweek low of 11.10% to a high of 11.20%, while the 15.12.32 traded at 11.25%.
The 01.06.33 traded up from an intraweek low of 11.50% to a high of 11.60%, while the 01.11.33 traded up from an intraweek low of 11.65% to a high of 11.80%, before easing back to 11.70%. The 15.10.34 traded up from an intraweek low of 11.80% to a high of 11.90%.
On the longer end, the 15.08.36 traded higher from an intraweek low of 11.90% to a high of 11.95%.
To recap, at last Wednesday’s weekly Treasury Bill auction, the weighted averages exhibited mixed results. The longer tenors (182 day & 364 day) extended their downward trajectory while the 91-day bucked the trend by increasing.
Accordingly, the 182-day yield fell by 3 basis points to 9.24%, while the 364-day bill declined by 4 basis points to 9.77%. The 91-day increased by 07 basis points to 9.03%.
Despite the mixed outcome, the longer tenors extended their run of declines for a ninth consecutive week.
The Public Debt Management Office (PDMO) successfully raised the full Rs. 80 billion offered. The amount accepted on the 91-day Bill fell short of its respective offering, with the shortfall offset by higher-than-offered acceptances on the longer tenors. Total bids received amounted to 1.87 times the overall offer.
This was followed by a round of Treasury Bond auctions conducted last Friday, where the entire offered amount of Rs 150.00 billion was raised at the first phase of the auction in competitive bidding. The auction recorded a mixed outcome with weighted averages coming in slightly above its pre-auction rates despite the full acceptance at the first phase.
The bids received to accepted amount ratio stood at 2.58 times.
Maturity-wise the results were as follows:
The shorter tenor 01.08.30 maturity was issued at a weighted average yield of 10.83%, above its pre-auction secondary two-way quote of 10.70%/10.75%
The 15.10.34 maturity was issued at the weighted average yield of 11.96%, as compared to a pre-auction market two-way of 11.85%/11.90%.
The 01.07.37 maturity was issued at a weighted average of 12.08% above its pre-auction market two-way of 11.90%/12.00%.
Forex market
The rupee or the USD/LKR rate was seen depreciating marginally, to close the week ending 11 September at Rs. 328.60/328.70 as against its previous week’s closing of Rs. 328.22/328.30. Intraweek the Rupee traded within the highs and lows of Rs. 328.15 to Rs. 329.05
The average daily USD/LKR traded volume over the first four trading days of the week stood at $ 100.81 million.
 (References: Public Debt Management Office - Ministry of Finance, Central Bank of Sri Lanka, Bloomberg E-Bond Trading Platform, Money Broking Companies)