Thursday Oct 01, 2026
Thursday Oct 01, 2026
Tuesday, 29 September 2026 04:31 - - {{hitsCtrl.values.hits}}
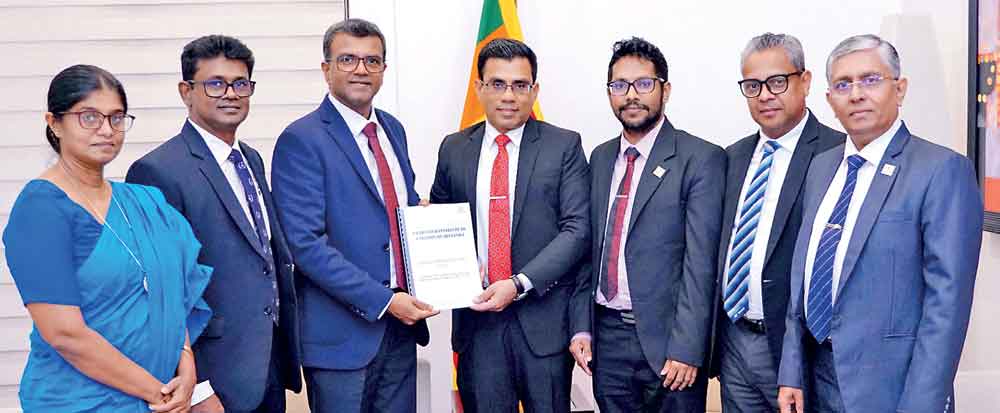
Chartered Institute of Taxation of Sri Lanka President Ruwan Gamage (centre) along with other representatives of the Institute present the proposal for 2027 Budget to Treasury Secretary Dr. Harshana Suriyapperuma
 Moots broadening the tax base, simplifying the tax system and reduction in tax rates
The Chartered Institute of Taxation of Sri Lanka (CITSL) in furtherance of the statutory mandate vested in the Institute, submitted its Budget proposals for the year 2027 to Finance Ministry Secretary Dr. Harshana Suriyapperuma last week.
The proposals were formulated with the principal objectives of broadening the tax base, simplifying the tax system and, thereby, creating an appropriate basis for reducing tax rates while enhancing overall tax revenue. The proposals also identify potential areas through which the tax base could be expanded without increasing existing tax rates, thereby facilitating a broader and more equitable participation of persons liable to tax in contributing to the national economy.
Furthermore, the proposals contain recommendations for the simplification of tax laws, procedures and administrative mechanisms, with the objective of reducing unnecessary complexity and compliance costs, minimising avoidable disputes and assessments, alleviating the administrative burden placed on taxpayers, and improving the efficiency and effectiveness of tax collection mechanisms.
Accordingly, the proposals seek to contribute towards the establishment of a fair, transparent, efficient and taxpayer-friendly tax system, while strengthening tax compliance, broadening the tax base and ensuring the sustainable enhancement of Government revenue without placing an undue burden on compliant taxpayers.
CITSL is a professional body established under the Sri Lanka Institute of Taxation Act, No. 21 of 2000, for the advancement of tax education and the development of the taxation profession. The Institute was subsequently granted chartered status through the amendment of the said Act by Act No. 13 of 2023.
In particular, Section 3(1)(g) of the CITSL Act expressly empowers the Institute to make recommendations to the Government for the improvement and simplification of tax laws and practices, to identify and highlight anomalies in laws relating to taxation, and to make observations and recommendations in respect of proposed amendments to such laws. The submission of proposals for 2027 Budget was in that connection.