Thursday Sep 17, 2026
Thursday Sep 17, 2026
Wednesday, 16 September 2026 14:28 - - {{hitsCtrl.values.hits}}
By Wealth Securities
The secondary Bond market saw yields extend the bearish momentum, rising sharply for a second consecutive session yesterday. The upward pressure was observed across the entire yield curve but most pronounced on the short to belly end. However, the upward swing was moderated by renewed buying interest, which drove a partial recovery. Nevertheless, Bond yields closed higher, despite the retracement.
Despite the bearish tone, market activity remained robust, with strong turnover and several sizeable block trades.
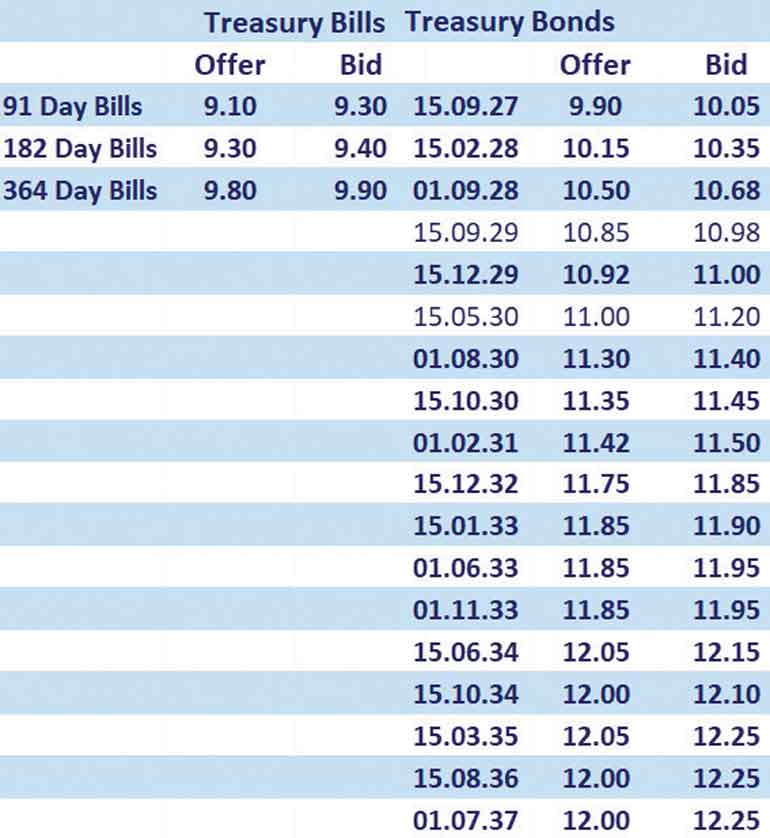
Accordingly, the 15.09.29 and 15.12.29 maturities traded higher at 10.95% and 11.05%-10.95%, respectively. The 01.07.30, 01.08.30 and 15.10.30 maturities traded higher at 11.40%, 11.45%-11.15% and 11.50%-11.40%, respectively. The 01.02.31 and 01.12.31 maturities traded at 11.55%-11.35% and 11.50% respectively. The 15.12.32 traded within the range of 11.90%-11.80% and the 15.01.33 at 11.90%. The 01.06.33 and 01.11.33 traded at the yields of 11.85% and 11.95%-11.90% respectively. The 15.06.34 and 15.10.34 maturities traded at 12.15%-12.10% and 12.02% respectively.
The Treasury Bill auction scheduled for today will have a total of Rs. 70 billion on offer, which is marginally below the estimated corresponding maturing amount of Rs. 73.16 billion. This will comprise of Rs. 25 billion on the 91-day maturity, Rs. 25 billion on the 182-day maturity and Rs. 20 billion on the 364-day maturity.
For context, at last Wednesday’s weekly Treasury Bill auction, the weighted averages exhibited mixed results. The longer tenors (182 day and 364 day) extended their downward trajectory while the 91-day maturity bucked the trend by increasing.
Accordingly, the 182-day yield fell by 3 basis points to 9.24%, while the 364-day Bill declined by 4 basis points to 9.77%. The 91-day increased by 7 basis points to 9.03%.
Despite the mixed outcome, the longer tenors extended their run of declines for a ninth consecutive week.
The Public Debt Management Office (PDMO) successfully raised the full Rs. 80 billion offered. The amount accepted on the 91-day Bill fell short of its offering, with the shortfall offset by higher-than-offered acceptances on the longer tenors. Total bids received amounted to 1.87 times the overall offer.
In the money market, the net liquidity surplus stood at Rs. 92.55 billion yesterday. Of this, Rs. 88.59 billion was deposited with the Central Bank through the Standing Deposit Facility (SDF) at 8.25%, while Rs. 1.04 billion was withdrawn through the Standing Lending Facility (SLF) at 9.25%.
Meanwhile, the Domestic Operations Department (DOD) of the Central Bank absorbed further liquidity through a Rs. 5 billion overnight Repo at a weighted average rate of 8.70%.
The weighted average rates on overnight call money and repos were 8.89% and 8.95% respectively.
Forex market
The Rupee depreciated against the US dollar in spot trading, closing at Rs. 330.65/331.10, compared with the previous day’s close of Rs. 329.15/329.35.
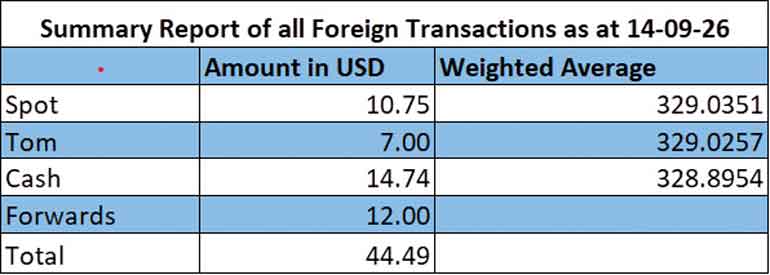
The total USD/LKR traded volume on 14 September was $ 44.49 million.
(References: Public Debt Management Office - Ministry of Finance, Central Bank of Sri Lanka, Bloomberg E-Bond Trading Platform, Money Broking Companies)