Thursday Oct 01, 2026
Thursday Oct 01, 2026
Wednesday, 30 September 2026 00:07 - - {{hitsCtrl.values.hits}}
By Wealth Trust Securities
The secondary Bond market remained on a bearish footing yesterday, with yields edging up further as the negative momentum continued for a second consecutive session.
The broader news flow remained bearish, with global Bond yields continuing to remain elevated, while the Reserve Bank of Australia’s latest rate hike reinforced the relatively hawkish global monetary policy backdrop. Meanwhile, Brent crude remained elevated, well above $ 100 per barrel, amid continued uncertainty surrounding US-Iran negotiations, keeping inflationary and external sector pressures in focus.
Against this backdrop, selling interest was witnessed across key maturities, pushing yields moderately higher as the session progressed. Nevertheless, the upward movement remained relatively contained, with market participants maintaining a cautious stance ahead of tomorrow’s Monetary Policy Decision.
Market activity and transaction volumes remained at subdued levels.
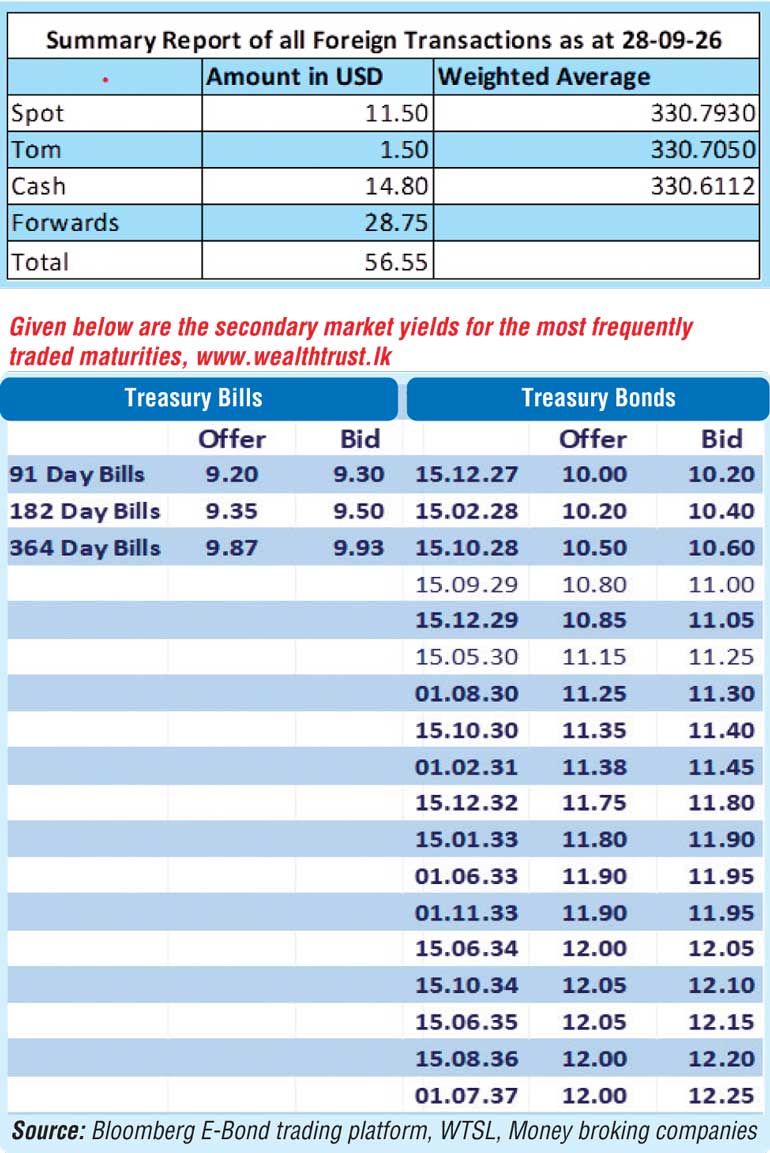
In the trade summary, the 15.12.28 traded at 10.65%-10.68%, while the 15.05.30 and 15.10.30 maturities traded up in the range of 11.25%-11.30% and 11.35%-11.40% respectively. The 01.02.31 and 15.12.32 changed hands at 11.30%-11.40% and 11.70% respectively. The 15.12.32 changed hands at the rate of 11.80%. The 01.06.33 and 01.11.33 both traded at 11.95%, while the 15.10.34 maturity traded at12.05%-12.10%.
This comes ahead of the Monetary Policy Review Meeting No. 05 for 2026, with the policy decision due to be announced at 7:30 a.m. today (30). To recap, at the previous Monetary Policy Review held in July, the CBSL opted to keep policy rates unchanged, with the Overnight Policy Rate holding at 8.75% and the Standing Deposit and Lending Facility rates remaining at 8.25% and 9.25% respectively.
The Treasury Bill auction scheduled for today will have a total of Rs. 80 billion on offer, comprising of Rs. 35 billion in the 91-day maturity, Rs. 25 billion in the 182-day maturity and Rs. 20 billion in the 364-day maturity. The amount on offer is below estimated Rs. 91.79 billion in maturities.
For context, at last Wednesday’s weekly Treasury Bill auction, weighted average yields increased across the board for a second consecutive week- albeit marginally.
Accordingly, the 91-day yield rose by two basis points to 9.20%, while the 182-day and 364-day yields increased by 1 basis point and 5 basis points to 9.37% and 9.93%, respectively.
The Public Debt Management Office (PDMO) successfully raised the full Rs. 60 billion offered. The 91-day tenor recorded acceptance above its target allocation, while the 182-day and 364-day tenors fell short of their respective targets. Total bids received amounted to 2.41 times the amount offered.
The full Rs. 6 billion available under phase 2 of the auction was fully raised, with bids received exceeding the amount offered by Rs. 12 billion.
In the money market, the net liquidity surplus was recorded at Rs. 151 billion. Of this, Rs. 113.35 billion was deposited at the Central Bank’s SDFR (Standing Deposit Facility Rate) of 8.25%, while no funds were withdrawn from the Central Bank’s SLFR (Standing Lending Facility Rate) of 9.25%.
In addition, the Domestic Operations Department (DOD) of the Central Bank of Sri Lanka absorbed Rs. 38 billion via an overnight repo auction at the rate of 8.74%.
The weighted average yields on overnight call money and repos were recorded at 8.96% and 9.03% respectively.
Forex market
The USD/LKR spot rate appreciated marginally to close at Rs. 330.75/330.90 yesterday, compared with Rs. 330.95/331.05 on the previous day. The total USD/LKR traded volume for 28 September amounted to $ 56.55 million.
(References: Public Debt Management Office - Ministry of Finance, Central Bank of Sri Lanka, Bloomberg E-Bond Trading Platform, Money Broking Companies)