Thursday Nov 05, 2026
Thursday Nov 05, 2026
Wednesday, 4 November 2026 00:06 - - {{hitsCtrl.values.hits}}
By Wealth Trust Securities
The secondary Bond market yesterday saw yields decline, particularly across medium- to longer-tenor maturities, extending the downward momentum from the previous session. Market sentiment was buoyed by a sharp decline in global oil prices, as renewed optimism surrounding a potential diplomatic breakthrough between the US and Iran eased concerns over further supply disruptions and tempered near-term inflationary pressures. Market activity and transaction volumes were seen at robust levels.
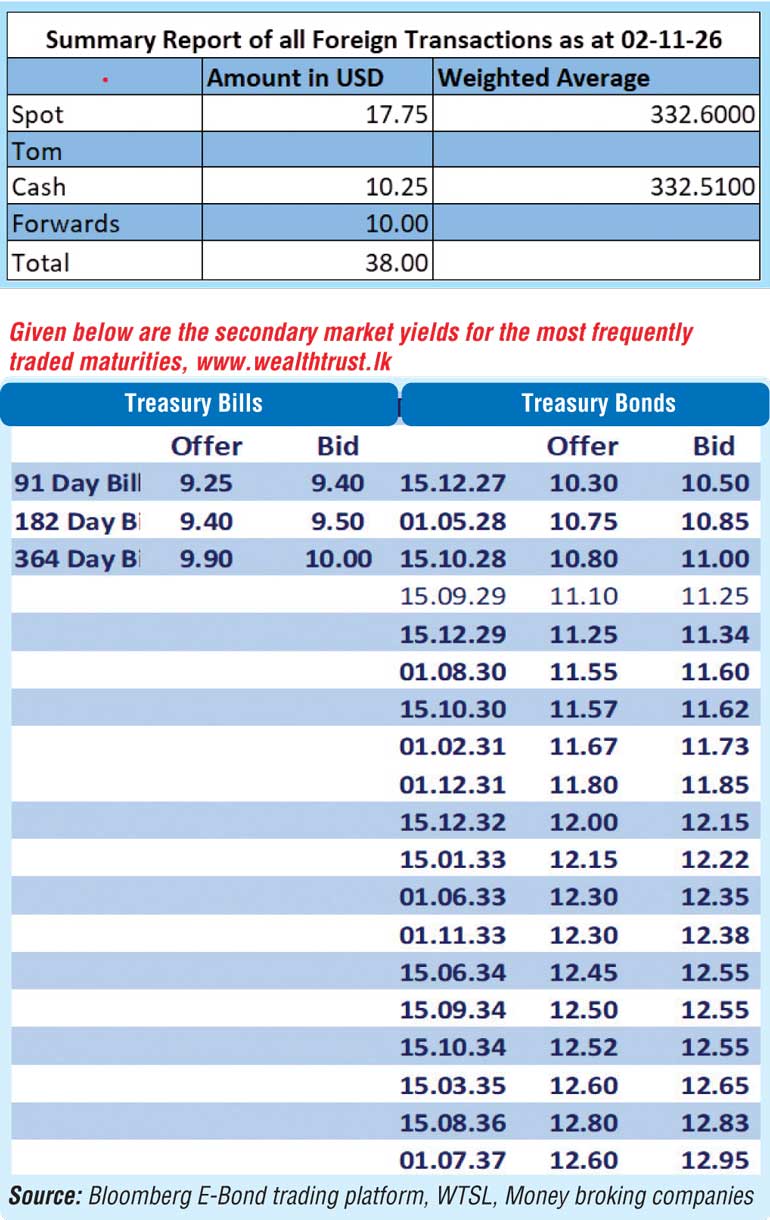
In terms of the trade summary, the 01.03.30 traded at the rate of 11.45% and the 15.10.30 at the rate of 11.60%. The 01.02.31 and 15.03.31 maturities traded within the range of 11.72%-11.70% and the 01.12.31 maturity at the rate of 11.85%. The 15.01.33, 01.06.33 and 01.11.33 maturities traded at the rates of 12.20%, 12.35% and 12.34%. The 15.10.34 and the 15.08.36 maturities rallied down the ranges of 12.56%-12.52% and 12.87%-12.82% respectively.
The Treasury Bill auction scheduled for today will have a total of Rs. 90 billion on offer, comprising of Rs. 40 billion on the 91-day maturity, Rs. 30 billion on the 182-day maturity and Rs. 20 billion on the 364-day maturity. The amount on offer is below the estimated Rs. 122.89 billion in maturities corresponding to the auction.
To recap: At the weekly Treasury Bill auction conducted last Wednesday (28 Oct.), weighted average yields were seen holding steady with the rate on the 182-day and 364-day tenors remaining unchanged at 9.44% and 9.95% respectively for the fourth straight week. However, the 91-day tenor maturity saw its yield edge up marginally by 2 basis points to 9.34%.
The Public Debt Management Office (PDMO) raised only Rs. 86.48 billion or 86.48% in total out of the Rs. 100 billion offered in total. The 91-day tenor recorded acceptance above its respective target allocation, while the 182-day and 364-day recorded acceptances below their respective offered amounts.
Total bids received amounted to 2.25 times the overall offer.
In the money market, the net liquidity surplus stood at Rs. 138.68 billion yesterday. A total of Rs. 126.69 billion was deposited at the Central Bank’s SDFR (Standing Deposit Facility Rate) of 8.25% as against an amount of Rs 0.01 billion withdrawn from the Central Bank’s SLFR (Standing Lending Facility Rate) of 9.25%.
In addition, the Domestic Operations Department (DOD) of the Central Bank of Sri Lanka mopped out Rs. 12 billion by way of an overnight repo auction at a weighted average yield of 8.75%. The weighted average yields on overnight call money and repos were recorded at 9.04% and 9.11% respectively.
The USD/LKR rate on spot contracts was seen closing at Rs. 332.65/332.70 yesterday, with the rupee depreciating slightly against its previous day’s closing of Rs. 332.55/332.65. The total USD/LKR traded volume for 2 November amounted to $ 38 million.
(References: Public Debt Management Office - Ministry of Finance, Central Bank of Sri Lanka, Bloomberg E-Bond Trading Platform, Money Broking Companies)