Tuesday Sep 29, 2026
Tuesday Sep 29, 2026
Monday, 28 September 2026 04:36 - - {{hitsCtrl.values.hits}}
By Wealth Trust Securities
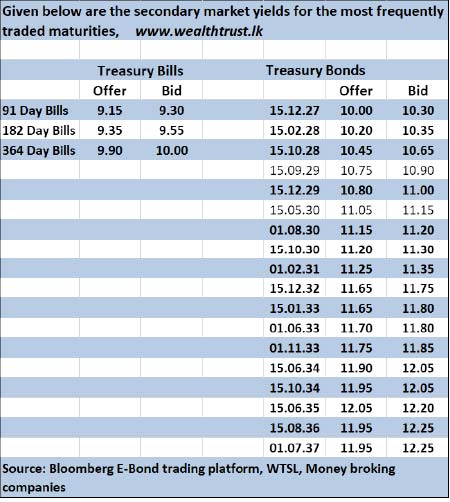 The secondary Bond market rallied through the first half of the week ending 25 September, extending the positive momentum from the previous week.
Sentiment strengthened following Fitch Ratings’ upgrade of Sri Lanka’s sovereign rating to ‘B-’ with a Stable Outlook, while Brent crude initially falling below $ 100 per barrel amid renewed Middle East diplomatic optimism providing further support. The IMF’s latest assessment also boosted sentiment, highlighting economic resilience, strong fiscal performance and improving foreign reserves.
However, momentum faded following Wednesday’s Treasury Bill auction, where yields increased further across all tenors, while profit-taking emerged after the sharp decline in Bond yields. Towards the latter part of the week, renewed Middle East uncertainty, higher oil prices and rising global Bond yields weighed on sentiment.
Consequently, yields retraced from intraweek lows, surrendering part of the earlier gains. Nevertheless, shorter-tenor two-way quotes closed lower week-on-week, while longer tenors broadly returned to previous week levels. Activity remained healthy overall but moderated towards the week’s end as participants adopted a watchful stance ahead of the Monetary Policy review.
The 15.02.28 and 15.10.28 traded at 10.20% and 10.42%, respectively, while the 15.12.28 traded between 10.66%-10.50%. The 15.09.29 and 15.10.29 traded at 10.85% and 11.05%, while the 15.12.29 declined from 10.85% to 10.75%.
The 2030 and 2031 tenors exhibited a clear V-shaped yield pattern. The 01.08.30 declined from 11.30% to 10.95% before retracing to 11.15%, while the 15.10.30 moved from 11.40% to 10.95% before returning to 11.30%. The 01.02.31 similarly declined from 11.40% to 11.00% before retracing to 11.30%.
The 01.10.32 traded between 11.55%-11.35%, while the 15.12.32 rallied to 11.35% before reversing to 11.75%, ending Friday around 11.70%. The 15.01.33 traded from 11.47% to 11.65%. The 01.06.33 moved from 11.80% to 11.55% before retracing to 11.72%, while the 01.11.33 traded between 11.85%-11.60%.
The 15.06.34 traded between 12.00%-11.75%, while the 15.10.34 rallied from 12.01% to 11.75% before reversing to 12.03%. The 15.03.35 traded at 12.15%-12.18%, while the 15.06.35 traded at 12.00%-11.97%.
To recap, at last Wednesday’s weekly Treasury Bill auction, weighted average yields increased across the board for a second consecutive week- albeit marginally.
Accordingly, the 91-day yield rose by 2 basis points to 9.20%, while the 182-day and 364-day yields increased by 1 basis point and 5 basis points to 9.37% and 9.93%, respectively.
The Public Debt Management Office (PDMO) successfully raised the full Rs. 60 billion offered. The 91-day tenor recorded acceptance above its target allocation, while the 182-day and 364-day tenors fell short of their respective targets. Total bids received amounted to 2.41 times the overall offer.
The total available amount of Rs. 6 billion at the phase two of the auction was fully raised, receiving an oversubscription of Rs. 12 billion in bids received.
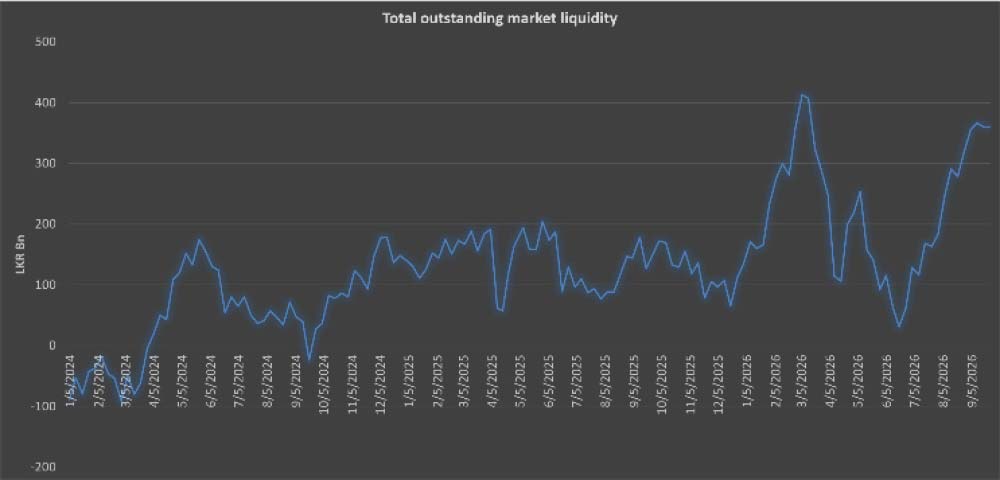
The Money market liquidity surplus as at the week ending 25 September increased to Rs. 370.92 billion up as against its previous weeks total outstanding figure of Rs. 359.79 billion.
The weighted average Call Money and Repo rates stood at 8.96% and 9.00% respectively, up from their previous week’s levels of 8.91% and 8.96%, respectively.
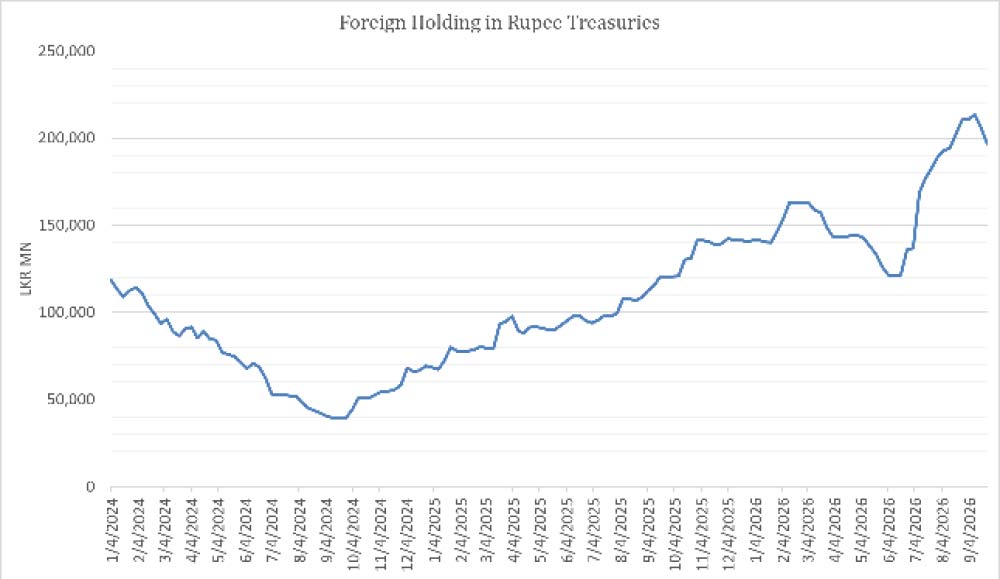
The foreign holdings of rupee-denominated Government securities recorded a net outflow for the second consecutive week, amounting to Rs. 9.17 billion during the week ended 24 September. A drop of 4.50% week on week. Accordingly, the total foreign holdings of rupee treasuries dropped to Rs. 196.93 billion.
Furthermore, the rupee or the USD/LKR rate was seen appreciating, to close the week ending 25 September at Rs. 330.40/330.50 as against its previous week’s closing of Rs. 330.75/331.25. This was subsequent to trading within an intraweek high of Rs. 329.30 and a low of Rs. 331 intraweek.
The average daily USD/LKR traded volume over the first four trading days of the week stood at $ 69.85 million.
(References: Public Debt Management Office - Ministry of Finance, Central Bank of Sri Lanka, Bloomberg E-Bond Trading Platform, Money Broking Companies)