Wednesday Sep 30, 2026
Wednesday Sep 30, 2026
Wednesday, 12 August 2026 05:39 - - {{hitsCtrl.values.hits}}
By Wealth Trust Securities
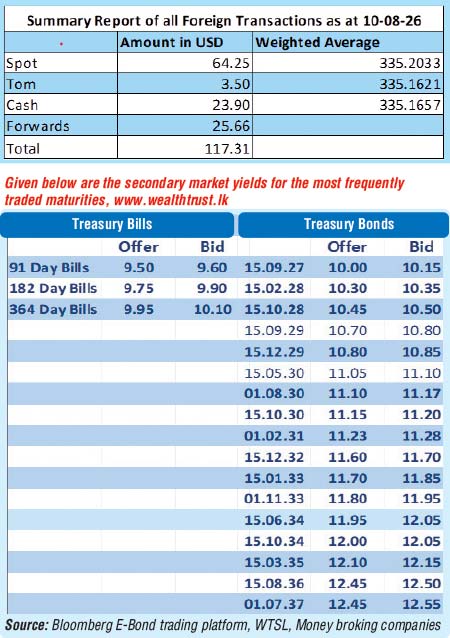 The secondary Bond market yesterday saw rates remain broadly steady, as the market consolidated the gains from the previous day’s rally. Activity and transaction volumes were seen at healthy levels.
The 15.12.28 maturity traded at 10.51%. The 15.05.30 and 15.10.30 maturities traded at 11.05%-11.00% and 11.15% respectively. The 01.02.31 maturity traded at 11.25%. The 15.10.34 maturity traded at 12.05%-12.00%. The 01.07.37 maturity traded at 12.52-12.50%.
The Treasury Bill auction scheduled for today, will have a total of Rs. 140 billion Treasury Bills on offer, below the estimated maturing amount of Rs. 158.22 billion. This will comprise of Rs. 55 billion offered on the 91-day maturity, Rs. 50 billion on the 182-day maturity and Rs. 35 billion on the 364-day maturity.
To recap: At the weekly Treasury Bill auction held last Wednesday, the weighted average yields dropped for the fourth consecutive week. Accordingly, the yield on the 91-day tenor declined by 9 basis points to 9.77% and the 182-day maturity by a steep 22 basis points to 9.99% and the 364-day maturity declined by 01 basis point to 10.19%. The auction successfully raised the full Rs. 140 billion offered at the first phase of competitive bidding. Maturity-wise, the shorter tenors raised more than or equal to their respective amounts offered, while less than the amount offered was accepted for the one-year tenor. The bids received exceeded the offered amount by 2.41 times.
Demand extended into the second phase with the full Rs. 14 billion offered being taken up against a total market subscription of Rs. 58.57 billion. Accordingly, the aggregate accepted amount stood at Rs. 154 billion. This was followed by a rally in the secondary T-Bill market which saw maturities trade below their respective weighted averages.
In the money market, the net liquidity surplus stood at Rs. 194.03 billion yesterday. Of this, Rs. 94.16 billion was deposited at the Central Bank’s Standing Deposit Facility (SDF) at 8.25% as against an amount of Rs 0.13 billion withdrawn via the Central Bank’s Standing Deposit Facility (SDF) at 9.25%. A further Rs. 100 billion was mopped up through an overnight Repo auction conducted by the Domestic Operations Department (DOD) at a weighted average rate of 8.74% as well as Rs. 20 billion via a term Repo at the rate of 9.08%.
The weighted average rates on overnight call money and Repos were 8.84% and 8.88% respectively.
Forex market
The USD/LKR rate on spot contracts was seen closing at the day at Rs. 334.50/334.60, with the Rs. appreciating steadily further as against its previous day’s close of Rs. 335.10/335.18.
The total USD/LKR traded volume on 10 August was $ 117.31 million.
(References: Public Debt Management Office - Finance Ministry, Central Bank of Sri Lanka, Bloomberg E-Bond Trading Platform, Money Broking Companies)