Monday Sep 21, 2026
Monday Sep 21, 2026
Monday, 21 September 2026 03:18 - - {{hitsCtrl.values.hits}}
By Wealth Trust Securities
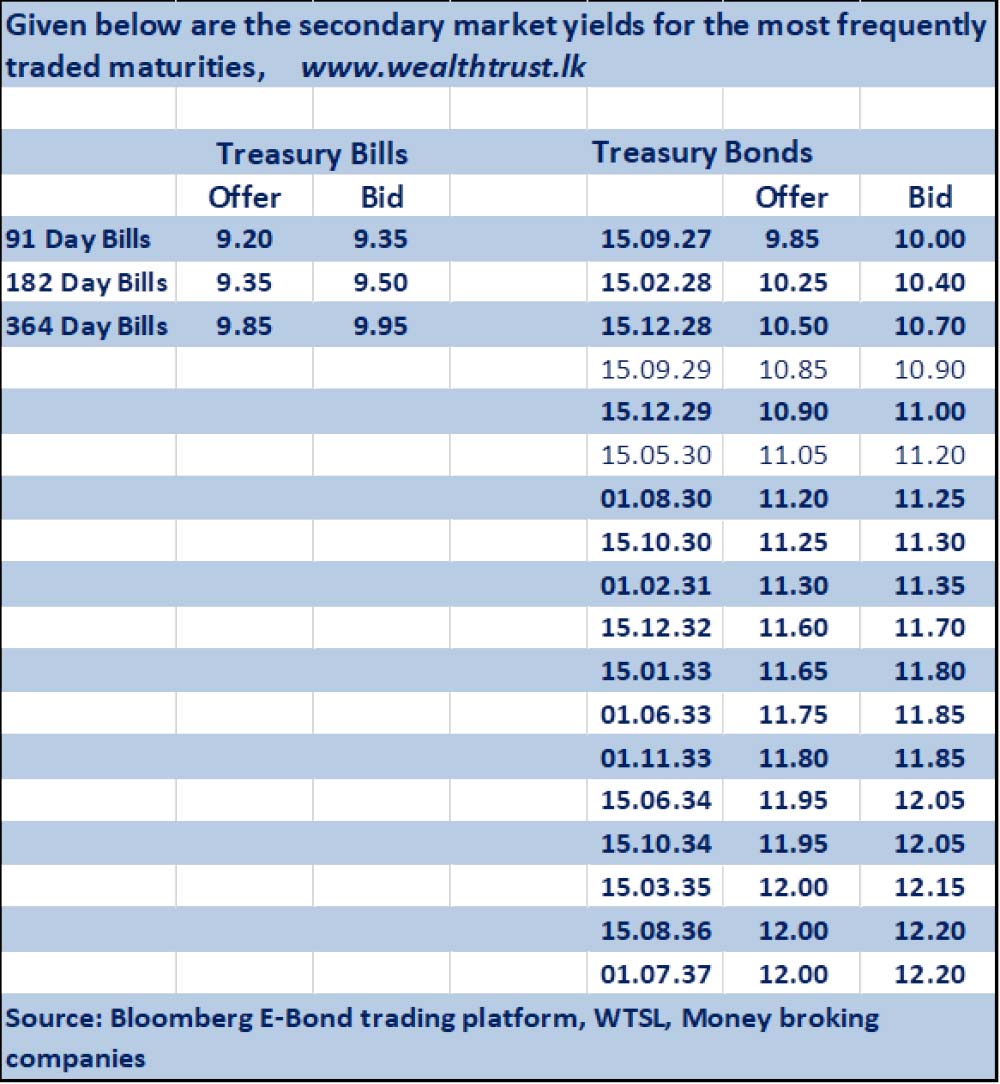 The secondary Bond market last week initially began on a bearish footing, with yields rising sharply across much of the curve. This came amid elevated global oil prices, continued Middle East tensions and higher global Bond yields. Concerns over inflationary and external sector pressures, together with expectations of a relatively hawkish global monetary policy backdrop, kept sentiment weak through the first three days of trading sessions.
However, the tone shifted from Thursday as the elevated yield levels attracted renewed buying interest. The recovery extended into Friday and gained further support from softer Brent crude prices and easing US Treasury yields, which helped temper inflation concerns and improve broader risk sentiment. Sentiment was also supported by signs of renewed diplomatic engagement with regard to the ongoing Middle Eastern tensions.
Overall, the secondary Bond market staged a notable recovery during the latter part of the week, with renewed buying interest driving yields lower across the yield curve and helping reverse part of the sharp sell-off seen earlier in the week. Despite this, secondary Bond market two-way quotes closed higher, week on week, resulting in an upward shift in the yield curve. Activity and transaction volumes continued to be seen at robust levels.
During the week yields see-sawed, trading in an inverted U-shape pattern. The 15.09.29 maturity started last week at 10.70%, moved up to a high of 11.10%, before easing back to trade at the rate of 10.90% at the close of the week.
On the 2030 segment, the 01.08.30 traded up from an initial low of 10.90% to a weekly high of 11.45%, before recovering to 11.25% on Friday. The 15.10.30 followed a similar path, moving from an early low of 11.10% to a high of 11.50%, before easing back to 11.30%.
The 01.02.31 rose to a weekly high of 11.65%, before staging a strong recovery back down to 11.30%.
Further out, the 15.12.32 climbed from a low of 11.70% to a high of 11.90%, before recovering to 11.60%. The 15.01.33 moved from an initial low of 11.80% to a high of 11.95%, before easing back down to 11.80%. The 01.11.33 rose from around 11.85% to a high of 12.00%, before retracing to 11.82%.
On the 2034 segment, the 15.09.34 moved up from around 12.00% to a weekly high of 12.20%, before easing to 12.05%. The 15.10.34 rose from an initial low of 11.96% to a high of 12.10%, before retracing modestly thereafter to trade at the rate of 12.05%.
To recap, at last Wednesday’s weekly Treasury Bill auction, weighted averages reversed course and increased across the board breaking a downtrend streak of 11 weeks.
Accordingly, the yield on the 91-day yield rose by 15 basis points to 9.18%, the 182-day Bill by 12 basis points to 9.36% and the 364-day Bill by 11 basis points to 9.88%.
The Public Debt Management Office (PDMO) successfully raised the entire Rs. 70 billion offered, with each tenor meeting its targeted allocation. Total bids received amounted to 2.45 times the offer.
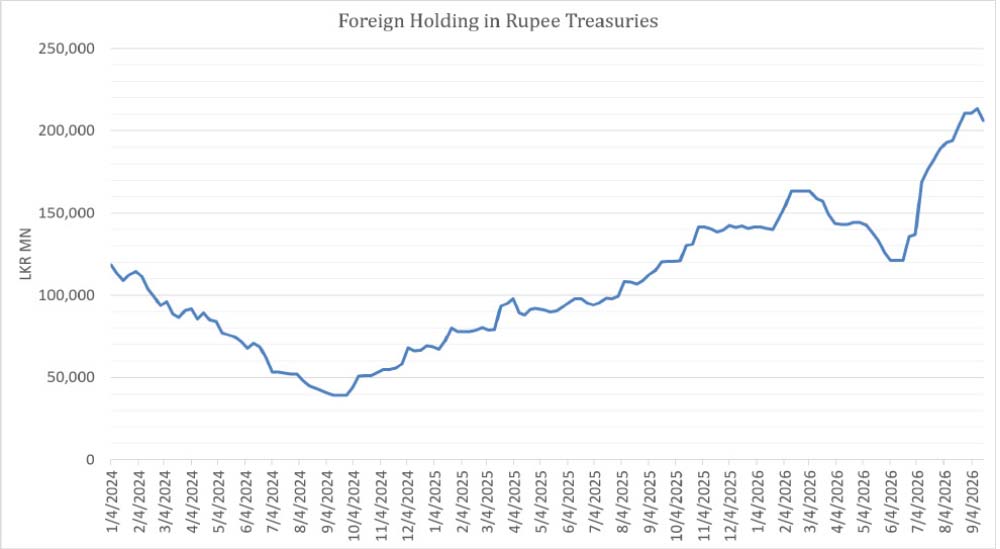
Meanwhile, the foreign holdings of rupee-denominated Government securities recorded a net outflow of Rs. 7.30 billion during the week ended 17 September, breaking a 14 consecutive week streak of increases prior. Accordingly, the total foreign holdings of rupee treasuries dropped to Rs. 206.10 billion.
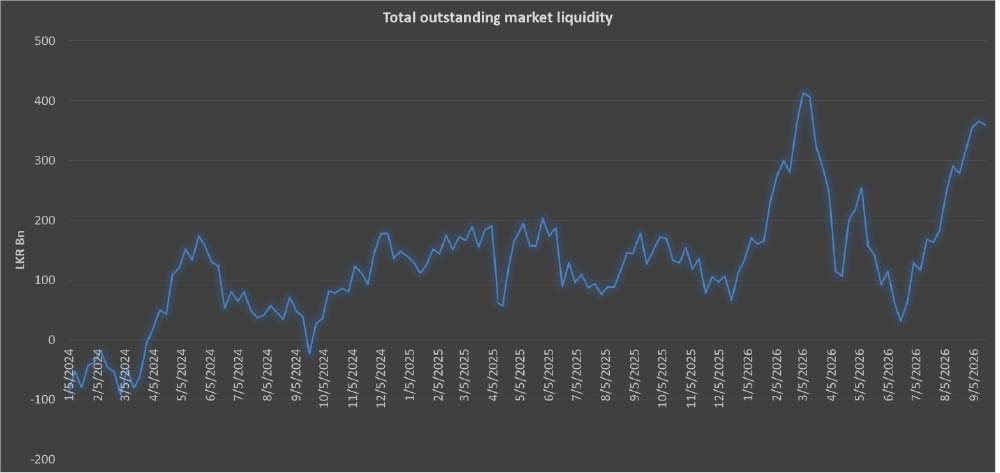
Money market liquidity surplus as at the week ending 18 September remained elevated and was recorded at Rs. 359.79 billion as against its previous weeks total outstanding figure of Rs. 366.11 billion.
The weighted average Call Money and Repo rates stood at 8.91% and 8.96%, respectively.
Furthermore, the rupee or the USD/LKR rate was seen depreciating, to close the week ending 18 September at Rs. 330.75/331.25 as against its previous week’s closing of Rs. 328.60/328.70. This was subsequent to trading within an intraweek high of Rs. 328.89 and a low of Rs. 332.60 intraweek.
The average daily USD/LKR traded volume over the first four trading days of the week stood at $ 48.45 million.
(References: Public Debt Management Office - Ministry of Finance, Central Bank of Sri Lanka, Bloomberg E-Bond Trading Platform, Money Broking Companies)