Tuesday Oct 06, 2026
Tuesday Oct 06, 2026
Monday, 5 October 2026 04:39 - - {{hitsCtrl.values.hits}}
By Wealth Trust Securities
 The secondary Bond market during the trading week ending 2 October started off with yields initially moving higher as the upward momentum from the previous week carried through. Sentiment was weighed down by elevated global Bond yields, a relatively hawkish global monetary policy backdrop (with the Australia choosing to hike rates) and renewed Middle East uncertainty.
However, the sentiment turned positive following the CBSL’s decision to maintain policy rates unchanged, triggering a strong relief which saw a sharp drop in yields. While part of the downward rally was subsequently retraced-particularly after the Treasury Bill auction outcome, buying interest remained evident at the higher yield levels.
Sentiment improved further as crude oil prices briefly dropped sharply intraweek. The CBSL’s reaffirmation of its 5% inflation target, together with signs of moderating private sector credit growth, also helped temper expectations of further near-term policy tightening.
Against this backdrop, yields eased back from their intraweek highs before consolidating towards the close of the week. Overall, the trading range reflected a market balancing of lingering external risks against improving domestic policy visibility and renewed demand at elevated yield levels. Activity and transaction volumes were seen at subdued levels with sporadic bouts of activity.
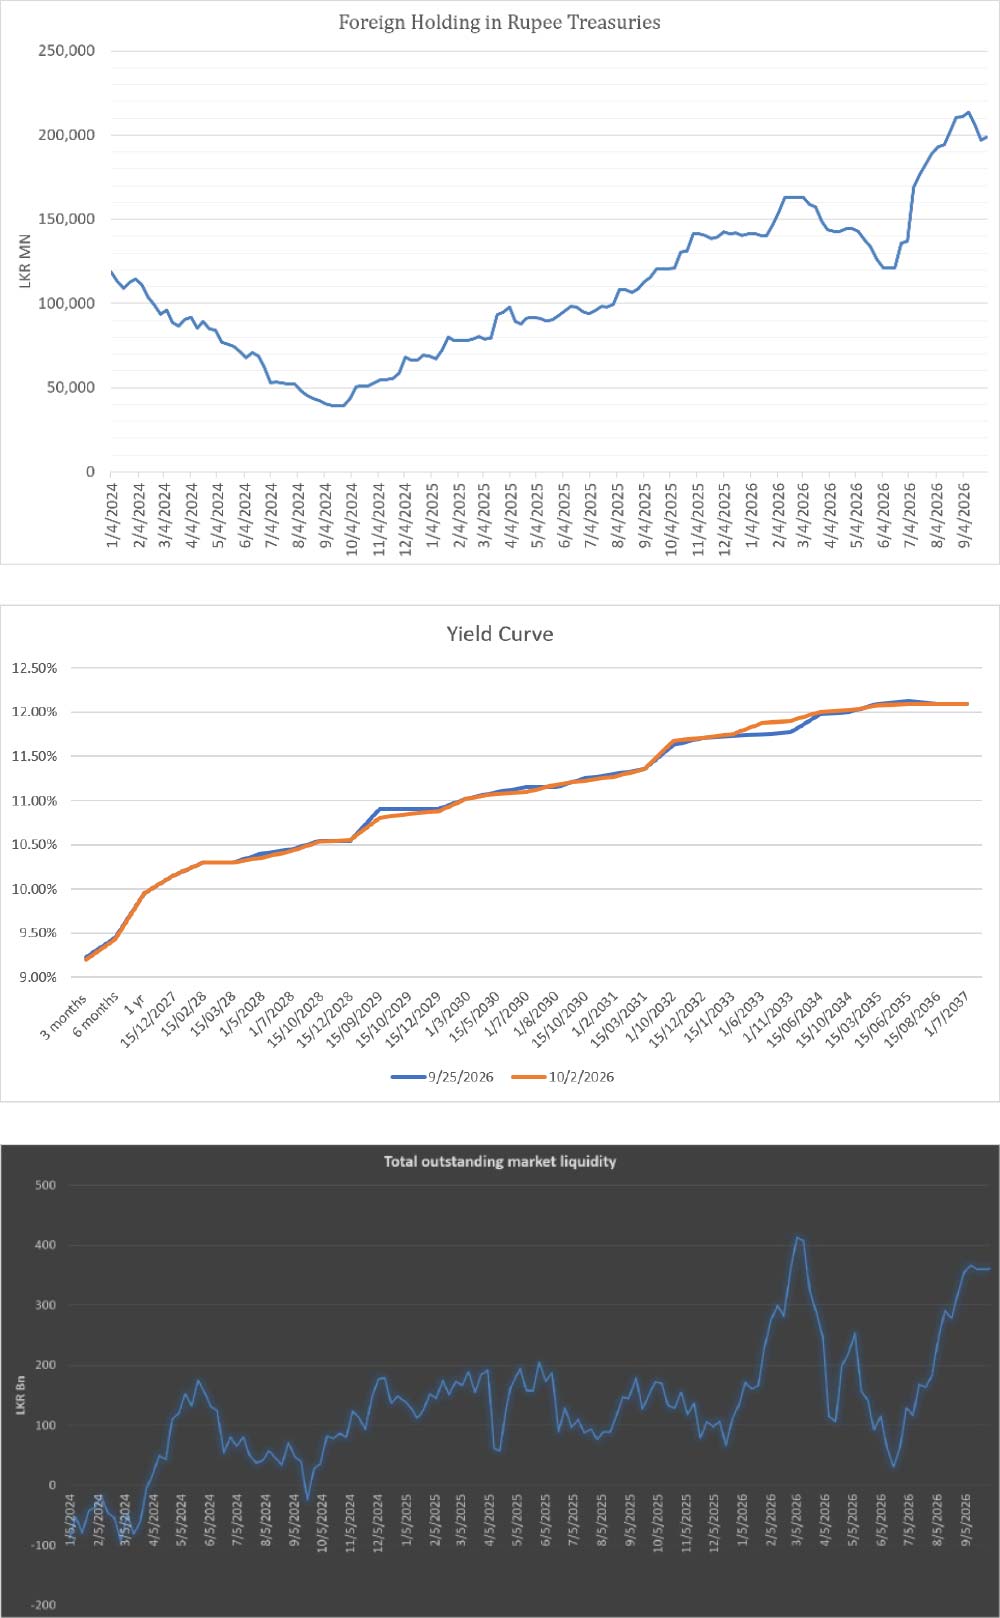
The 15.10.28 traded down the intraweek range of 10.55%-10.50%, while the 15.12.28 traded within the range of 10.65%-10.68%. The 15.12.29 traded at 10.85%.
The 2030 and 2031 tenors exhibited the V-Shape trading pattern during the week. The 01.08.30 initially traded up to an intraweek high of 11.28% before rallying sharply to a low of 11.00%, following which yields partially retraced to 11.17%. The 15.10.30 saw an even more pronounced move, rising to an intraweek high of 11.35% before dropping to a low of 11.05% and subsequently retracing to 11.20%. Similarly, the 01.02.31 traded up to an intraweek high of 11.40%, rallied to a low of 11.10% and subsequently moved back up towards 11.27%.
A similar pattern was observed on the 15.12.32, which initially traded as high as 11.80% before rallying to an intraweek low of 11.60% and partially retracing to 11.70%. The 15.01.33 traded down from an intraweek high of 11.85% to a low of 11.75%, while the 01.11.33 declined from an intraweek high of 11.95% to a low of 11.85%.
Further along the curve, the 15.06.34 traded within the intraweek range of 12.05%-11.90%, while the 15.09.34 traded between 11.95%-12.00%. The 15.10.34 rallied from an intraweek high of 12.10% to a low of 11.90% and retraced to 12.00%. The 15.03.35 and 15.06.35 traded at 12.15%.
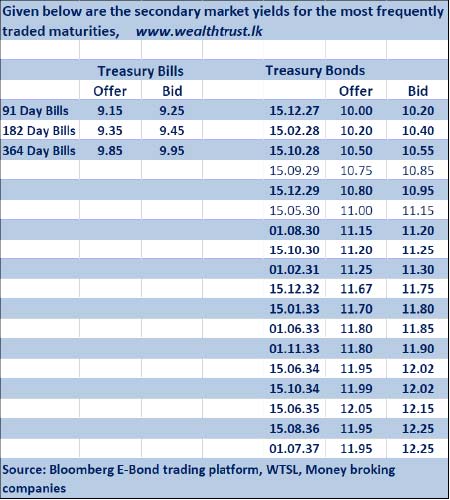
The Treasury Bill weighted average yields continued on an upward trajectory and increased across the board for the third consecutive week at the weekly auction held.
Accordingly, the 91-day yield rose by 5 basis points to 9.25%, while the 182-day and 364-day yields increased by 4 basis point and 2 basis points to 9.41% and 9.95%, respectively.
The Public Debt Management Office (PDMO) successfully raised the full Rs. 80 billion offered. The 91-day and 182-day tenors recorded acceptances above its target allocation, while the 364-day tenor fell short of its target.
Total bids received amounted to 2.51 times the overall offer.
In addition, subsequent to the weekly Treasury Bill auction conducted on 30th September, demand extended to the second phase. The second phase was heavily oversubscribed receiving bids amounting to Rs. 20.91 billion as against an offered amount of Rs 8.00 billion. Accordingly, the entire offered amount was raised leading to an aggregate subscription of Rs. 88.00 billion across both phases.
The Money market liquidity surplus as at the week ending 2 October was Rs. 360.11 billion as against its previous weeks total outstanding figure of Rs 370.92 billion- remaining elevated and holding above the Rs. 350 billion mark.
The weighted average Call Money and Repo rates stood at 8.99% and 9.04% respectively, up from their previous week’s levels of 8.96% and 9.00%, respectively.
Meanwhile, the foreign holdings of rupee-denominated Government securities recorded a net inflow following two consecutive weeks of outflows, amounting to Rs. 1.82 billion for the week ended 01 October. An increase of 1% week on week. Accordingly, the total foreign holdings of rupee Treasuries increased to Rs. 198.75 billion.
Forex market
The Rupee or the USD/LKR rate was seen holding broadly steady, to close the week ending 1 October at Rs 330.59/330.64 as against its previous week’s closing of Rs. 330.40/330.50. This was subsequent to trading within an intraweek high of Rs. 330.59 and a low of Rs. 331.17 intraweek.
The average daily USD/LKR traded volume over the first four trading days of the week stood at $ 107.42 million.
(References: Public Debt Management Office - Ministry of Finance, Central Bank of Sri Lanka, Bloomberg E-Bond Trading Platform, Money Broking Companies)