Thursday Nov 12, 2026
Thursday Nov 12, 2026
Thursday, 12 November 2026 00:26 - - {{hitsCtrl.values.hits}}
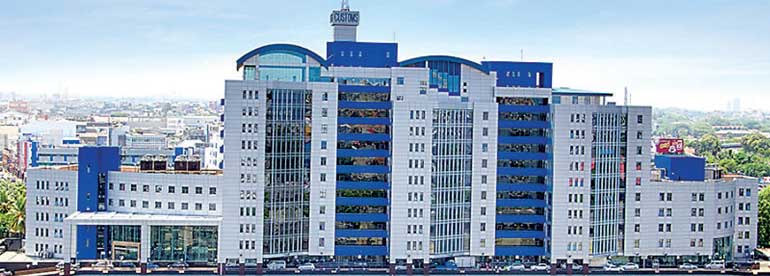
A power intended to uphold the rule of law should not be exercised to confer undue benefits on the very officers entrusted with enforcing it. Such a practice creates an inherent conflict of interest, undermines institutional integrity, and risks making unethical conduct and corruption widespread in exercising the discretionary powers by such public officers.
The legislative provision that paved the way for this alarming arrangement was introduced into the Sri Lanka Customs Ordinance through the Customs (Amendment) Act, No. 83 of 1988, under the then UNP Government. This was in the aftermath of the radical economic liberalisation policy introduced by President J. R. Jayewardene in 1977, which opened the country’s economy and significantly relaxed import controls.
The relevant provision, as introduced, reads as follows:
“153. The amount--
(1) of all forfeitures and penalties recovered under this Ordinance or under this Ordinance read with the provisions of any other written law; and
(2) of the proceeds of all such goods as may be disposed of by the Director-General under section 162 of this Ordinance, or under this Ordinance read with the provisions of any other written law,
shall be paid into the hands of such Director-General and shall (after deducting any expenses incurred) be paid and applied as follows : -
(a) one half to the Deputy Secretary to the Treasury, out of which sixty per centum shall be credited to the Consolidated Fund and the balance forty per centum to the Customs Officers Management and Compensation Fund (hereinafter in this Ordinance referred to as “ the Fund”) ; and
(b) the other half into a reward fund under the control of the Director-General for distribution, in accordance with a scheme to be approved by the Minister, among customs officers concerned and informers.”
The financial implications of this provision are particularly alarming. Out of the aggregate amount recovered through penalties and forfeitures imposed on errant importers, together with the proceeds realised from the disposal of seized goods, 30% goes to the Treasury while 70% goes to Customs officers and informers.
This allocation comprises:
n 30% to the Consolidated Fund: 60% of the first half of the recoveries. (153(2)(a)).
n 20% to the Customs Officers Management and Compensation Fund: 40% of the first half. (153(2)(a))
n 50% to the Reward Fund: the remaining half, to be distributed among the Customs officers concerned and informers under a scheme approved by the Minister. (153(2)(b))
It should be emphasised that informers, where applicable, receive only a negligible portion of the 50% allocated to the Reward Fund. The overwhelming share of this allocation is therefore intended for the benefit of Customs officers directly.
A legal power intended to punish Customs offences and protect public revenue should never be used to financially benefit the very officers responsible for enforcing the law. When the rewards given to these officers exceed the revenue retained by the State, it is not just a legal anomaly but a serious misuse of public funds and a threat to the integrity of law enforcement.
A request for information was submitted to Sri Lanka Customs on 19 October 2026 under the Right to Information Act, No. 12 of 2016, seeking details of the total amounts of penalties and forfeitures collected during the years 2023, 2024 and 2025, together with a breakdown of the amounts distributed among Customs officers and remitted to the Treasury.
The request also sought clarification as to whether the relevant distribution scheme had received the approval of the Minister in charge, as expressly required under Section 153(2)(b) of the Customs Ordinance. This is particularly important because it has been alleged that the scheme is implemented without obtaining the Minister’s approval, as required by law.
In its response dated 3 November 2026, SLC, despite its reputation for operational efficiency, surprisingly requested a further 21 working days to provide information that should ordinarily be readily available in its possession. Upon receipt of the requested information, a detailed article, if warranted, will be published, supported by relevant facts and figures to shed further light on this matter.
Performance-based incentives v. penalties-based rewards
There is nothing wrong with public officers, particularly those responsible for collecting and protecting Government revenue, receiving reasonable performance-based incentives. However, such incentives should be based on clear annual targets and an objective assessment of each officer’s performance under a transparent scheme applicable equally to all staff. The incentive scheme of the Inland Revenue Department is a good example of this legitimate approach to staff management.
However, such a penalty-based reward system can give rise to several serious adverse consequences that deserve urgent attention from both the Government and the public. It must be emphasised that the concern is not directed at the Customs officers as a whole. Many officers perform their duties honestly and diligently. Unfortunately, the questionable conduct of a few can tarnish the reputation of the entire service, undermine public confidence and bring discredit to the many dedicated officers who uphold the integrity of the institution.
1. Conflict of interest
A conflict of interest arises when a public officer’s personal or financial interests may influence, or appear to influence, the proper performance of official duties. Public officers are expected to make decisions solely in the public interest and in accordance with the law, without being influenced by the prospect of personal financial benefits.
For example, when Customs officers are entitled to receive financial rewards from penalties and forfeitures imposed on importers, they may develop an indirect personal interest in detecting more offences and imposing higher penalties. This creates a situation where the officers responsible for investigating violations and enforcing the law may also benefit financially from the very penalties they impose.
The fundamental problem is that those entrusted with enforcing the law should not have a personal financial interest in the outcome of their own enforcement actions. Law enforcement must be guided by justice, fairness and the protection of public revenue, not by the financial rewards that may arise from punishing those who violate the law.
2. Erosion of public confidence
The public expects public officials, especially revenue officials such as Customs officers to enforce the law fairly and impartially, without being influenced by personal financial benefits. Importers should not have to worry about whether enforcement decisions are made in the interest of the law or financial gain.
When honest importers face unnecessary difficulties, excessive penalties or unofficial demands to clear their goods, they may lose confidence in the system and even resort to unlawful practices. Ultimately, this discourages tax compliance, undermines public confidence and results in losses to State revenue.
3. Harassment and disproportionate enforcement
Not every Customs violation involves an attempt to evade duties or defraud the State. Some may arise from genuine mistakes, differences in interpretation, documentation errors or technical non-compliance. Such cases should ordinarily be dealt with through additional duties, commonly known as Additional Estimates (AEs), where applicable, rather than punitive penalties and forfeitures that generate financial rewards for enforcement officers.
It is alleged that certain Customs officers take excessive personal interest in investigating and prosecuting importers, sometimes going beyond what is reasonably necessary to enforce the law. This raises concerns that the prospect of personal financial rewards may influence enforcement decisions, shifting the focus from justice and revenue protection to personal financial gain.
4. Compromising professional integrity
Customs officers should measure their performance by the quality of their investigations, accuracy of their decisions, fairness of enforcement and contribution to national revenue.
However, when financial rewards are linked to penalties, the focus may gradually shift from professional performance to the amount of money generated through enforcement activities. This can undermine the professional ethics and integrity expected of public officers.
5. Weakening the rule of law
The rule of law requires that laws be enforced fairly, consistently and without personal interests influencing official decisions.
An enforcement system should not encourage officers to view every violation as an opportunity to generate financial benefits. Penalties must be imposed according to the law and the seriousness of the offence, not according to the financial rewards they may produce. Otherwise, the distinction between enforcing the law and exploiting the law becomes dangerously dim.
6. Institutionalising a conflict of interest
Perhaps the most serious consequence is that such an arrangement can make a conflict of interest part of the institutional structure itself.
Normally, conflicts of interest are matters to be prevented through ethical standards, administrative controls and disciplinary procedures. But when legislation itself creates a financial entitlement for the officers responsible for imposing penalties, the problem becomes institutional rather than merely individual.
It may also become difficult to ensure independent analysis of enforcement decisions when the enforcing institution itself stands to benefit financially from those decisions.
Responsibility of the Government
Although the NPP Government has made considerable progress in combating political corruption, it has been less successful in eliminating bureaucratic corruption within the public service, particularly among revenue agencies that are entrusted with wide discretionary powers in the discharge of their official duties.
Revenue-collecting institutions such as Sri Lanka Customs fall within the direct purview of President Anura Kumara Dissanayake, whose long-standing and vocal opposition to corruption has been a defining feature of his political career. Furthermore, the fact that his Secretary previously served as a senior officer of Sri Lanka Customs makes the need for meaningful intervention even more compelling.
It is therefore the solemn responsibility of this Government to take decisive action to eradicate corruption itself and its potential avenues within revenue-collecting institutions and restore public confidence in their integrity. This responsibility must not be compromised, weakened or diluted by resistance from vested interests, potentially corrupt elements within trade unions, or opportunistic opposition political forces seeking to obstruct genuine institutional reforms. The Government must demonstrate the political courage and determination to pursue these reforms in the public interest, particularly when no other foreseeable political force appears capable of undertaking such bold and necessary measures for the benefit of the nation and its people.
The fight against corruption cannot end with politicians; it must extend to every public institution and every public official entrusted with State power.
(The author is a Retired Deputy Commissioner General, Inland Revenue Department and could be reached via email [email protected])