Tuesday Sep 15, 2026
Tuesday Sep 15, 2026
Tuesday, 15 September 2026 03:39 - - {{hitsCtrl.values.hits}}
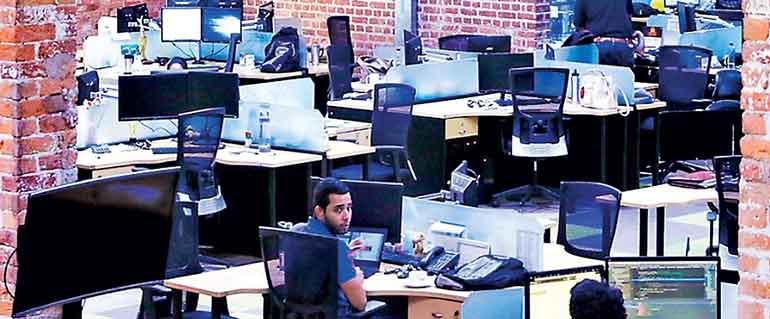
A BPO office in Sri Lanka
 For nearly three decades, Sri Lanka’s service exports enjoyed a significant advantage by being largely exempt from income tax. A software engineer in Colombo working for a client in London, a graphic designer invoicing a customer in Sydney, or a business process outsourcing firm providing services to an insurer in New York could earn foreign income without facing tax in Sri Lanka, provided the earnings were received through the banking system. This exemption was not simply a tax concession. It was a deliberate policy choice aimed at encouraging the growth of Sri Lanka’s export-oriented services sector, and it played an important role in building the country’s IT-BPM industry. Today, the sector employs over 144,000 people and, together with professional services, freelancing and other knowledge-based exports, generates well over three billion dollars annually. From April 2025, however, this long-standing exemption was removed. Service export income is now subject to tax of up to 15%, while the Government has also strengthened mechanisms for identifying and collecting tax from those earning such income. The policy may increase Government revenue in the short term, but it also raises a more fundamental question: whether taxing a sector that was deliberately nurtured through years of tax incentives could ultimately weaken the very export base the Government now seeks to tax.
As part of its post-default adjustment program, the IMF proposed taxing service export income at rates of up to 30%, effectively treating it in the same manner as ordinary domestic corporate income. Sri Lankan negotiators subsequently secured a lower rate of 15%. For the first time in the country’s modern economic history, income earned by selling Sri Lankan expertise to the rest of the world is being treated as a target for revenue collection rather than a strategic asset to be protected
A tax born of desperation, not design
It is worth being honest about how this change came about. It was not the result of a broader national discussion on the future of Sri Lanka’s export or industrial strategy, but rather a response to the country’s fiscal crisis. As part of its post-default adjustment program, the IMF proposed taxing service export income at rates of up to 30%, effectively treating it in the same manner as ordinary domestic corporate income. Sri Lankan negotiators subsequently secured a lower rate of 15%. In December 2024, President Anura Kumara Dissanayake presented this reduced rate as a concession to the industry, with Export Development Board Chief Executive Mangala Wijesinghe describing it as a “significant push” for the sector. That framing obscures the more basic fact. For the first time in the country’s modern economic history, income earned by selling Sri Lankan expertise to the rest of the world is being treated as a target for revenue collection rather than a strategic asset to be protected.
The mechanics of the new regime are important. Under the Inland Revenue (Amendment) Act, which took effect on 1 April 2025, individual freelancers and professionals are subject to a graduated tax rate, with the first Rs. 150,000 exempt, followed by a 6% rate that increases progressively to a maximum of 15%, provided the income is remitted through a Sri Lankan bank. Companies, meanwhile, are subject to a flat 15% tax on service export profits, subject to the same condition. Income that is not remitted through the domestic banking system, or that is booked in ways the Inland Revenue Department cannot verify, is liable to be taxed at ordinary rates of up to 30% for companies and 36% for individuals. On paper, this looks like a modest, business-friendly compromise. In practice, it introduces exactly the kind of complexity and unpredictability that footloose, digitally delivered services cannot tolerate.
The problem nobody has solved: You cannot tax what you cannot see
This is the crux of the matter, and it is the one policymakers have been least willing to confront. Sri Lanka’s service exports are not a handful of large, easily audited companies shipping containers through a port. They are a sprawling, largely informal universe of freelancers, sole proprietors, small studios and remote contractors who invoice foreign clients directly through platforms like Upwork, Fiverr, Payoneer and direct wire transfer. Even the Export Development Board’s own chairman has acknowledged that official figures, $3.47 billion in service exports last year, almost certainly understate reality, given that data from informal, non-registered service providers in the sector is difficult to collect. The Central Bank of Sri Lanka (CBSL) has responded by expanding its International Transactions Reporting System, while the Inland Revenue Department has been granted additional powers, through a Gazette issued in May 2024, to examine bank transactions and other financial activity. Authorities have also pointed to the use of automatic international information-sharing mechanisms and have made clear that efforts to identify and trace undeclared income are increasingly likely to be identified and traced.
Under the Inland Revenue (Amendment) Act, individual freelancers and professionals are subject to a graduated tax rate, with the first Rs. 150,000 exempt, followed by a 6% rate that increases progressively to a maximum of 15%, provided the income is remitted through a Sri Lankan bank. Companies, meanwhile, are subject to a flat 15% tax on service export profits, subject to the same condition. Income that is not remitted through the domestic banking system, or that is booked in ways the Inland Revenue Department cannot verify, is liable to be taxed at ordinary rates of up to 30% for companies and 36% for individuals. On paper, this looks like a modest, business-friendly compromise. In practice, it introduces exactly the kind of complexity and unpredictability that footloose, digitally delivered services cannot tolerate
All of this, however, assumes that the income remains within a system that the state can effectively monitor. That assumption may not hold. Digital labour is one of the most mobile forms of economic activity, allowing individuals to operate across borders without physically relocating. A Sri Lankan freelancer concerned about the tax burden on service income could, for example, establish a business through Estonia’s e-residency program, use a fintech platform outside the domestic banking system, or receive payments into a foreign-currency account that does not pass through a Sri Lankan bank. None of this requires relocating, it only requires a laptop and an internet connection. Every one of these workarounds illustrates a phenomenon that tax economists have long recognised, when the cost of remaining visible and compliant exceeds the cost of going invisible, revenue authorities do not gain a new tax base, they risk losing the one they already have. If there is a case of under invoicing when exporting goods, it could be identified at some stage by the Customs, but an under invoicing in service exports cannot be detected. A tax that is difficult to monitor is also, almost by definition, a tax that becomes easier to avoid.
Each of these workarounds illustrates a phenomenon long recognised by tax economists, when the costs associated with remaining visible and compliant exceed those of operating outside the formal system, revenue authorities do not necessarily broaden the tax base; they risk losing taxpayers who were previously within it. A tax that is difficult to monitor and enforce is, by its very nature, also more susceptible to avoidance.
Sri Lanka’s service exports are not a handful of large, easily audited companies shipping containers through a port. They are a sprawling, largely informal universe of freelancers, sole proprietors, small studios and remote contractors who invoice foreign clients directly through platforms like Upwork, Fiverr, Payoneer and direct wire transfer. Even the Export Development Board’s own chairman has acknowledged that official figures, $3.47 billion in service exports last year, almost certainly understate reality, given that data from informal, non-registered service providers in the sector is difficult to collect. All of this, however, assumes that the income remains within a system that the state can effectively monitor. That assumption may not hold
Who actually pays this
The businesses least able to absorb a sudden 15% increase in their tax burden are not necessarily the large BPM operators with diversified client bases and greater negotiating leverage. Even these larger firms, however, remain exposed, as global outsourcing contracts are often negotiated and priced years in advance, making it difficult to pass an unexpected tax increase on to clients. The greatest pressure is likely to fall on smaller IT consultancies, boutique design studios, accounting and legal process outsourcing firms, and individual professionals who operate on relatively narrow margins while competing with providers in India, Vietnam, the Philippines and Eastern Europe. Sri Lanka’s IT and BPM industry bodies, including SLASSCOM, FITIS, the British Computer Society and the Computer Society of Sri Lanka, jointly warned the Government in 2024 that the new tax structure could place Sri Lanka among the highest tax slabs in the region. They also cautioned that skilled professionals, already facing income tax rates of up to 36%, could find relocation increasingly attractive, while businesses considering future expansion could choose competing jurisdictions instead. This is not merely a theoretical concern. Unlike a garment factory or a tea estate, an IT services company can relocate its delivery operations to Bangalore, Ho Chi Minh City or Manila with comparatively little physical investment, requiring little more than a lease agreement and a hiring plan, rather than ships, factories or substantial fixed capital left behind.
What the success stories actually did
The countries Sri Lanka now competes with for this business did not achieve their position by imposing higher taxes on service exports. In fact, their approach has been largely the opposite.
The Philippines provides perhaps the clearest example. In 1995, the Government established the Philippine Economic Zone Authority (PEZA), offering tax holidays and a streamlined regulatory framework to companies operating within designated economic zones. This policy helped transform the country’s existing advantages, particularly widespread English proficiency and a large young workforce, into the foundations of a globally competitive business process outsourcing industry. In 2010, the Philippine BPO sector employed approximately 525,000 people and generated $8.9 billion in export revenue. By 2025, employment had risen to nearly 1.9 million, while the sector generated an estimated $40 billion in export revenue and contributed more than 8% of national GDP. Over time, the industry has also moved beyond traditional call centre operations into higher value digital and knowledge based services. Industry groups now project that the workforce could reach 2.5 million by 2028.
Digital labour is one of the most mobile forms of economic activity, allowing individuals to operate across borders without physically relocating. A Sri Lankan freelancer concerned about the tax burden on service income could, for example, establish a business through Estonia’s e-residency program, use a fintech platform outside the domestic banking system, or receive payments into a foreign-currency account that does not pass through a Sri Lankan bank. None of this requires relocating, it only requires a laptop and an internet connection
India presents a similar example, but on a much larger scale. For decades, India used export oriented incentives to support its IT and business services sector. These included tax holidays for units registered under the Software Technology Parks of India scheme and, later, Special Economic Zones. These measures helped develop an industry that barely existed before economic liberalisation in 1991. The industry is now projected to generate $283 billion in revenue in 2024–25, while the Government has set a target of $450 billion in services exports and Goldman Sachs projects that India could reach $800 billion in global services exports by 2030. India did not reach this position by treating software exporters as a convenient source of additional tax revenue once they became profitable. Instead, it protected their competitiveness long enough for the industry to develop the scale and global presence that would eventually make India’s position in the international market, rather than tax incentives, its greatest advantage.
Ireland offers a third model, particularly at the higher-value end of the services sector. For decades, its 12.5% corporate tax rate helped establish Ireland as a preferred European base for companies such as Google, Meta, Microsoft, Apple and Pfizer, as well as numerous other providers of digital and professional services. The rate is now 15% for the largest multinational enterprises under the OECD’s global minimum tax framework, but it remains relatively low compared with those of many competing jurisdictions. What was once criticised as a concession that could erode Government revenue instead became a major source of income for the Irish state. The experience suggests that a competitive tax rate can broaden the underlying tax base by attracting greater levels of investment and economic activity, rather than relying on higher rates imposed on a narrower base.
The lesson across all three examples is the same, and it is not that services should never be taxed. Ireland taxes service income, as have India and the Philippines at various stages of their development. The more important lesson is one of sequencing and credibility, build the tax base, protect it while the industry remains mobile and price sensitive, and introduce taxation only at a level the industry can absorb without being driven to relocate. Just as importantly, such changes should be introduced predictably and through meaningful consultation with the industry, rather than being presented as a fait accompli.
The businesses least able to absorb a sudden 15% increase in their tax burden are not necessarily the large BPM operators with diversified client bases and greater negotiating leverage. Even these larger firms, however, remain exposed. The greatest pressure is likely to fall on smaller IT consultancies, boutique design studios, accounting and legal process outsourcing firms, and individual professionals who operate on relatively narrow margins while competing with providers in India, Vietnam, the Philippines and Eastern Europe
What Sri Lanka needs to do differently
None of this means that Sri Lanka should abandon the idea of taxing service export income indefinitely. A Government facing fiscal constraints cannot reasonably be expected to leave a multi-billion-dollar sector permanently outside the tax base, and there is a legitimate argument that a modest, well-designed levy may be fairer than an indefinite blanket exemption, particularly when merchandise exporters continue to face a 30% tax rate, a point the National Chamber of Exporters has rightly emphasised. However, fairness in principle does not excuse poor policy design in practice, and on that count, the current approach falls short in at least four areas that require attention.
First, phase the tax in gradually. A tax introduced with only a few months’ notice, particularly in an industry that the Government itself has identified for growth to $11 billion by 2030, risks triggering precisely the kinds of reactions that could undermine the revenue it is intended to generate, including deferred investment, accelerated emigration and informal workarounds. A multi-year transition period, announced well in advance, would give businesses time to adjust their pricing and financial arrangements, while reducing the incentive for skilled workers to leave or move their activities outside the formal system.
Sri Lanka’s IT and BPM industry bodies jointly warned the Government in 2024 that the new tax structure could place Sri Lanka among the highest tax slabs in the region. They also cautioned that skilled professionals, already facing income tax rates of up to 36%, could find relocation increasingly attractive, while businesses considering future expansion could choose competing jurisdictions instead
Second, consult before legislating, not after. SLASSCOM and other industry bodies were left to respond to a policy that had already been formulated and gazetted, rather than being given a meaningful opportunity to shape it. An industry as mobile and internationally competitive as this one should be treated as a partner in designing tax policy, rather than simply as a subject of it.
Third, pair taxation with incentives for growth. Training and research and development tax credits, accelerated depreciation for technology infrastructure, and streamlined incentives for firms that reinvest profits domestically would allow Sri Lanka to generate meaningful revenue from mature, high margin operators while continuing to reward the investment and growth that the country seeks to encourage.
Fourth, improve measurement before tightening enforcement. Expanding surveillance of bank transactions is a poor substitute for developing an accurate and credible register of the freelancers and micro exporters who make up an unknown but clearly substantial share of the sector. A simplified, low friction registration and payment system, perhaps based on a flat and easily administered levy rather than a punitive marginal rate, would be more likely to bring a larger number of taxpayers into the formal system and generate sustainable revenue than an enforcement apparatus focused on pursuing a workforce that can readily route its income around the system.
The countries Sri Lanka now competes with for this business did not achieve their position by imposing higher taxes on service exports. In fact, their approach has been largely the opposite. The lesson across all international examples is the same, and it is not that services should never be taxed. The more important lesson is one of sequencing and credibility, build the tax base, protect it while the industry remains mobile and price sensitive, and introduce taxation only at a level the industry can absorb without being driven to relocate
Sri Lanka’s service exporters are, in a very real sense, among the country’s most portable economic assets, and also among its most fragile. They do not require ports, plantations or power grids. They require a laptop, a client and a reason to stay. At present, the tax system is giving them one fewer reason than it once did.
If Colombo wants to achieve the $11 billion services export target it has set for itself, the choice is not between taxing the sector and leaving it untaxed. The choice is between designing a tax system within which the industry can continue to grow, and one that encourages it to quietly grow around the system instead.
(The author is a President’s Counsel and a Member of Parliament)