Monday Sep 28, 2026
Monday Sep 28, 2026
Monday, 28 September 2026 04:08 - - {{hitsCtrl.values.hits}}
 The Central Bank has issued continuous public warnings about the extreme dangers of these pyramid schemes, but it appears the message has failed to reach the wider public. The ultimate cause of this failure is clear: a wave of intense financial greed has completely overcome the public’s basic ability to assess everyday investment risks
 Charge against CBSL
A disturbing audio clip has been circulating widely on various social media platforms in Sri Lanka. In the recording, an over-bearing and aggressive male speaker is heard talking to a lady purported to be a Central Bank of Sri Lanka (CBSL) officer.
The man launches a bitter attack on the Central Bank, accusing it of destroying his family’s livelihood. He loudly blames the bank for throwing his wife and children onto the street by cutting off a regular, lucrative monthly income. This income, he explains, had been flowing continuously from a profit-sharing investment in a modern agricultural project. The disruption occurred because the bank accounts of the agricultural business were abruptly frozen.
The lady officer responds with exemplary politeness, calmly explaining that the freezing of the accounts was not an arbitrary action by the Central Bank, but a legal directive issued by the courts. She gently reminds him that the bank has no power to override it now without going back to the courts.
War hero’s threat
Instead of accepting this institutional reality, the caller becomes increasingly infuriated by her repeated, identical explanations. He grows angry and dramatically reminds her of his past sacrifices. He boasts that he was a war hero—one of the brave individuals who saved Sri Lanka from brutal terrorist attacks while Central Bank officials were allegedly sleeping safely in their offices. He goes so far as to threaten the institution, warning that he could easily mobilise his fellow war heroes to march upon the Central Bank, surround the premises, and physically block the exit of all staff members from the building.
The lady officer maintains her professional composure, politely reiterating that her hands are tied due to the prevailing court order. This triggers an even more explosive response. The caller descends into a barrage of words targeting the top bank management, painting them as insensitive bureaucrats oblivious to the predicament of the people. The audio clip cuts off at that intense moment, leaving listeners with a stark example of growing public anger, deep misunderstanding, and emotional manipulation.
CBSL too was a victim
The caller’s aggressive rhetoric explicitly referenced Sri Lanka’s devastating thirty-year conflict with the Liberation Tigers of Tamil Eelam (LTTE), who fought an armed campaign to establish a separate State in the north and east of the island. While the caller claimed that Central Bank officials were merely sleeping during the conflict, the historical reality is that the bank itself was a tragic victim of that very war.
In January 1996, the bank premises in Colombo were hit by a heinous and devastating terrorist attack. A lorry packed with powerful explosives tried to force its way into the building. It was stopped only because of a sturdy iron barrier that prevented the vehicle from being driven directly onto the porch of the main building. The resulting explosion was massive, killing 41 dedicated bank officers and injuring over 1,200 employees. Many staff members were permanently blinded or disabled, yet the institution resumed operations almost immediately to keep the national economy alive.
|
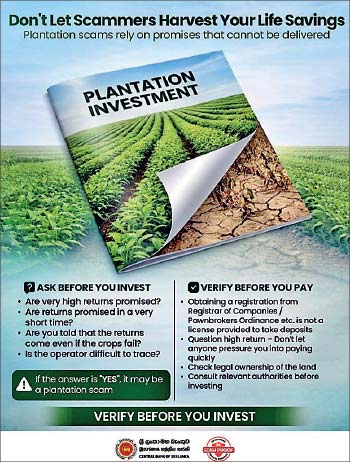
A CBSL public warning notice about shady investment schemes
|
War behind frontlines
Furthermore, the self-proclaimed war hero in the audio clip seems completely unaware that when the military conflict reached its most intense phase in 2008, a second, equally critical war was being fought directly behind the frontlines. While soldiers were fighting bravely in the field, the Central Bank was fighting a silent, desperate battle to manage the nation’s collapsing finances.
If the Central Bank had failed in that financial war, the armed forces would have lost the conflict on the ground without firing a single shot. The challenge at the time was securing the massive amounts of foreign exchange required by the military forces to purchase vital weaponry from overseas suppliers.
These suppliers had agreed to supply the necessary military equipment, but strictly on a short-term, three-month suppliers’ credit facility. The defence authorities placed their orders and requested the State-owned Bank of Ceylon (BOC) to open the necessary Letters of Credit (LCs). When these LCs matured after ninety days, the Bank of Ceylon was legally obligated to honour the payments in foreign currency.
Unseen war by CB
However, Sri Lanka’s foreign exchange reserves had run critically low, creating a terrifying national security crisis. The Central Bank was tasked with finding the money to save the military effort from immediate collapse. The Governor at the time, Ajith Nivard Cabraal, had to deploy desperate measures to secure foreign exchange and meet these heavy international obligations. This included sending several official teams to various countries across the globe to solicit urgent financial support and investment from the Sri Lankan diaspora.
It was a time of absolute desperation behind closed doors. Had the Central Bank failed to provide the necessary foreign exchange during those critical months, the flow of essential weapons, ammunition, and spare parts to the armed forces would have completely dried up. Sri Lankan soldiers on the frontlines would have been left as sitting ducks for devastating terrorist attacks.
Therefore, the ultimate victory in the war was never the result of a single group or a single man’s efforts. There were thousands of unsung heroes working tirelessly behind the scenes in the financial sector, ensuring that the visible heroes fighting on the ground had the tools to win.
Strange profit-sharing
The underlying issue that triggered the viral phone call is an investment scheme that has trapped thousands of citizens across the country. In recent years, a group of crafty entrepreneurs launched various agricultural investment projects, acquiring lands in outstations to cultivate fast-growing, high-yield short-term crops, such as pineapples.
They heavily promoted these projects through sophisticated marketing campaigns, offering an irresistible “profit-sharing” investment opportunity to the public. These entrepreneurs promised astronomical returns, often guaranteeing a profit-sharing rate of around 40% per annum. To make the trap even more appealing, they paid these super profits into the bank accounts of investors on a strict monthly basis from the very first day of investment. Crucially, this meant that profit shares were being distributed to investors long before the crops were even grown, let alone harvested or sold in the market.
Irresistible temptation
During a period when formal commercial banks were offering standard fixed deposit rates of around 8%, and risk-free Government securities were yielding roughly 9%, an investment offering a guaranteed 40% annual return was bound to be an irresistible temptation.
From a purely human perspective, ordinary citizens who opted for this scheme cannot be entirely blamed for wanting to improve their financial position. However, their critical error lay in their total failure to ask basic, logical questions about how these businesses could possibly sustain such high returns. The normal rate of return in agricultural ventures is notoriously low, due to uncontrollable natural or sometimes man-made hazards. Then, how could anyone guarantee a high fixed return amidst them?
Robbing Peter to pay Paul
More importantly, it boiled down to paying profits before a single crop had been harvested. The answer is simple and mathematically absolute: the early investors were not being paid from genuine agricultural revenue, but from the cash inflows brought in by subsequent waves of new investors. This is the classic, textbook definition of a fraudulent pyramid or Ponzi scheme.
So long as there was a continuous, growing influx of new people handing over their savings, the operators could use that fresh inflow to pay the promised monthly “profits” to the earlier participants. However, the moment the pool inevitably began to dry up, the entire structure was destined to collapse under its own weight. The income flow to the investors would have stopped completely on its own, even without a formal court order to freeze the company’s bank accounts.
The Central Bank has issued continuous public warnings about the extreme dangers of these pyramid schemes, but it appears the message has failed to reach the wider public. The ultimate cause of this failure is clear: a wave of intense financial greed has completely overcome the public’s basic ability to assess everyday investment risks.
Dropping guard amid economic hardships
This raises a profound socio-economic question: why are people so easily driven by blatant greed in a country that proudly boasts an official adult literacy rate of around 90%? The blame must be placed squarely on the country’s rapidly declining economic conditions.
When a nation passes through a severe, unprecedented economic crisis, the daily cost of living skyrockets while real household incomes remain completely stagnant or decline. As regular economic opportunities shrink and businesses close, individuals find themselves under intense financial pressure.
Furthermore, citizens at all income levels are burdened by heavy direct and indirect taxes, as a desperate Government tries to increase its State revenue by any means. The cost of daily essentials increases even further due to the sharp collapse of the exchange rate.
Super profit offers
All these harsh economic hazards combine to create an environment of desperation, driving ordinary people to take wild, irrational risks on super-profit offers just to keep their heads above water. This historical pattern is visible in every country that has experienced a sudden surge in fraudulent pyramid schemes during times of financial distress.
The situation perfectly mirrors a popular Sinhala saying: “A hungry dog does not care about the crushing attack on its head coming from a club from above, when it is offered a juicy bone from below.” In exactly the same manner, deteriorating economic conditions and the daily struggle for survival force individuals to completely abandon their normal guard, ignore obvious warning signs, and blindly chase unrealistic financial rewards. People who are unable to assess the risks faced by them are really poor people, irrespective of their educational levels, professional positions or social statuses.
Risk-blindness
Accordingly, history shows that it is very often individuals with high incomes, better education, and prominent social status who fail most spectacularly to assess these basic financial risks. They allow greed and overconfidence to blind their analytical faculties.
When a society becomes abundant with intellectually vulnerable, risk-blind individuals, crafty financial schemers and fraudulent entrepreneurs will always succeed in exploiting them. The Central Bank can enforce regulations and freeze fraudulent accounts through the courts, but it possesses no medicine that can cure inherent human greed. The responsibility for financial survival ultimately rests with the individual citizen.
Preventive justice
It must be explicitly understood that the recent freezing of bank accounts was executed by the courts strictly as a vital, precautionary measure.
The rationale behind this judicial intervention is preventative justice. If a business operating as a suspected pyramid scheme is allowed to carry on its operations without restriction, it will inevitably draw in fresh layers of unsuspecting citizens, creating an ever-expanding pool of financial victims.
The clear desire and duty of the court have been to protect these vulnerable members of the public from falling into a laid-down trap. This freezing order is by no means a permanent condemnation; it is an interim legal pause. Once the formal court case is fully concluded, the judicial system will readily permit the business to resume its operations, provided it is conclusively proved that the enterprise is a legitimate commercial entity and not a fraudulent pyramid structure.
I have come across well-dressed young men and women operating in the car parks of supermarkets, coaxing shoppers to go for these investments. A primary ploy they employ is playing upon a deep-seated fear harboured by many in the middle class: the burden of paying high income taxes. To bypass this fear, the promoters actively encourage investors to split their large capital into smaller, separate amounts that fall comfortably below the minimum legal threshold for tax registration. It is precisely due to this tax-evasion tactic that so many desperate investors have spread their family savings across the separate names of their wives, children, elderly parents, and in-laws
Burden of proof
Under the law, the legal burden rests upon two opposing sides. It is the responsibility of the Central Bank regulators to present robust evidence in court to prove that the business model is inherently fraudulent. Conversely, the operators of the business are given a fair, transparent opportunity to present acceptable evidence demonstrating that their enterprise functions on legitimate agricultural profits rather than subsequent investor capital.
At this stage, the matter rests entirely in the hands of the courts of law to weigh the evidence and deliver an impartial judgment. If the judicial system finds that the enterprise is not a pyramid scheme, as claimed by the Central Bank, the legal restrictions will be dismantled, and the investors can rightfully continue to receive their high monthly profit returns.
Courts may listen
Furthermore, the legal framework is not entirely insensitive to the practicalities of ongoing physical operations. If the freezing of the bank accounts has directly disrupted the maintenance of already established agricultural cultivations due to a sudden lack of working capital, the operators are not completely helpless.
The business always retains the right to plead its case before the courts, formally requesting the structured withdrawal of essential funds from the frozen accounts to meet operational costs, such as paying field labourers or buying fertiliser. Historically, the courts of law have proven highly sensitive to these practical realities, frequently making suitable and fair allowances to ensure essential, ongoing agricultural expenses are met while the broader legal issue is being litigated.
Weakness in CBSL communications
While the legal process runs its course, the immediate plight of the current investors remains undeniably pathetic. However, the reality of the situation reveals that the Central Bank’s repeated warnings and educational messages have simply not gone into their heads sufficiently.
This disconnection points to a major, undeniable weakness in the Central Bank’s contemporary public communication strategy. Relying heavily on dry, macro-level marketing, formal press releases, and complex technical jargon has failed to shield ordinary citizens from financial sharks. If the Central Bank hopes to win this battle, it must completely overhaul its approach and adopt equally aggressive, modern, and effective communication methods to spread its messages widely.
Need for change
First, the monetary authority must heavily leverage social media platforms, utilising engaging, simple visual formats and short video content that can go viral just as quickly as the deceptive claims of the fraudulent entrepreneurs.
Second, the bank should implement localised visual anchors by placing prominent, bold billboards at supermarkets or shops and street junctions. These billboards must serve as a stark, everyday reminder to the gullible public that accepting unrealistic, ultra-high profit offers will lead to an inevitable and devastating financial loss.
Advice to CBSL: fight fire with fire
This localised approach is crucial because it directly counters the exact methods used by the promoters of these fraudulent schemes. The operators of pyramid ventures do not market their products through legal media; they operate directly on the ground.
I have come across well-dressed young men and women operating in the car parks of supermarkets, coaxing shoppers to go for these investments. A primary ploy they employ is playing upon a deep-seated fear harboured by many in the middle class: the burden of paying high income taxes.
To bypass this fear, the promoters actively encourage investors to split their large capital into smaller, separate amounts that fall comfortably below the minimum legal threshold for tax registration. It is precisely due to this tax-evasion tactic that so many desperate investors have spread their family savings across the separate names of their wives, children, elderly parents, and in-laws.
To successfully counter these crafty, micro-targeted tactics, the Central Bank must fight fire with fire and adopt similar information-disseminating strategies on the ground. I suggest they mobilise advanced-level economics students to act as public awareness ambassadors. They can do the counterpropaganda in car parks or by visiting houses.
Without such innovative propaganda tactics, people will fall into the traps laid by schemers, and the Central Bank will continue to get blamed for doing its duty properly after the event.
(The writer, a former Deputy Governor of the Central Bank of Sri Lanka, can be reached at [email protected])