Saturday Oct 31, 2026
Saturday Oct 31, 2026
Saturday, 31 October 2026 00:00 - - {{hitsCtrl.values.hits}}

As the Maldives tightens its grip on tourism dollars, Sri Lanka has an opportunity to position itself as the preferred destination for the next generation of resort investments, international hotel brands and hospitality capital
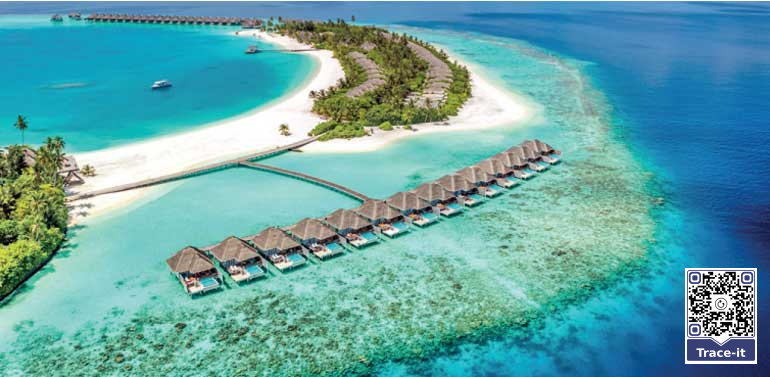
 There is a revealing incongruity at the heart of the Maldives’ latest foreign-exchange policy. A country whose economic model depends overwhelmingly on attracting foreign visitors and earning hard currency is tightening its grip on the dollars generated by its tourism industry. The decision to require Category A tourism establishments to convert 40 per cent of their monthly gross foreign-currency sales, effective from September 2026, comes amid renewed pressure on the country’s foreign-exchange position.
The Maldives Monetary Authority’s August figures showed official reserve assets rising marginally to $ 643.8 million, while usable reserves fell 9.6 per cent to $ 200.6 million. The central bank attributed the decline to foreign-currency sales exceeding inflows during the month.
The timing matters. This is not an isolated regulatory adjustment but a broader attempt to draw tourism earnings into the formal banking system, strengthen domestic foreign-exchange liquidity and reduce pressure on the currency market. President Mohamed Muizzu ratified the First Amendment to the Foreign Currency Act on 31 August, with the amendments taking effect on 1 September. Category A establishments must now convert 40 per cent of monthly gross foreign-currency sales through an MMA-licensed bank, replacing the previous option of converting $500 per tourist.
But the consequences extend beyond monetary management. They raise a question for the Indian Ocean tourism market, what happens when a government requires the businesses generating foreign currency to surrender a larger share of their earnings, while those same businesses depend on dollars to operate?
For Sri Lanka, the answer could influence the next generation of resort developments, international hotel partnerships and investment decisions.
A tighter grip on tourism dollars
The amended framework compresses the conversion timetable. September earnings must be converted by 28 October, rather than by the 28th day of the third subsequent month under the previous arrangement. Compliance records and transaction logs must be submitted through the MMA’s Foreign Exchange Portal.
The authorities have also strengthened controls over foreign-exchange transactions. The revised regime provides for penalties of up to MVR 1 million for prohibited foreign-currency transactions conducted above rates authorised by the central bank. It also introduces restrictions on publishing or disseminating unofficial exchange rates, including through media and digital channels, alongside stricter licensing requirements for money changers.
Money-exchange operators must obtain formal MMA licences and meet a mandatory $50,000 security-deposit requirement. Together, these measures seek to reduce unregulated currency dealing and direct more foreign-exchange transactions through authorised institutions.
The underlying objective is understandable. When dollars earned from tourism do not circulate adequately through the formal financial system, the central bank has fewer resources to meet import requirements and ease shortages. However, enforcement alone cannot resolve the economic incentives that drive businesses towards alternative channels.
The dollar paradox facing resorts
A Maldivian resort is an unusually foreign-currency-intensive business. Imported food and beverages, fuel, equipment, insurance, spare parts, overseas services and foreign-currency financing account for substantial operating requirements.
The resort earns dollars from international visitors but also needs those dollars to remain commercially viable.
The difficulty emerges when mandatory conversion into Rufiyaa is not matched by reliable access to foreign currency for legitimate international payments. Businesses may receive local currency through conversion only to face delays, additional costs or uncertainty when purchasing dollars to pay overseas suppliers, service foreign debt or settle foreign-currency obligations.
At a 40 per cent conversion threshold, this becomes a material consideration for working capital, margins and investment returns.
The regulatory framework recognises that a uniform requirement may create difficulties for certain operators. The MMA Governor has discretionary powers to reduce the threshold where businesses demonstrate that compliance would impair their ability to service foreign debt, pay mandatory foreign-currency taxes or meet essential overseas operating costs.
Such concessions may provide relief, but discretionary exemptions are not necessarily equivalent to a predictable, transparent system guaranteeing access to foreign currency when legitimate commercial obligations fall due.
Taxing offshore tourism transactions
The foreign-exchange measures also intersect with efforts to capture more value from tourism transactions arranged outside the Maldives.
Revisions to the Tourism Goods and Services Tax framework target foreign tour operators and online travel agencies, bringing offshore package and booking arrangements within a more clearly defined domestic tax-compliance regime.
Resorts and guesthouses are required to disclose transactions, booking values and revenue arrangements involving foreign travel intermediaries to the Maldives Inland Revenue Authority.
The policy challenge is to ensure that tourism-related economic activity is appropriately reported and taxed, even when booking and payment arrangements cross national borders. Yet taxation, foreign-exchange conversion and access to dollars are distinct issues. Their combined effect on resort cash flow and investment returns will matter to operators assessing future projects.
Commercial banks also face foreign-currency surrender obligations requiring them to transfer prescribed portions of foreign currency purchased to the MMA. The objective is to strengthen central-bank reserves and support essential imports, including fuel, food and pharmaceuticals.
The wider question is whether the system can improve the availability of dollars across the economy without undermining the businesses responsible for generating them.
Why Sri Lanka should look beyond tourist arrivals
This is where the story becomes particularly relevant for Sri Lanka.
Sri Lanka has experienced its own severe foreign-exchange crisis and has no reason to assume that its present position is permanently secure. Nevertheless, the country has an opportunity to compete for international tourism capital by offering investors a credible, predictable operating environment.
An investor evaluating an Indian Ocean resort does not compare beaches, room rates and tourist arrivals alone. The calculation includes financing costs, foreign-currency liquidity, imported operating expenses, debt servicing, taxation, regulatory predictability and the ability to repatriate legitimate returns.
The distinction is important. A tourist may change destinations for a week. An international hotel group may commit hundreds of millions of dollars to a project expected to operate for decades.
Sri Lanka should therefore resist treating the Maldives’ regulatory changes merely as an opportunity to attract displaced visitors. The larger prize is investment capital: new resorts, hotel-management agreements, integrated tourism developments and long-term hospitality infrastructure.
Colombo should engage international hotel groups and resort operators while investment decisions are still being made. Its proposition should combine a diversified tourism offering, connectivity, luxury and experiential tourism opportunities, infrastructure development and a transparent framework for managing foreign-currency earnings.
The objective should not be to promise investors that Sri Lanka will never experience currency pressure. It should be to demonstrate that legitimate foreign-currency obligations can be managed through predictable rules and functioning financial markets.
A window, not a guaranteed windfall
The opportunity is neither automatic nor permanent.
The Maldivian government could modify the 40 per cent threshold, expand exemptions or improve access to dollars through domestic banks. Its established luxury-tourism brand, existing resort infrastructure and international commercial relationships remain formidable advantages. A regulatory change does not mean international investors will abandon existing projects.
The more important question is what happens at the margin: where the next resort is built, where the next hotel-management agreement is signed and where international capital is committed.
For Sri Lanka, converting this opening into investment requires credible policy, efficient approvals, reliable infrastructure, regulatory stability and a clear commitment to protecting the commercial viability of tourism projects. Without these, any advantage created by developments elsewhere will remain theoretical.
Maldives’ foreign-exchange difficulties should not be celebrated. They should be studied.
The Maldives may have a foreign-exchange problem. Sri Lanka has an investment problem. One country is attempting to retain more of the dollars generated by tourism; the other needs to attract more foreign capital into its tourism economy.
If Colombo can align its tourism, investment, foreign-exchange and infrastructure policies intelligently, the Maldivian policy shift could create an opening that extends far beyond the next tourist arrival.
The question is whether Sri Lanka will recognise that opportunity while it is still a window, rather than discovering it after the capital has already chosen where to go.
(The author is a consultant specialising in data analytics, with a special focus on Sri Lanka’s future direction, sustainable energy, ESG, investments and telecommunications. He can be reached at [email protected].)