Thursday Oct 01, 2026
Thursday Oct 01, 2026
Thursday, 1 October 2026 00:20 - - {{hitsCtrl.values.hits}}
 Picture a small fleet of fishing boats pushing off from a lagoon at dawn. Every boatman rows hard. One pulls towards the reef, another towards the rocks, a third just paddles in places to stay near the warm shallows. By noon the whole fleet had burned a full day’s energy and gone nowhere, because nobody agreed on where “out” was. Scale that lagoon up to the size of a national economy, and you have a fair picture of how Sri Lanka has approached industrial policy for most of the past three decades.
Boats pointed in every direction
Sri Lanka does have an industrial policy, in the sense that it has dozens of them. A duty waiver here, a protective tariff there, a loan scheme for one sector, a state enterprise propping up another. What it has lacked is a single answer to the question, protect and support industry for what? To sell more abroad? To create jobs? To replace imports? Different arms of government have quietly answered that question differently, and the result has been supported scattered across sectors with no shared destination.
The evidence shows up clearly once you look at where the money and the protection actually go. Research published by the World Bank this year found that manufacturing absorbs roughly half of all new industrial policy measures introduced across South Asia since 2022, even though manufacturing employs only about one in seven workers in the region. Meanwhile, the quarter of non-agricultural sectors that received the least policy attention generated more than 80% of employment growth in Sri Lanka and Bangladesh over the past decade. In plain terms, the sectors we have been busiest protecting are not the ones actually hiring people. The trade data tells an even blunter story, when South Asian governments restricted imports, imports duly fell. When they tried to promote exports through incentives and subsidies, exports did not meaningfully rise. We have gotten good at building walls and much worse at building ships.
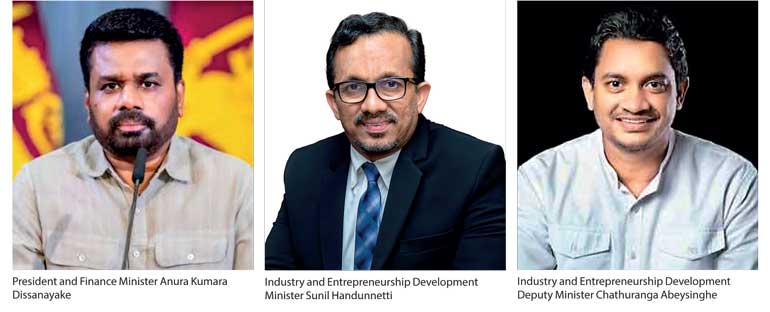
As part of a five-year strategic plan spanning 2023-2027, Sri Lanka’s Industry Ministry set out real targets, publicly announced in July 2024, lifting manufacturing’s share of GDP from 16% to 20%
by 2030, raising industrial exports from 14% to 20% of GDP, and more than doubling the share of the workforce engaged in entrepreneurship, from 2.8% to 7%. Two years into that announcement, discussions ahead of the 2027 Budget suggest the Government is aware the current approach is not delivering. Officials are reviewing long delayed industrial zones on Dambulla, Ingiriya, Valaichchenai, Millaniya, and Katunayake, held up by land allocation and infrastructure challenges and weighing whether to consolidate a tangle of institutions into a single new Entrepreneurship and Industry Transformation Authority. That is a reasonable instinct. Nevertheless, zones without a shared national target are just more shoreline, more places for boats to sit, not a bearing for them to follow.
The world rediscovers a tool it once distrusted
Sri Lanka is not choosing this moment to rethink industrial policy by accident. Almost every serious economy on earth is doing the same thing, for reasons that have less to do with textbook economics than with geopolitics. The pace of change is striking, annual industrial policy interventions worldwide have roughly doubled since 2020, with the US, China, the European Union and several East Asian economies among the most active users of these tools. Washington’s CHIPS and Science Act and Inflation Reduction Act embedded industrial policy into long term American law. Beijing’s decade-long Made in China 2025 program reshaped entire global supply chains, from electric vehicles to batteries, even as it drew retaliation from trading partners. By one recent estimate, government subsidies for battery technology alone reached roughly 30% of the entire global battery industry’s revenue in a single year.
The justification has shifted too. A decade ago, governments defended these interventions mainly on economic grounds, infant industries, market failures, and jobs. Increasingly now the language is about security, which country makes the chips your phone needs, which country controls the minerals your batteries need, which supply chain breaks first if a conflict erupts. Researchers tracking these shifts note that by 2025, industrial policy interventions were increasingly relying on trade restrictions and security based justifications rather than purely economic ones. A sign that the tool is being used as much for geopolitical positioning as for economic management.
South Asia has joined this wave with enthusiasm. Between 2016-19 and 2022-25, the average South Asian country roughly doubled the number of new industrial policies it introduced, outpacing the typical emerging economy by more than two to one. This is not, by itself, bad news. But the same World Bank research warns that the region is largely repeating the mistakes described above at a larger scale. Shielding home markets rather than building competitive exports. More policy activity has not translated into more dollars earned abroad.
Why direction matters more for an island short on dollars
For most countries this is a missed opportunity. For Sri Lanka it is closer to a structural danger, because of one number that rarely makes it into policy speeches. The country simply does not have enough foreign currency. In 2025, Sri Lanka’s trade deficit widened to roughly $ 7.9 billion even as exports hit a record high, because vehicle imports alone cost over $ 2 billion
and grew faster still. Gross official reserves stood at about $ 6.6 billion by the end of July 2026, built up through active Central Bank Dollar buying, respectable by the standards of the crisis years. Nevertheless, a meaningful share of that headline figure is tied up in short-term obligations, including currency swaps, so the reserves genuinely available to meet external payments are considerably smaller than the gross number suggests, and a thin cover against a debt bill that requires steady dollar income for years to come.
This is the detail that ought to reshape how Sri Lanka thinks about which industries deserve support. An industry that makes consumer items for the domestic market, however politically sensitive, earns no foreign exchange and therefore does nothing to ease the constraint that nearly broke the country in 2022. An industry that exports garments, processed food, ceramics, boat building components, or business services earns Dollars the country can actually use to import fuel, to service debt, to build reserves back up. When policy protection and subsidy are spread evenly across both kinds of industry, as they largely are today, the country is using scarce fiscal and regulatory firepower on activities that do not solve its most binding problem. A properly planned industrial policy for Sri Lanka is not just about picking winners, it is about picking winners that sell to the world. Because that is the one thing this economy structurally cannot afford to get wrong twice.
A country that picked a bearing
Vietnam offers a useful, unglamorous contrast, precisely because it started from a position not unlike Sri Lanka’s own a generation ago, poor, agrarian, recovering from decades of conflict. In 2018, Vietnamese leadership set out a national industrial development policy with a specific, public target, industry to exceed 40% of GDP by 2030, with processing and manufacturing carrying most of that weight, and exports explicitly prioritised over import replacement.
Vietnam’s industrial strategy documents, including the 2018 resolution and the sectoral plans that followed it, named the sub-sectors country that wanted electronics, machinery, textiles and footwear, automobile components rather than leaving every ministry to protect whatever fell under its own roof.
The results are visible in the trade figures. Vietnam’s electronics exports alone rose from around $ 46 billion
in 2015 to roughly $ 150 billion by late 2025, more than tripling in a decade, and now accounting for close to a third of all the country’s exports. Vietnam is now among the world’s top ten electronics exporters. None of this happened because Vietnam is uniquely gifted. It happened because the government picked a small number of exports facing sectors, built industrial zones with the roads, power and skilled labour those sectors actually needed, signed the trade agreements that gave manufacturers duty free access to rich markets, and then held to that plan for close to a decade under continuous single party leadership, insulated from the churn of individual ministers. The strategy survived changes in leadership because it had been written down as national policy, not tied to any one minister’s tenure.
It is worth being honest about the limits of this story too. A large share of Vietnam’s export earnings still flows through foreign multinationals rather than local firms, and researchers have found only modest technology transfer to Vietnamese suppliers so far. Picking the right sectors and pointing them outward is necessary, but not sufficient on its own. Making sure the domestic economy captures more of the value over time is the next harder chapter. Sri Lanka should learn from both halves of that story, the discipline of setting one target and holding it, and the caution not to mistake attracting factories for building an economy.
Setting Sri Lanka’s compass
None of this requires Sri Lanka to invent anything new. It requires choosing. The country already earns most of its export Dollars from a handful of activities, apparel and textiles alone account for a major share of merchandise exports, alongside tea, and a fast-growing information technology and business process sector. A properly planned policy would name these and a small number of adjacent sectors as the national priority, commit to them publicly with the same seriousness as a debt target, and then bend every other lever. The industrial zones under review, the proposed transformation authority, tax concessions, skill training, port and logistic investment toward making those specific sectors more competitive abroad, not merely more comfortable at home.
That also means resisting the temptation, visible in the current pre-Budget discussions, to treat every struggling State enterprise or every industrial estate as equally deserving of the same push. The struggling industries that operate targeting the domestic consumer market deserve reform for their own reasons, but they are not going to close Sri Lanka’s Dollar gap, and treating them as part of the same industrial strategy as export manufacturing blurs a distinction the country cannot afford to blur. Success should be measured not by how many industries get registered, but by how many additional Dollars those industries bring in each year.
The fleet analogy holds one more lesson. A boat that rows hardest is not necessarily the one that reaches open water. The one that reaches open water is the one whose crew agreed, before they pick up the oars, on which direction to face. Sri Lanka has no shortage of energy, ambition or entrepreneurial talent, what it has lacked is agreement on the bearing. With the world’s major economies now openly steering their industries towards strategic and export goals, and with regional competitors already a decade into their own version of this exercise, an island economy that keeps rowing in every direction at once is not standing still, it is falling behind.
(The author is an independent economic analyst and researcher focusing on Sri Lanka’s macroeconomic policy and post-crisis recovery. Views expressed are personal)