Tuesday Sep 29, 2026
Tuesday Sep 29, 2026
Tuesday, 29 September 2026 00:57 - - {{hitsCtrl.values.hits}}
A new incentive regime
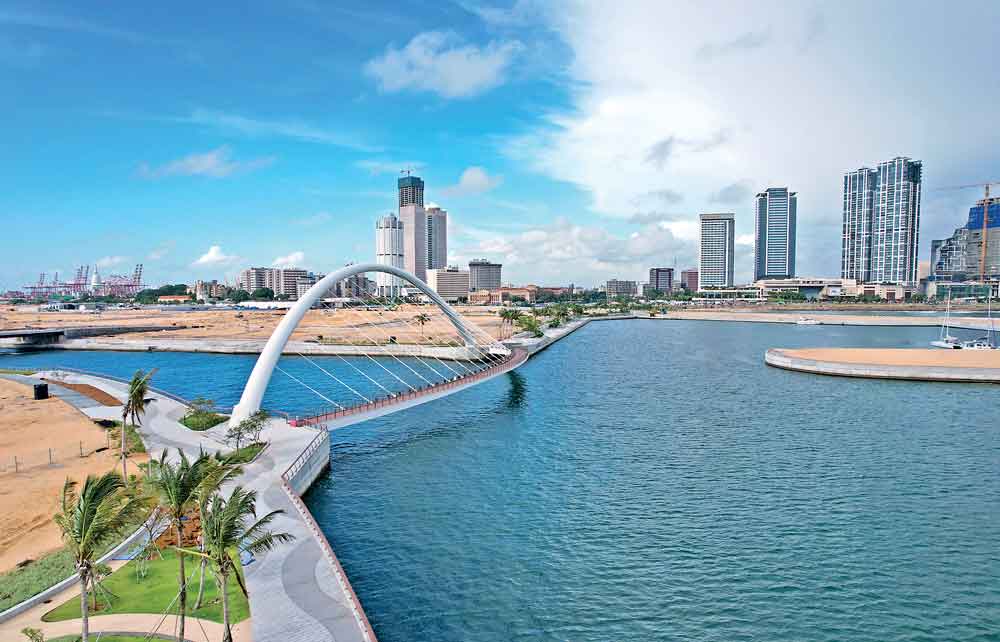
 An investment in the Port City Colombo will bring investors less benefits than it did just three years ago. The question to ask is whether that makes it less attractive or more credible to those looking for opportunities.
In under three years, Sri Lanka has made several changes to the Port City Colombo project, a Special Economic Zone built on reclaimed land in Colombo, aimed at positioning Sri Lanka as a regional financial and investment hub. It went from offering exceptionally long tax holidays to a shorter, more conditional, and closely supervised incentive regime. The September 2025 regulations, introduced under Gazette No. 2454/62, significantly curtailed fiscal incentives granted under the previous framework, while the 2026 amendment further tightened oversight and monitoring. The immediate debate is whether reducing these incentives has weakened Port City’s ability to attract investors. However, the revised incentive framework could provide a credible, stable, and commercially viable investment environment.
What changed in 2025 and 2026
Tax concessions still matter because they affect investor returns and location decisions, but their effectiveness depends on a broader investment environment, particularly regulatory certainty, institutional credibility, and macroeconomic stability. The original 2023 framework offered broad and generous fiscal incentives to Businesses of Strategic Importance (BSIs). It was introduced under the Colombo Port City Economic Commission Act No. 11 of 2021. Under this framework, Primary BSIs received a 25-year corporate income-tax exemption followed by another 10 years at a reduced rate. Secondary BSIs also received full or partial tax exemptions for up to 25 years. The earlier framework also allowed qualifying BSIs to benefit from exemptions under several other enactments. Moreover, the earlier framework did not impose a clear statutory end date on the accompanying employment income tax exemption for BSI employees under Section 35 of the 2021 Act.
The September 2025 regulations replaced this with a tiered incentive structure linking tax breaks to investment and employment targets. Under this framework, Primary BSIs now qualify for tax breaks ranging from 8-15 years, while Secondary BSIs receive a 7.5% concessionary tax rate for four years, replacing the earlier 25-year exemption.
The January 2026 Amendment also strengthened oversight of offshore banking. Banks are now explicitly subject to Central Bank supervision and prudential requirements covering capital adequacy, liquidity, risk management, disclosure, and auditing. It also curtailed the earlier employment income exemption, allowing a three-year transitional exemption for existing authorised businesses, while excluding newly authorised businesses. Collectively, these reforms shifted the focus away from an overwhelmingly incentive-led approach towards one that places greater emphasis on oversight and regulatory credibility.
 Port City’s success was not guaranteed because Sri Lanka offered generous tax incentives previously, nor will it fail simply because those holidays have been shortened. Its prosperity depends on offering investors a space that is commercially viable, efficiently governed, and protected from unpredictable policy shifts. The approval pipeline under the 2025 and 2026 reforms remains active, but whether this activity translates into durable, realised investment will be seen with time
The government itself made this shift explicit in the 2026 Budget Speech, framing the reforms as a move toward transparency and predictability. This domestic policy shift also aligns with Sri Lanka’s IMF supported effort to strengthen the tax exemption framework through time-bound incentives and closer monitoring of exempted business.
The change in regulations illustrates a central policy trade-off. On one hand, the curtailments may lower post-tax returns, reduce the appeal to tax-sensitive investors, and create concerns about future policy changes. On the other hand, the reforms could strengthen credibility. The incentives are now more performance-based and time-bound, with stronger monitoring and fiscal oversight. This could reduce the risk of unsustainable benefits being withdrawn abruptly later. In effect, investors may be giving up a more generous package in exchange for one that is more structured, transparent, and potentially sustainable. The 2025 regulations are stated to remain in force for five years unless earlier amended or repealed. This gives investors a defined five-year regulatory horizon. However, because the regulations can still be amended or repealed, five years should not be treated as a guarantee of lasting policy stability. Whether the credibility gain is sufficient to offset the cost of competitiveness remains to be seen.
What investors compare
Tax incentives represent only one component of the wider investment proposition. There’s a simple economic idea behind this. John Dunning’s ‘location advantage’ framework suggests that firms do not choose locations based on tax treatment alone. They compare tax incentives with accessibility, connectivity and wider operating conditions when choosing between locations. On this front, Sri Lanka’s Logistics Performance Index placed the country 73rd out of 139 countries in 2023, improving from 92nd place in 2018. Singapore’s 1st and the UAE’s 7th place rankings reflect stronger logistics systems and connectivity, illustrating the trade and infrastructure gap Port City must still close. As a trade-logistics measure, the index captures only part of the picture; Port City’s proposition also spans financial, professional, and digital services, where other factors matter more.
Further, long-term investors often emphasise clarity, predictability, and credibility of regulations alongside specific incentives offered within a jurisdiction. In practice, investors want clear eligibility criteria, effective dispute settlement mechanisms, investor protection and predictable rules. They also need confidence that governments will commit to maintaining rules. Port City’s own history speaks for this: the 2026 Amendment’s tightening of the earlier income-tax concession makes the issue of credible commitment particularly important. Investors must assess not only the value of an incentive today, but also how rules are changed, whether transitional protections are provided, and how predictable the framework remains over time.
Real options theory suggests that firms do not always invest immediately when uncertainty is high. Under such situations, firms may wait, invest on a smaller scale, or expand gradually as conditions become clearer. A more transparent and predictable policy environment can reduce this delay, even when incentives are less generous. Together, these perspectives show Port City’s competitiveness rests on its whole proposition, not on the size of its tax offer alone.
What the evidence shows, and does not show
Globally, Port City can benchmark itself against mature economic and financial hubs such as Singapore, the UAE’s free zones, and India’s GIFT City, though none of them are directly equivalent to its mixed-use SEZ model. According to the 2024 Worldwide Governance Indicators, Sri Lanka scored 46.0 on the 0-100 index for Government Effectiveness, compared with 75.8 for the UAE and 95.7 for Singapore. This indicator measures perceptions of public services, policy implementation, and the credibility of government decisions—all factors that matter to long-term investors. While they do not measure Port City itself, these gaps highlight the wider institutional environment within which its investment regime must operate. On sovereign risk, the credit rating agency Fitch rated the UAE and Singapore in their highest tiers ‘AA-’ (May 2026) and ‘AAA’ (April 2026), while rating Sri Lanka at ‘CCC+’ (October 2025). These ratings illustrate the very different sovereign-risk environments in which the respective hubs operate. While they do not measure Port City itself, country risk can influence financing conditions and investor confidence.
Cabinet’s approval of 77 BSI designations in April 2026 suggests that the reformed framework has not brought the approval pipeline to a halt. Whether this trend will translate into durable, realised investment, however, remains an open question.
A joint IMF, OECD, UN and World Bank report found that tax incentives are often not a major factor in investment decisions in low-income countries and were frequently reported as redundant. This cautions against assuming that more generous concessions alone will attract more investment.
Lessons from benchmark hubs
India’s GIFT City allows eligible International Financial Services Centre (IFSC) units to pay no tax at all for 20 of their first 25 years in operation. This is longer in duration than Port City’s current 8–15-year tiered corporate tax concessions, although the two regimes differ substantially in design and eligible activities.
Singapore and the UAE compete on more than tax packages alone. Singapore pairs its offer with strong infrastructure, financial depth, and regulatory consistency. The UAE combines its free-zone model with strong logistics and governance.
Although none of these jurisdictions are equivalent to Port City, all three suggest the same lesson: incentives alone are not enough. Port City’s package will only become genuinely competitive if backed by strong institutional design suited to its own purpose and context. The lesson is not that Port City must replicate any one of these models, but that the credibility of an incentive depends on the ecosystem in which it is offered.
What Sri Lanka should prioritise
Sri Lanka should prioritise a few key factors to attract investors. First, it should make regulatory changes more predictable. This means implementing clear rules, transparent eligibility criteria, and fewer discretionary changes that could increase uncertainty for investors.
Second, policymakers should recognise that Port City cannot operate as an isolated enclave. Its long-term prosperity relies on the broader macroeconomic stability of the country. The 2022 economic crisis showed that even well-designed investment zones remain vulnerable to wider economic instability. Maintaining fiscal sustainability, external stability, and low and stable inflation is therefore non-negotiable in the long run.
Third, Port City must strengthen its operational competitiveness through high-quality infrastructure and international connectivity. This must be supported by a capable, adequately resourced, and appropriately supervised Economic Commission that can provide efficient and predictable administration.
Port City’s success will also depend on integrating supplier networks, skills development, and knowledge transfer into the domestic economy. Equally important is regulatory integrity, including effective audits, safeguards against money laundering, clear ownership transparency, and proper tax-reporting, all of which reduce the risk of Port City becoming a channel for regulatory arbitrage.
The real test for Port City
Port City’s success was not guaranteed because Sri Lanka offered generous tax incentives previously, nor will it fail simply because those holidays have been shortened. Its prosperity depends on offering investors a space that is commercially viable, efficiently governed, and protected from unpredictable policy shifts. The approval pipeline under the 2025 and 2026 reforms remains active, but whether this activity translates into durable, realised investment will be seen with time. The real test for Port City’s success will not be the generosity of its fiscal incentives alone, but the quality and credibility of the investment environment built around them.
(The author works in the field of economic research. He has earned a BSc (Hons) in Economics and Politics from the University of London)
References:
Colombo Port City Economic Commission. 2023. “Clarification Regarding Statement.” November 14. https://www.portcitycolombo.gov.lk/news/20231114/colombo-port-city-economic-commission-clarification-regarding-statement.
Dunning, John H. 1988. “The Eclectic Paradigm of International Production: A Restatement and Some Possible Extensions.” Journal of International Business Studies 19 (1): 1–31.
Fitch Ratings. 2025. “Fitch Affirms Sri Lanka at ‘CCC+’.” October 1.
Fitch Ratings. 2026. “Fitch Affirms Singapore at ‘AAA’; Outlook Stable.” April 2.
Fitch Ratings. 2026. “Fitch Affirms United Arab Emirates at ‘AA-’; Outlook Stable.” May 22.
Government of Sri Lanka. 2023. Colombo Port City (Guidelines on the Grant of Exemptions or Incentives to Businesses of Strategic Importance) Regulations, No. 2 of 2023. Gazette Extraordinary No. 2343/60, August 4.
Government of Sri Lanka. 2025. Colombo Port City (Guidelines on the Grant of Exemptions or Incentives to Businesses of Strategic Importance) Regulations, No. 1 of 2025. Gazette Extraordinary No. 2454/62, September 20.
International Monetary Fund. 2025. “IMF Completes the Third Review under the Extended Fund Facility for Sri Lanka.” Press Release No. 25/053, February 28. https://www.imf.org/en/news/articles/2025/02/28/pr25053-sri-lanka-imf-completes-the-3rd-rev-under-the-eff.
International Monetary Fund, Organisation for Economic Co-operation and Development, United Nations, and World Bank. 2015. Options for Low Income Countries’ Effective and Efficient Use of Tax Incentives for Investment. Report to the G20 Development Working Group. https://www.imf.org/external/np/g20/pdf/101515.pdf.
Ministry of Finance, Sri Lanka. 2025. Budget Speech 2026. Colombo: Government of Sri Lanka. https://media.gov.lk/media-gallery/latest-news/3497-full-budget-speech-2026.
North, Douglass C., and Barry R. Weingast. 1989. “Constitutions and Commitment: The Evolution of Institutions Governing Public Choice in Seventeenth-Century England.” Journal of Economic History 49 (4): 803–32.
Parliament of Sri Lanka. 2021. Colombo Port City Economic Commission Act, No. 11 of 2021. https://www.parliament.lk/uploads/acts/gbills/english/6218.pdf.
Parliament of Sri Lanka. 2026. Colombo Port City Economic Commission (Amendment) Act, No. 1 of 2026. https://documents.gov.lk/view/acts/2026/1/01-2026_E.pdf.
World Bank. 2023. Logistics Performance Index 2023: Sri Lanka Country Scorecard.
World Bank. 2025. Worldwide Governance Indicators, with Source Data. https://datacatalogfiles.worldbank.org/ddh-published/0038026/DR0095947/wgidataset_with_sourcedata-2025.xlsx.