Tuesday Sep 22, 2026
Tuesday Sep 22, 2026
Tuesday, 22 September 2026 04:59 - - {{hitsCtrl.values.hits}}
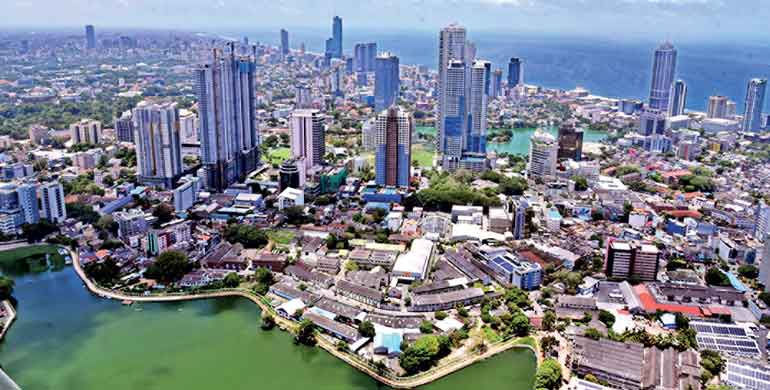
Four years ago, Sri Lanka stood at the edge of an economic abyss. Today, it stands on firmer ground, thanks to the authorities’ concerted reforms and the resilience of the Sri Lankan people.
As our IMF team concludes its discussions for the Seventh Review of the Extended Fund Facility and this year’s Article IV consultation, the headline numbers are telling.
Inflation, which shot to 70% and eroded household incomes during the crisis, has been tamed and is expected to settle around the CBSL’s 5% target. Public debt, once unsustainable, is back on a viable path following the debt restructuring. Reserves are being rebuilt, and tax revenue as a share of GDP has doubled in four years.
But the more important story lies behind the numbers: a sustained national effort, and a series of difficult but deliberate reforms—from a new Central Bank Act to a Public Financial Management Act, from implementing tax reforms to a governance action plan. These reforms did not merely restore calm; they added over two percentage points to cumulative growth between 2023 and 2025. Stability has already begun to pay dividends.
Yet stabilisation was never the destination. It was the foundation. And here lies the next chapter, which will be every bit as demanding as the one just written: the move from macroeconomic stabilisation to economic transformation.
Why is stability not enough? Because stability alone does not create jobs or raise living standards—and Sri Lanka’s growth problem was never a shortage of good projects or generous incentives.
Growth of that kind—jobs, private investment, exports, innovation—will not come from isolated interventions. It will require an environment in which businesses can plan, compete, and expand with confidence. Building that environment is the task ahead.
The reform agenda is well understood, and much of it is already in the authorities’ own plans. What’s needed now is a renewed push.
The reform agenda is well understood, and much of it is already in the authorities' own plans. What’s needed now is a renewed push
Streamline the thicket of business regulations and set up a genuine one-stop shop for investors. Close infrastructure gaps through better public investment management and well-governed partnerships with the private sector. Modernise land and labour markets so that resources flow to their most productive uses. Widen access to finance for the small businesses that create jobs. And lower trade barriers and modernise customs so that Sri Lankan firms can compete in global markets rather than shelter from them.
The payoff from these reforms can be substantial. Staying the current course would only lift growth modestly, as the impetus from recent reforms fades out. But an ambitious, comprehensive push across the full reform agenda could raise annual growth by around 1.4 percentage points over the next five years—across governance, business regulation, external markets, labour markets, and credit—reviving the foreign investment that has lain dormant, and marking the difference between medium-term growth of around 3.5% and 5% or higher.
Streamline the thicket of business regulations and set up a genuine one-stop shop for investors. Close infrastructure gaps through better public investment management and well-governed partnerships with the private sector. Modernise land and labor markets so that resources flow to their most productive uses. Widen access to finance for the small businesses that create jobs. And lower trade barriers and modernise customs so that Sri Lankan firms can compete in global markets rather than shelter from them
None of this is possible without sound public finances, and here the current debate over taxes deserves care. It is fair to ask whether some tax rates can come down while maintaining overall revenue, and the forthcoming Medium-Term Revenue Strategy is the right place to design a simpler, fairer, and more efficient system. But the goal must remain adequate revenue, because it is what funds growth. A country cannot grow without spending on what makes inclusive growth possible—infrastructure, education, productive investment, social spending—and it cannot spend reliably, through hard times, without a solid fiscal framework and the revenue buffers to withstand shocks.
Nor can any of this be separated from the effect it has on people. The adjustment since 2022 was borne by households, many of whom fell into hardship as the crisis deepened, poverty roughly doubled, and too many young people still struggle to find work. Strengthening the social safety net matters not only to protect the vulnerable but also to help put people back to productive work and ensure the benefits of economic growth are shared widely.
Strengthening the social safety net matters not only to protect the vulnerable but also to help put people back to productive work and ensure the benefits of economic growth are shared widely
Sri Lanka has already proven it can do the hard things. The reforms of the past four years were not easy, but they paid off. The next chapter calls for the same resolve—no longer to survive a crisis, but to build a more prosperous economy. That work is Sri Lanka’s to lead, and we intend to remain a firm partner.
(The author is a Deputy Division Chief in the Asia and Pacific Department (APD) of the IMF, and the Mission Chief for Sri Lanka. He has served as Mission Chief for New Zealand and Vanuatu, Deputy Mission Chief for Australia, and has also worked on Sweden and Denmark among other roles. Evan has extensive experience in monetary, financial sector and financial market issues, gained over many years in the IMF’s Monetary and Capital Markets Department, and as an emerging markets fixed-income strategist at Goldman Sachs and Citigroup in New York and London. He helped lead the IMF’s flagship Global Financial Stability Report and has authored numerous publications on macroeconomic and financial stability topics including on asset purchases by emerging market central banks and the determinants of capital flows. Evan holds a Ph.D. in Operations Research and Financial Engineering from Princeton University, and an M.A. in Financial Mathematics from Columbia University.)
Sri Lanka has already proven it can do the hard things. The reforms of the past four years were not easy, but they paid off. The next chapter calls for the same resolve—no longer to survive a crisis, but to build a more prosperous economy. That work is Sri Lanka's to lead, and we intend to remain a firm partner